
NEXTDC Prices A$1.1 Billion Convertible Notes to Fund Data-Centre Growth
NEXTDC priced 1.75% subordinated convertible notes due 2031, adding committed funding for its Australian data-centre development pipeline and lifting pro forma liquidity.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy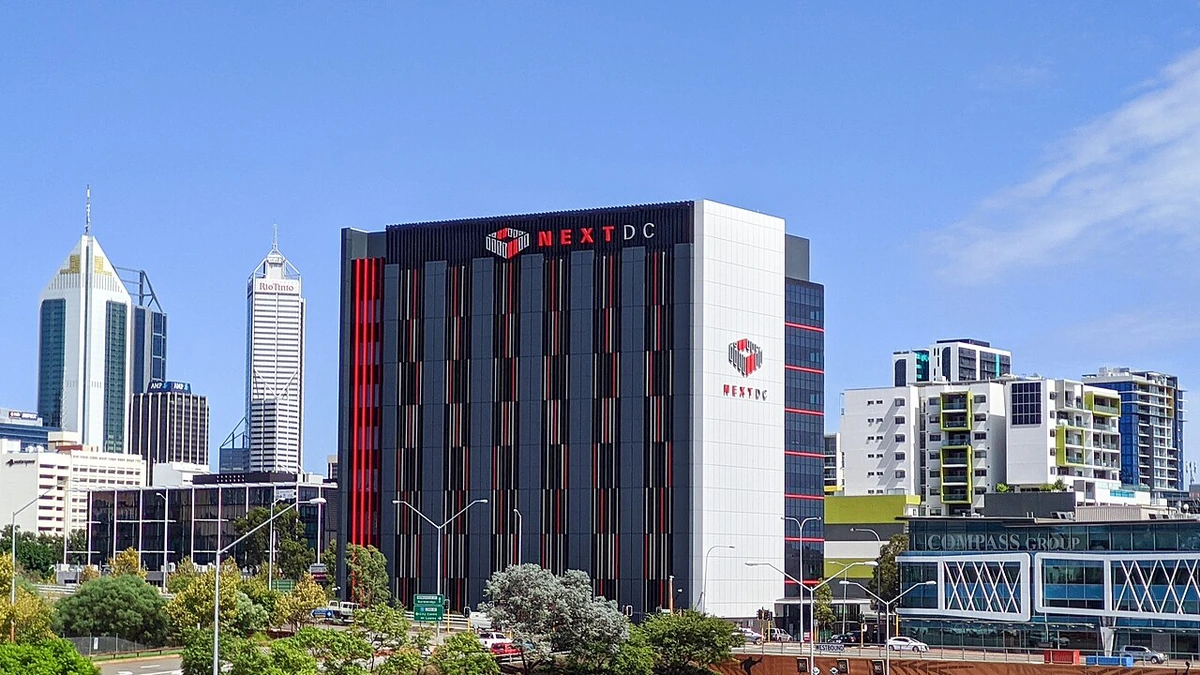
NEXTDC has priced A$1.1 billion of subordinated convertible notes, giving the Australian data-centre operator another large pool of committed funding as it pushes ahead with a build-out shaped by rising cloud and AI demand. The notes carry a 1.75% coupon and mature on 17 September 2031.
Management is framing the raise as another step in a broader capital strategy rather than a one-off funding patch. That matters because the group has already been expanding its liquidity base through senior debt and hybrid securities, while its contracted capacity pipeline has grown far faster than historical revenue.
In the priced announcement, NEXTDC said the offering should strengthen liquidity and provide committed funding for its development pipeline while preserving flexibility for further customer-led growth. Net proceeds are expected to be about A$1.006 billion after the cost of the capped-call hedges and before other costs.
Pricing locks in five-year funding at a 1.75% coupon
The final terms landed at the top of the coupon range laid out a day earlier, when NEXTDC launched the deal with an indicative 1.25% to 1.75% cash coupon. The initial conversion price was set at A$16.695 per share, a 32.5% premium to the A$12.60 reference share price. In practical terms, that allows NEXTDC to raise debt-like capital at a relatively low cash cost today while pushing any equity dilution out into the future and only at a materially higher share price.
The structure sits below senior debt in the capital stack. NEXTDC said the notes are direct, unsecured and subordinated obligations, ranking junior to its senior debt, equal with the A$750 million subordinated notes it issued in April 2026, and senior to hybrid securities and ordinary shares. That ranking helps explain why the coupon can sit below some other subordinated funding alternatives while still offering investors conversion upside if NEXTDC’s equity value continues to grow.
Several other terms are worth watching. The notes mature on 17 September 2031, but holders can require redemption at principal plus accrued interest on 17 September 2029. NEXTDC also retains the ability to satisfy conversions in cash rather than with shares, subject to the terms of the security. The instruments are expected to be admitted to the Vienna Multilateral Trading Facility rather than quoted on the ASX, which means they are being aimed at institutional debt investors rather than the local equity market.
For NEXTDC, the attraction is clear. Chief executive Craig Scroggie said the deal broadens the company’s investor base and preserves senior debt capacity. That is an important point for a business whose development timetable still depends on access to multiple pools of capital, not just a single debt instrument.
Expansion plans explain the need for more committed capital
The financing only makes sense in the context of how quickly NEXTDC’s operating pipeline has expanded. In a 21 July contracted-utilisation update, the company said pro forma contracted utilisation at 30 June 2026 had risen by 73MW since the previous update to 740MW, while the forward order book climbed to 565MW. NEXTDC said that forward order book is expected to convert progressively into billings, revenue and EBITDA between FY26 and FY30.
That operating backdrop helps explain why the balance sheet has been moving almost as quickly as the operating numbers. The priced notes announcement said NEXTDC reported pro forma available liquidity of A$8.676 billion at 30 June 2026, including A$876 million of cash, A$7.1 billion of undrawn senior debt facilities and A$700 million of undrawn commitments under its Hybrid Securities B Delayed Draw Series. On a pro forma basis, total liquidity would have been about A$9.776 billion before offering costs and the capped-call expense.
Readers looking for the broader backdrop can see the company’s latest operating snapshot on NEXTDC’s investor centre, which currently highlights FY26 net revenue of A$405.0 million, underlying EBITDA of A$248.8 million and contracted utilisation of 740.1MW. Those figures help show the mismatch that now defines the story: revenue is still growing at a far smaller dollar scale than the multibillion-dollar capital commitments required to build and fit out the next wave of data-centre capacity.
NEXTDC has been preparing for that funding burden for some time. Earlier this year it launched a A$1.0 billion hybrid securities offer backed by La Caisse and, before that, expanded debt facilities tied to national expansion and AI-infrastructure demand. The new convertible notes do not replace those measures. They add another layer to a financing stack designed to keep construction and customer delivery moving without exhausting senior debt headroom too early.
That layering carries trade-offs. More committed capital reduces funding risk around an ambitious build programme, but it also leaves investors with a more complex capital structure to assess. Equity holders now need to think not only about execution on new capacity, but also about how much future upside may eventually be shared with noteholders if the share price rises far enough to make conversion attractive.
Capped calls and the delta placement change the dilution picture
The most technical part of the announcement involves the capped-call hedges and the related delta placement. NEXTDC said it bought cash-settled call options from two financial institutions with a strike price equal to the initial conversion price and a cap price of A$21.42 per share, or 70% above the A$12.60 reference price. The upfront cost of those hedges is A$93.61 million.
Those options do not stop conversion from happening, nor do they reduce the number of shares that would be issued if the company elects physical settlement. What they are meant to do is offset part of the economic dilution or cash cost that would otherwise arise if the share price moves above the conversion price. The protection works only up to the cap. If NEXTDC’s shares rise above A$21.42, the company no longer has hedge cover for the additional upside.
The accompanying delta placement is also easy to misunderstand. About 18.6 million existing shares were placed at A$12.60 to help investors establish their initial hedge positions. NEXTDC said it will not issue new shares and will not receive any proceeds from that placement, so the exercise should not be confused with a conventional equity raising. Even so, the company acknowledged that hedging and trading activity linked to the convertible notes, the capped calls and the delta placement may affect trading in the ordinary shares from time to time.
The next concrete milestone is settlement, which is expected on 17 September 2026, assuming customary conditions are met. After that, the focus shifts from bookbuild mechanics to execution: how quickly NEXTDC can turn its contracted pipeline into billings and whether the additional capital helps it keep pace with the infrastructure demands created by large cloud and AI customers.
More from Investing
Latest News
View all news- FTC, USDA Launch Joint Inquiry Into Agricultural Equipment Market Practices
- VAALCO Completes Gabon Phase 3 Drilling as ETSEM-3H Starts at About 2,000 BOPD
- U.S. Crude Inventories Fall 3.2 Million Barrels in Latest EIA Report
- UK Trade Remedies Authority Proposes Five-Year Anti-Dumping Duty on Chinese Rutile Titanium Dioxide
- OCC Launches Direct Payments-Fraud Reporting Tool for Community Banks
