
Oklahoma Overhauls Licensing Rules for Money Transmission Businesses
A new Oklahoma law changes licensing fees, financial safeguards and oversight for money transmitters, with added requirements for payroll services.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy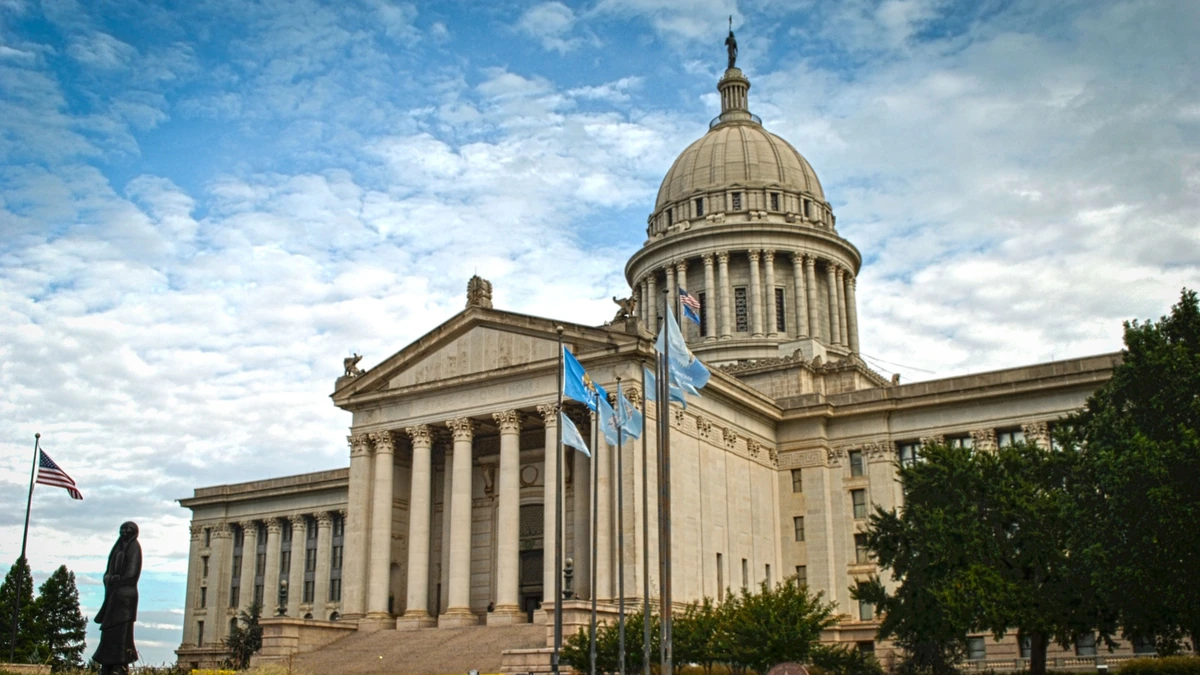
Oklahoma has put a new regulatory framework for money transmission businesses into effect, changing how companies obtain licenses, protect customer funds and report to state supervisors. The Oklahoma Money Transmission Modernization Act took effect November 1, 2026, with higher specified licensing fees and a broader set of operating requirements for businesses that fall within the law.
The overhaul comes through House Bill 3521, which became law on May 13 without Gov. Kevin Stitt’s signature. It replaces provisions of the Oklahoma Financial Transaction Reporting Act and establishes a new statutory framework administered by the Oklahoma State Banking Department. The change is more extensive than an adjustment to an application form: it addresses entry into the market, financial resources, the use of local agents and the state’s enforcement powers.
The legislative record for HB 3521 identifies the enacted measure and its final version. It covers nonexempt businesses engaged in money transmission, a category that can include companies handling customer payments, transferring funds or issuing certain payment products. The precise activity and the law’s exemptions determine whether a particular business needs an Oklahoma license.
Oklahoma is also moving toward licensing and examination practices that are more consistent with those used by other states. The statute permits the Banking Commissioner to use the Nationwide Multistate Licensing System and Registry, known as NMLS, for applications and ongoing administration. A common filing system can reduce duplicative paperwork, but a company must still meet Oklahoma’s requirements; registration through NMLS is not a nationwide license.
New applications carry $4,000 and $3,000 fees
Under the new framework, a nonexempt applicant must obtain a state license before conducting money transmission. The license is not transferable or assignable. The legislation sets a nonrefundable $4,000 application fee and a separate nonrefundable $3,000 license fee, with applicants also potentially responsible for the reasonable costs of an on-site investigation. It provides for a $3,000 annual renewal fee.
Those amounts matter to firms assessing the cost of entering Oklahoma, particularly smaller businesses that may already hold licenses in several states. The $4,000 application charge and $3,000 license charge serve different purposes and should not be mistaken for a single recurring $7,000 annual fee. Renewal is a separate process, while the broader cost of compliance also includes financial safeguards and recordkeeping.
Applications require more than payment. The act calls for information about business operations, ownership and control, financial condition and people in key roles. The Banking Commissioner may review applicants’ fitness and can investigate whether the legal standards for holding a license are met. The law also establishes a process for written notice when an application is denied and provides an avenue to appeal a denial to the Oklahoma State Banking Board.
Changes in ownership receive their own scrutiny. The law generally requires advance approval before a person acquires control of a licensed business, subject to specified exceptions, and provides for a nonrefundable $4,000 fee for a control application. A license cannot simply be passed to a buyer as if it were an ordinary business asset. These provisions make licensing an ongoing obligation rather than a one-time approval.
The department’s money-transmitter licensing page directs new license applications through NMLS and provides filing materials for licensees. Businesses dealing with the change must distinguish the requirements of the new law from older forms and rules that applied before November 1.
New rules cover customer funds and authorized delegates
The act revises standards for a licensee’s tangible net worth and the financial security it must maintain, including surety bonds or approved alternatives. It also requires permissible investments to support outstanding money transmission obligations. The purpose is to ensure that a company handling funds on behalf of customers maintains resources against the obligations it has taken on, rather than relying solely on a license issued at the outset.
Those requirements operate differently. Net worth measures the licensee’s financial position; a bond provides a separate form of security; and permissible investments address assets available against money transmission liabilities. Compliance with one does not eliminate the others. The Banking Commissioner is given authority under specified circumstances to adjust or administer parts of the financial requirements, so the applicable amount can depend on the company’s activities and condition.
The new law also addresses how licensed businesses operate through authorized delegates, such as third parties that provide money transmission services on a licensee’s behalf. It calls for written agreements and makes licensees responsible for ensuring their delegates operate within the legal framework. Delegates may not simply appoint further subdelegates. These rules are relevant to businesses whose consumer-facing locations are operated by partners rather than company employees.
For customers, the statute sets requirements concerning receipts, the forwarding of money and refunds. It also recognizes circumstances in which a provider may have reason to suspect fraud or another legal violation. These provisions establish duties for transmitters, but they do not mean every payment can always be reversed or that a license guarantees funds against every loss.
Reporting continues after a license is granted. The law provides for financial statements, reports about the business and its authorized delegates, record retention and notice of certain material events. Payroll processing also receives specific treatment. Senate amendments removed payroll service providers from a proposed exemption, and the enacted measure provides a transition mechanism for businesses newly brought under the licensing requirement. Companies providing payroll services therefore need to assess whether their particular activity qualifies and what transition provisions apply.
Regulators gain broader examination and enforcement powers
The Oklahoma Banking Commissioner may examine licensees, require records, issue subpoenas and coordinate with regulators in other states. The legislation supports multistate supervision while preserving Oklahoma’s ability to investigate a business or an authorized delegate directly. Licensees can be required to cover reasonable examination costs, making supervisory expenses another consideration for firms operating in the state.
Enforcement provisions include cease-and-desist orders, suspension or revocation of licenses and administrative fines of up to $5,000 per violation. The statute also establishes Class D1 felony offenses for knowingly conducting activities that require a license without holding one and for specified intentional false statements or material omissions in required records. These criminal provisions concern defined conduct; they do not make every late filing or compliance error a felony.
The overhaul follows a separate Oklahoma law governing digital asset kiosks. Senate Bill 1083, enacted in 2025, required operators of those machines to hold money transmitter licenses. HB 3521 is the broader rewrite of the money transmission framework, not the first law to bring kiosk operators under state licensing. Businesses dealing in digital assets must consider both the broader statutory definitions and requirements applicable to their activities.
For payroll processors brought into the licensing system, the law provides a separate transition period and allows the Banking Commissioner to extend it in specified circumstances. The terms of that transition, and any departmental guidance on applications, will determine the immediate filing timetable for those businesses.
More from Banking
Latest News
View all news- Virginia Restricts SNAP Spending on Soda and Certain Energy Drinks
- Texas Raises Assigned-Risk Auto Insurance Rates for Private and Commercial Vehicles
- HealthCare.gov Opens Enrollment for 2027 Health Insurance Coverage
- New Federal Rules Limit How Medical Billing Disputes Can Be Batched
- Federal Sentencing Guidelines Update Financial Penalties for Economic Crimes
