U.S. Natural Gas Storage Rises by 20 Billion Cubic Feet, EIA Reports
U.S. inventories reached 3,882 billion cubic feet, standing 80 Bcf above their five-year average but 66 Bcf below the year-earlier level.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy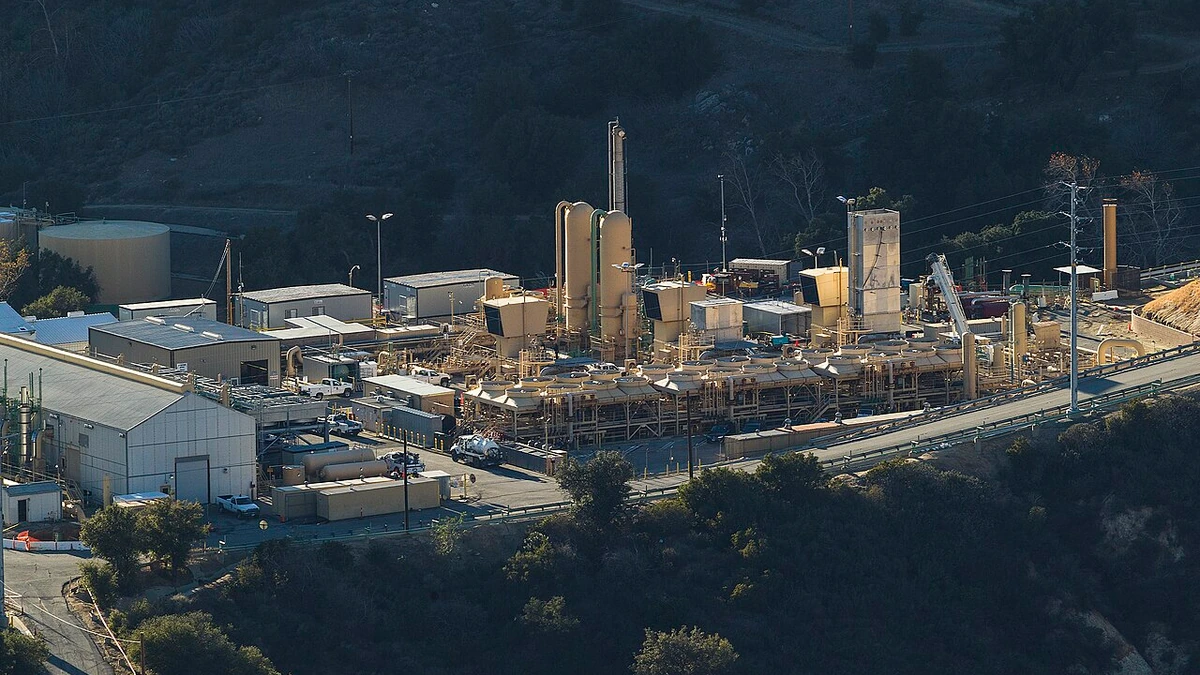
U.S. natural gas inventories rose by 20 billion cubic feet last week, a much smaller increase than the previous week’s build, as the country moved further into the winter heating season. Working gas held in underground storage across the Lower 48 states stood at 3,882 billion cubic feet (Bcf) on Friday, November 13, the U.S. Energy Information Administration reported Thursday.
The latest figures leave stocks 80 Bcf, or 2.1%, above the five-year average for the same period. They are also 66 Bcf, or 1.7%, below the level recorded a year earlier. Those comparisons give a more measured picture of supplies than the weekly increase alone: inventories remain above their recent seasonal norm, but are not as high as last November.
The agency’s Weekly Natural Gas Storage Report, released November 19, covers changes through November 13 rather than conditions on the publication date. It is a closely followed measure of how much natural gas is available for withdrawal from storage as demand for heating begins to rise.
Weekly injection slows sharply from early November
The 20 Bcf addition follows a 61 Bcf increase in the week ended November 6. That earlier report put U.S. working gas at 3,862 Bcf. The latest build was therefore 41 Bcf smaller, although inventories continued to increase on a net basis rather than decline.
The pace had already moderated from the larger autumn additions. EIA data showed storage growing by 80 Bcf in the week ended October 23 and by 77 Bcf in the week ended October 30. The move down to 20 Bcf in the latest week illustrates how quickly the weekly balance can change as the market approaches the period when heating consumption ordinarily leads to withdrawals.
A slower build is not, by itself, proof that supply has become tight. Weekly storage movements reflect the balance between gas entering and leaving underground facilities, not a direct measurement of production or household demand. Weather, electricity generation, industrial consumption, exports and other factors can affect that balance. The storage report does not isolate the contribution of each factor to the latest increase.
At 3,882 Bcf, total inventories also remained within the range observed for the corresponding week over the past five years, according to the agency. That matters because the headline change is small relative to the amount of gas already in storage. The five-year comparison is a seasonal benchmark, rather than a prediction of how much gas will be needed later in winter.
The year-over-year shortfall provides a different reference point. Storage stood at 3,948 Bcf in the corresponding week of 2025, compared with a five-year average of 3,802 Bcf for the latest reporting week. Both statements can be true at once: supplies are slightly above their recent norm and still below last year’s unusually higher level. Neither comparison alone determines the direction of natural gas prices.
South Central facilities account for most of the build
The regional figures show that the national increase was far from uniform. The South Central region added 13 Bcf, taking its working gas inventories to 1,248 Bcf. That region accounted for about two-thirds of the 20 Bcf net rise reported nationwide.
Within South Central, salt-cavern storage increased by 11 Bcf to 323 Bcf, while nonsalt storage rose by 1 Bcf to 925 Bcf. EIA notes that totals may differ slightly from the sum of individual components because the numbers are rounded independently. Salt caverns are designed to support relatively rapid injections and withdrawals, making their weekly movements particularly relevant to the balance in that region.
Despite the week’s increase, South Central inventories were 68 Bcf below their year-earlier level and 3 Bcf below the five-year average. The national surplus to the seasonal average therefore did not extend to every part of the country.
The East region reported no weekly change, leaving stocks at 938 Bcf. The Midwest registered a 1 Bcf withdrawal, bringing its total down to 1,128 Bcf. These two regions nevertheless held 30 Bcf and 23 Bcf more, respectively, than their five-year averages for the same week.
Further west, the Mountain region recorded a 3 Bcf increase to 265 Bcf, and Pacific storage rose by 5 Bcf to 303 Bcf. Both remained below their year-earlier levels, even though each was above its own five-year average. The geographic differences are important when assessing the system, since a nationwide inventory figure cannot describe every region’s available supplies or storage conditions.
Winter outlook remains sensitive to weather
The new storage reading arrives after EIA revised its near-term winter outlook in response to a warm start to November. In its November 10 Short-Term Energy Outlook, the agency raised its forecast for end-November inventories by about 67 Bcf from the previous month’s projection. That forecast was prepared before the latest weekly storage figures became available.
EIA also projected that the Henry Hub benchmark natural gas spot price would average $2.87 per million British thermal units from November through March, 16% below the forecast it had issued a month earlier. This was an estimate based on expected weather, supplies and consumption, not an observed price or a forecast mechanically determined by the 20 Bcf storage build.
Weather is a major source of uncertainty because colder conditions can quickly increase demand for gas used to heat buildings. The amount available in storage at the beginning of winter provides a buffer, but the rate at which it is drawn down also depends on production and the flow of gas to power generators, industrial users and export facilities. A modest surplus to the five-year average does not remove exposure to an extended cold spell.
Longer-term supply and demand are also changing. In its November outlook, EIA projected growth in gross U.S. liquefied natural gas exports from about 15 Bcf per day in 2025 to about 19 Bcf per day in 2027 as export facilities expand. That is a forecast over several years, rather than an explanation for the single week’s storage result. It does, however, show why the balance between domestic production, consumption and overseas demand remains relevant to future inventories.
For now, the latest EIA figures show a late-season increase that was much smaller than the prior week’s build, with most of the additional gas concentrated in South Central storage. The report does not establish a market-price reaction, and it would be premature to interpret one weekly reading as a lasting change in winter supply conditions.
The next scheduled storage report is due Wednesday, November 25, at noon Eastern time, an adjustment from the usual Thursday schedule for Thanksgiving. It will show whether inventories continued to rise or began a net withdrawal as the heating season progressed.
More News
Latest News
View all news- Walmart Raises Full-Year Outlook After Revenue Climbs 5.2% in Third Quarter
- RBI Absorbs ₹11,682 Crore Through Reverse Repo Auction at 5.49%
- U.S. Leading Economic Index Falls 0.3% in October as Housing Permits Weaken
- U.S. Jobless Claims Rise to 203,000 as Continuing Claims Jump by 70,000
- Williams-Sonoma Reports 21% EPS Growth, Helped by Tariff Refunds