
U.S. Steel Import Permits Dip in September as Census Data Arrive
September steel import license applications edged down 0.2%, but finished-steel requests rose. Actual Census import volumes require a separate comparison.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy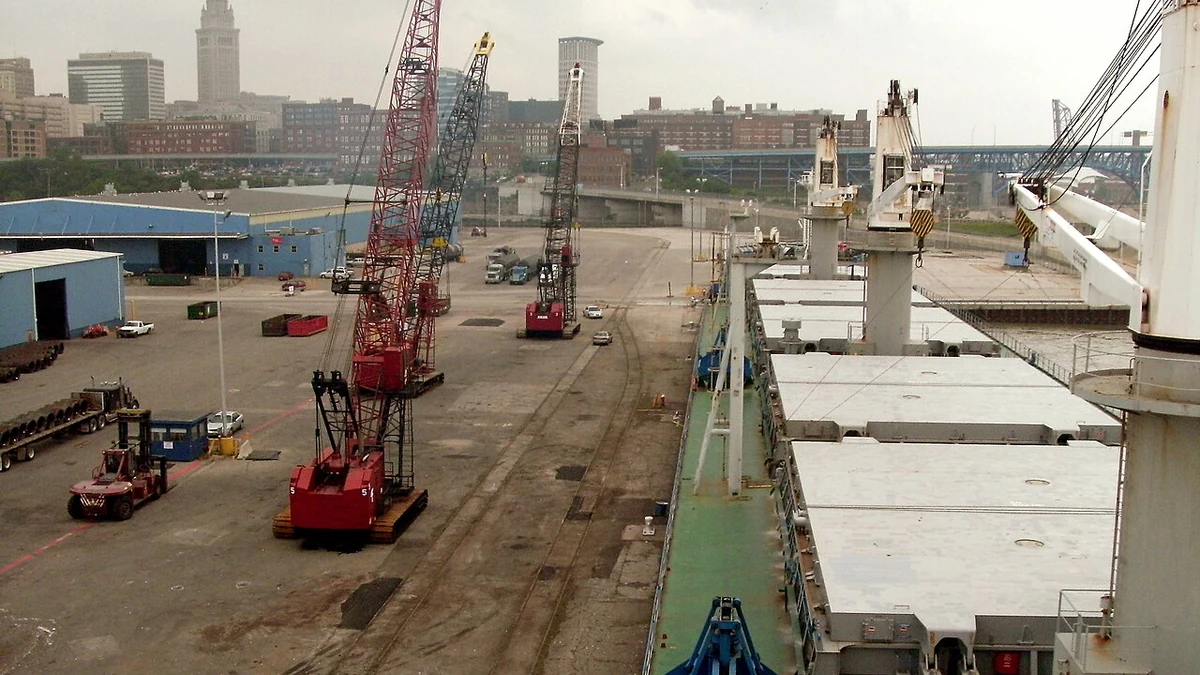
U.S. steel import permit applications edged lower in September, offering an early indication of softer inbound steel demand even as applications for finished products increased. The American Iron and Steel Institute (AISI) reported 2.492 million net tons in September permits, down 0.2% from August permit volume. The more detailed Census Bureau release on actual September imports is a separate measure and should not be confused with those license applications.
The numbers arrive as the U.S. Census Bureau lists its September preliminary steel-import report for October 27, 2026. The Census steel-release archive includes a September preliminary entry, following the August final and preliminary reports. The figures discussed here therefore distinguish September license applications from earlier confirmed import volumes; the two series are not interchangeable.
That distinction matters for steelmakers, importers and construction or manufacturing buyers trying to gauge supply. A small change in requests for import licenses is one piece of evidence about the flow of metal into the country, but it is not a final count of cargo that cleared U.S. Customs during the month.
September permits ease, but finished-steel applications increase
AISI’s October 8 analysis of September licensing data reported 2,492,000 net tons of total steel permit applications. August’s comparable license total was 2,499,000 net tons. Against the 2,515,000 net tons of actual August imports cited in the same release, September’s permit tally was 0.9% lower. Those are two different comparisons: permit applications against permit applications, and permits against the latest final import figure.
Finished-steel applications moved in the opposite direction. September permits covered 1,671,000 net tons of finished steel, 2.1% above the August final finished-import total of 1,636,000 net tons. This means the overall decline in applications should not be read as a uniform reduction across every type of imported steel. The product mix can move differently from the total, especially when semi-finished material is included in the broader measure.
The industry’s year-to-date comparison was still weaker than a year earlier. For the first nine months of 2026, counting final import data through August and September permit applications, AISI calculated total steel imports of 18.567 million net tons and finished imports of 13.042 million net tons. Those figures represented declines of 8.5% and 13.5%, respectively, from the comparable period of 2025. Because September is estimated using permits, the figures should not be treated as nine months of final Customs import records.
AISI estimated that imports accounted for 19% of the U.S. finished-steel market in September, compared with an estimated 16% over the year to date. The market-share estimate is not itself proof that more steel arrived during September than August. Changes in domestic shipments and the timing of licensing can affect a monthly share estimate.
Why the Census import tally and permit data may differ
Steel import licenses are generally requested before entry documentation is completed. The Commerce Department’s Steel Import Monitoring and Analysis program, known as SIMA, publishes information from those applications to give the industry an earlier look at potential inbound shipments. Census reports subsequently measure imports using trade records. The earlier signal is useful precisely because it arrives before the full import statistics, not because it is identical to them.
Importers can change shipment timing, quantities or sourcing after submitting their license applications. Some requested tonnage may not arrive in the month expected, and the information in applications can be revised. AISI’s September release explicitly cautioned that license figures can either understate or overstate subsequent actual imports. That is why its September 2.492 million net tons should never be relabeled as the Census Bureau’s preliminary September import volume.
The difference is visible in the preceding month’s reports. On September 24, AISI cited preliminary Census-based August imports of 2,345,954 net tons, including 1,599,537 net tons of finished products. It said those figures were 3.4% and 2.2% higher than July, respectively. By October 8, the association’s September permit analysis used final August figures of 2,515,000 net tons overall and 1,636,000 net tons of finished steel. The updated baseline can materially change a month-on-month comparison.
Census also reports steel in metric tons and dollar values, while AISI commonly presents totals in U.S. net tons. A net ton is 2,000 pounds, whereas a metric ton is roughly 2,205 pounds. Readers comparing two releases need to check the units as well as whether each number is preliminary, final or permit-based. A movement in import value can also differ from a movement in physical tonnage because product prices and mix change.
Country trends and trade policy complicate the picture
The September permits did not point to the same direction for every supplying country. South Korea was the largest origin in AISI’s September application data at 461,000 net tons, up 7.5% from its August final import total. Mexico followed with 311,000 net tons, an increase of 23%. By contrast, Brazil’s 279,000 net tons of applications were 20.5% below August final imports, and Canada’s 255,000 net tons were down 14%. Vietnam accounted for 195,000 net tons of permits, up 23%.
Such differences are significant when weighing the competitive pressures facing domestic producers. A modest decline in aggregate license volume can coexist with larger increases from individual suppliers, and those shifts can be concentrated in particular product categories. AISI reported especially large percentage increases in permit requests for standard rails, railroad accessories and tool steel compared with August final imports. Those sharp rates of change do not, by themselves, establish how much tonnage moved in each category.
Trade restrictions are another part of the background, although the licensing numbers do not establish that tariffs caused September’s change. U.S. Customs and Border Protection has documented the increase in Section 232 tariffs on many steel products to 50% beginning June 4, 2025, with important country and product exceptions. The cost of those duties can affect purchasing choices, but shifts in U.S. demand, delivery schedules, prices and the availability of domestic substitutes may also influence orders.
The Commerce Department’s SIMA monitor is intended to make these patterns easier to track between Census releases. For businesses relying on imported sheets, pipe, bar or specialty grades, the most informative comparison will be between the final August records, September’s actual preliminary imports and the later September revisions, using consistent product categories and units.
The Census Bureau schedules its preliminary October steel-import release for November 25, 2026. By then, additional revisions and a further month of licensing information can help distinguish a sustained change in the import trend from a short-term variation in shipment timing.
More News
Latest News
View all news- UPS Revenue Climbs 6.7% to $22.9 Billion as Company Raises 2026 Outlook
- Richmond Fed Manufacturing Index Holds at Minus 2 as New Orders Weaken
- FTC Begins $15.8 Million Refund Distribution to 2.1 Million Cleo AI Customers
- U.S. Home Prices Rise 0.3% in August, FHFA Reports
- Coca-Cola Raises 2026 Guidance After Third-Quarter Revenue Grows 7%
