
German Export Expectations Fall as Auto Industry Turns Negative Again
The ifo Institute’s export expectations index fell to 8.0 points in September from 9.8 in August, with automakers once again expecting exports to decline while several other industrial sectors remained positive.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy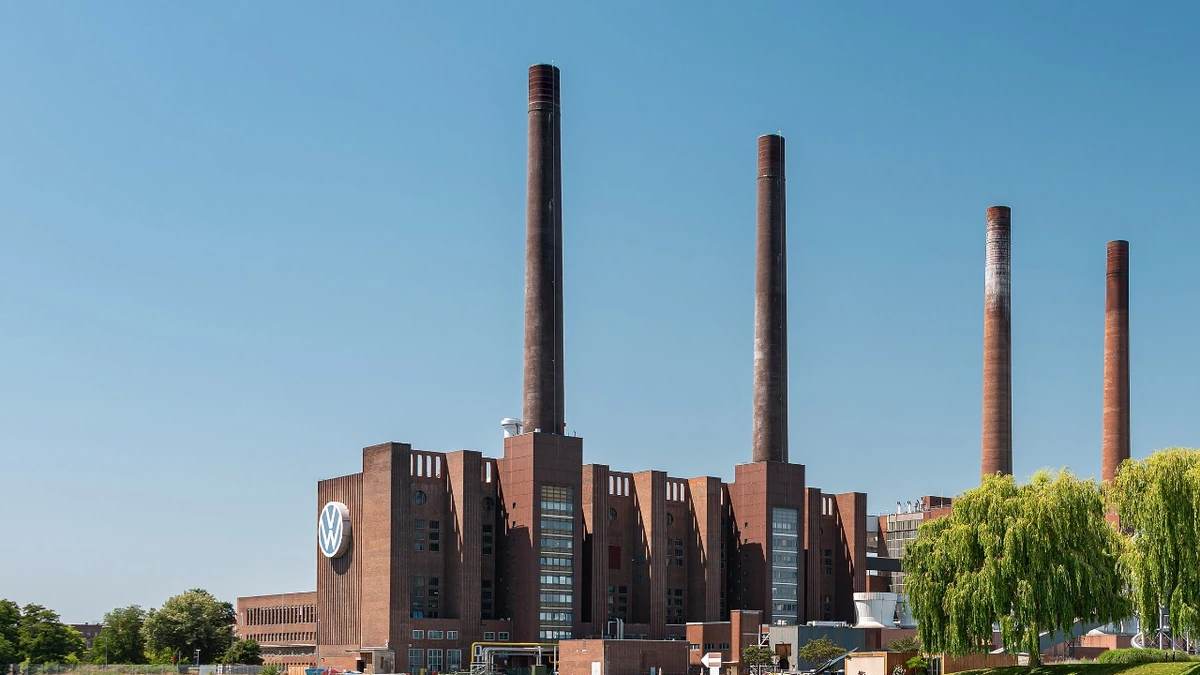
German exporters became less optimistic in September, with the ifo Export Expectations falling to 8.0 points from 9.8 in August. The main reversal came from the automotive industry, where manufacturers once again expect exports to decline after a more upbeat assessment a month earlier.
The pullback does not amount to a broad collapse in export sentiment. The ifo Institute said a majority of companies remain confident, and several important industrial sectors still expect foreign sales to rise. That makes the September reading a more uneven signal: auto manufacturers have turned cautious again, while parts of Germany’s machinery, electrical and technology-related manufacturing base continue to anticipate growth abroad.
In its September export expectations release, ifo identified the automotive industry as the primary reason for the decline in the overall indicator. The institute’s survey is designed to provide a timely view of export manufacturers’ expectations, so the 8.0-point reading should be understood as a sentiment indicator rather than a forecast that German exports will increase by 8%.
Autos reverse a one-month improvement
The latest result is notable because the auto sector had only recently become more positive. Ifo’s August survey described a sharp improvement in export expectations across German industry and said carmakers were much more optimistic about their foreign-sales prospects. September erased that improvement for autos, putting the industry back among the sectors expecting exports to fall.
That reversal fits with other official data showing pressure on Germany’s car business, although the different statistics measure different things and should not be treated as interchangeable. Destatis reported this week that Germany exported about 2.0 million new passenger cars worth 73.5 billion euros from January through July. The number of cars exported was 4.0% lower than in the same period of 2025, while the value of those exports fell 8.9%.
Production data have also been volatile. German automotive output fell 9.2% in July from June on a seasonally and calendar-adjusted basis. Destatis said a multi-week production shutdown was likely one of the main factors behind that monthly decline. The figure therefore should not be read as a direct explanation for September’s export sentiment, but it adds to evidence that the industry’s recent operating picture has been uneven rather than steadily improving.
Export optimism remains uneven across industry
Outside autos, the September survey was considerably firmer. Ifo said expectations in mechanical engineering improved substantially. Manufacturers of electrical equipment, as well as producers of data-processing equipment and electronic and optical products, also expect exports to rise. Beverage producers were particularly positive.
Other branches remain weak. Companies in metal production and processing still expect declining exports, as do businesses in the paper industry. The mix helps explain why the headline index stayed positive even though it slipped from August: the deterioration was concentrated enough to pull the overall reading down, but it did not reverse the more constructive outlook reported across several other manufacturing segments.
Recent trade figures tell a similarly mixed story. German goods exports totaled 138.2 billion euros in July on a calendar and seasonally adjusted basis, down 0.8% from June but 6.1% higher than a year earlier. Exports to European Union countries fell 1.6% from the previous month, while shipments to non-EU countries edged up 0.2%. Within major destinations, exports to the United States rose sharply from June, while exports to China and the United Kingdom declined.
Those destination-level swings matter for a manufacturing economy whose sectors have different exposures to overseas markets. Ifo’s August release had highlighted strong export activity toward the European Union and continuing weakness toward China. September’s industry breakdown suggests that the direction of foreign demand is still being felt differently across manufacturers rather than producing one uniform export cycle.
Hard data show why the auto signal matters
Germany’s auto industry remains large enough that a change in manufacturers’ expectations can materially affect the overall export mood. The sector’s latest production weakness came at the same time that broader industrial production fell 1.1% in July from June. In the official July production report, Destatis said the automotive decline was the main contributor to the monthly drop in industrial output, while higher energy production partly offset the weakness.
The wider export backdrop is not uniformly negative. Germany’s second-quarter national accounts showed exports of goods and services rising 2.0% from the first quarter after price, seasonal and calendar adjustment, with goods exports up 2.6%. Compared with the second quarter of 2025, price-adjusted goods exports were 5.0% higher. Destatis attributed much of that year-on-year increase to products including chemicals, data-processing equipment, electrical and optical goods, and other transport equipment, a pattern that broadly aligns with the stronger areas identified in ifo’s latest survey.
For now, September points to a loss of momentum rather than a wholesale reversal in German export expectations. The main question is whether the renewed caution among carmakers persists or proves temporary while other industries continue to expect growth abroad. Ifo’s next scheduled Export Expectations release is due on October 27, providing the next direct read on whether the auto-sector setback spreads or remains concentrated.
More News
Latest News
View all news- Brightline Florida Reaches Restructuring Deal With $490 Million in New Financing
- Delek US Prices $400 Million of 0% Convertible Senior Notes
- Nauticus Robotics Says Strategic Investor May Invest Up to $50 Million
- Japan’s 3-Month Bill Auction Clears at 1.2555% Average Yield
- Linjemontage Begins Nasdaq Stockholm Trading After SEK 658 Million IPO
