
Bank of Japan Balance Sheet Shrinks 10.1% as JGB Holdings Fall 9.5%
The central bank’s total assets fell to ¥625.0 trillion at end-September as reduced bond purchases and lower lending accelerated its balance-sheet runoff.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy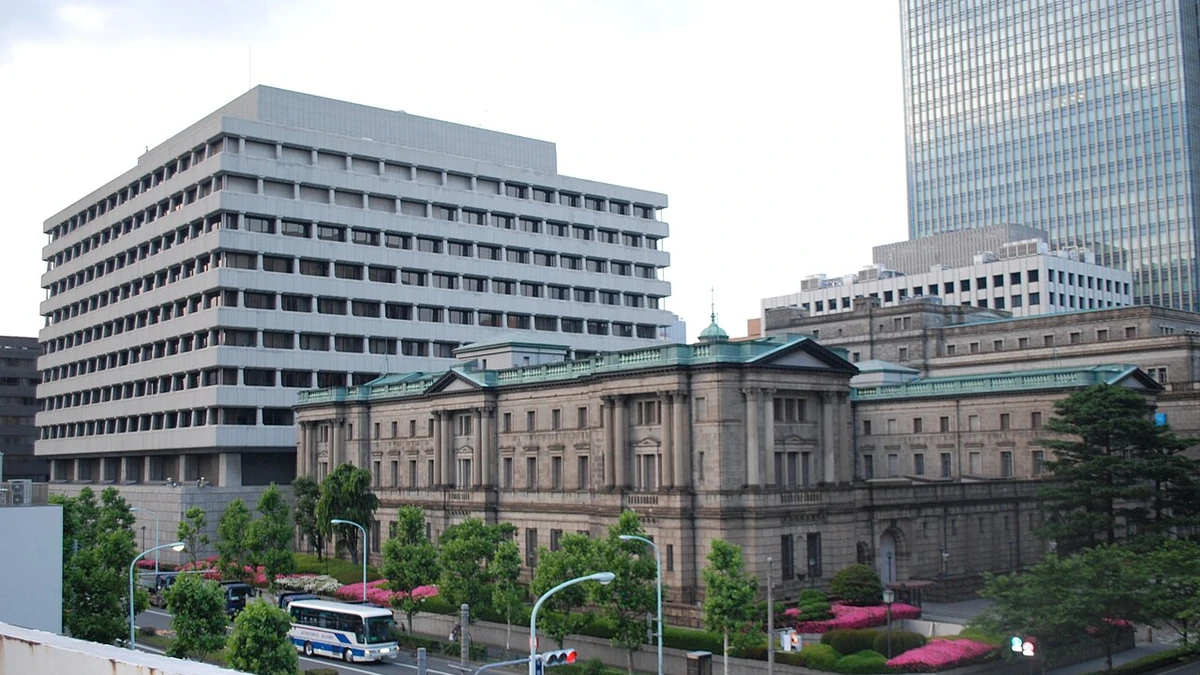
The Bank of Japan’s balance sheet shrank 10.1% from a year earlier to ¥625.0 trillion at the end of September, as its holdings of Japanese government bonds fell 9.5% and lending also declined. The ¥70.2 trillion drop in total assets was larger than the decline recorded a year earlier, underscoring how the central bank’s gradual retreat from large-scale bond buying is now showing up more clearly in the size of its balance sheet.
Japanese government securities stood at ¥504.0 trillion on September 30, down ¥52.7 trillion from the same date in 2025. Loans, excluding those to the Deposit Insurance Corporation, fell by ¥15.4 trillion, or 18.4%, to ¥68.4 trillion. Together, those two changes account for most of the year-over-year reduction in assets.
JGB runoff accounts for most of the decline
In its September 30 accounts, the BOJ said the drop in government securities reflected the reduction in its JGB purchase amount. The figure consists entirely of Japanese government bonds at the reporting date, with Treasury discount bills recorded at zero. The central bank’s end-September numbers are preliminary, with final half-year figures due in November.
The pace of contraction has accelerated. At the end of September 2025, the BOJ reported total assets of ¥695.2 trillion, down 7.7% from a year earlier, while government securities had fallen 4.9% to ¥556.8 trillion. At the end of September 2024, those securities stood at ¥585.5 trillion. On that basis, the BOJ’s JGB holdings have fallen by roughly ¥81.4 trillion, or about 13.9%, over two years.
The decline is a mechanical consequence of buying fewer bonds than in the period of aggressive monetary easing while existing securities continue to mature. BOJ officials have emphasized that JGB holdings can decline even without outright bond sales because maturities reduce the stock when new purchases no longer replace redemptions at the previous pace. The central bank has said its holdings peaked at nearly ¥590 trillion, a level that represented about half of outstanding JGB issuance.
Reserve balances fall as other liabilities shift
The liability side of the balance sheet also changed sharply. Current deposits held at the BOJ, which include reserve balances of financial institutions, fell by ¥85.5 trillion from a year earlier, or 17.0%, to ¥416.6 trillion. The BOJ attributed that decrease to the reduction in JGB purchases and lower lending through programs including its Loan Support Program.
That relationship is central to the balance-sheet runoff. When the BOJ purchases securities, payment for those assets generally adds to balances held by financial institutions at the central bank. As purchases are reduced and lending facilities contract, the corresponding pool of central-bank liabilities can also decline. The BOJ’s own explanation links the fall in current deposits directly to both lower bond purchases and lower program lending.
Not every liability moved down. Payables under repurchase agreements rose by ¥16.8 trillion, or 154.9%, to ¥27.7 trillion. The BOJ said the increase reflected greater sales of JGBs to the government under repurchase agreements. Banknotes outstanding were ¥114.2 trillion, compared with ¥116.6 trillion a year earlier, while government deposits increased to ¥5.2 trillion from ¥2.4 trillion.
On the asset side, the decline in lending was also substantial. The BOJ said the ¥15.4 trillion year-over-year reduction mainly reflected a decrease in loans provided through the Loan Support Program. At September 30, ¥35.7 trillion was outstanding under the Fund-Provisioning Measure to Stimulate Bank Lending, while other pooled-collateral and related funding operations accounted for ¥32.8 trillion.
Balance-sheet runoff continues alongside higher rates
The shrinking balance sheet is occurring at the same time the BOJ is raising short-term interest rates. At its September 18 monetary policy meeting, the Policy Board voted 7-2 to raise the target for the uncollateralized overnight call rate to around 1.25%, effective September 24. That followed a move to around 1.0% in June, adding a higher policy rate to the central bank’s ongoing reduction in bond purchases.
The JGB purchase schedule remains deliberately gradual. Under the plan approved in June, the BOJ set monthly purchases at about ¥2.5 trillion for July through September 2026, about ¥2.3 trillion for October through December, and about ¥2.1 trillion for January through March 2027. From April 2027 onward, it plans to keep monthly purchases at about ¥2 trillion rather than continue cutting the amount each quarter.
The BOJ estimated in June that its JGB holdings would fall to about ¥480 trillion by the end of March 2027, roughly 17% below the level before the reduction program began in June 2024. Assuming monthly purchases remain around ¥2 trillion and the maturity composition is broadly unchanged, the central bank projected holdings of about ¥430 trillion to ¥440 trillion by March 2028 and ¥350 trillion to ¥370 trillion by March 2030. Those figures are estimates rather than fixed balance-sheet targets.
The policy also retains flexibility. The BOJ has said it can increase JGB purchases or use fixed-rate purchase operations if long-term interest rates rise rapidly, and it can amend the pace of purchases at monetary policy meetings if market conditions warrant. That safeguard reflects the central bank’s stated aim of improving market functioning without destabilizing the government-bond market as its role as a buyer becomes smaller.
For the September balance sheet, the immediate picture is already clear: lower JGB holdings are now the dominant force behind a faster year-over-year contraction in total assets, with reduced lending adding to the decline. The next formal checkpoint for these end-September figures will come in November, when the BOJ releases its final half-year financial statements.
More News
Latest News
View all news- Singapore Announces Haze-Related Healthcare Subsidies Starting October 12
- New Zealand’s ACT Party Proposes NZ$12.4 Billion Cut to 2031 Debt Forecast
- French Finance Minister Seeks to Avoid Budget Ordinances Amid Deficit Pressure
- Florida Renters Insurance Rate Cut Takes Effect for American Modern Policies
- Canada’s New Employment Insurance Eligibility Rules Take Effect October 11
