
Bank of France Governor Says Year-End Budget Is Crucial as Borrowing Costs Rise
Emmanuel Moulin said France needs a deficit-cutting 2027 budget by year-end, with a 5% deficit ceiling, as higher yields increase the cost of servicing public debt.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy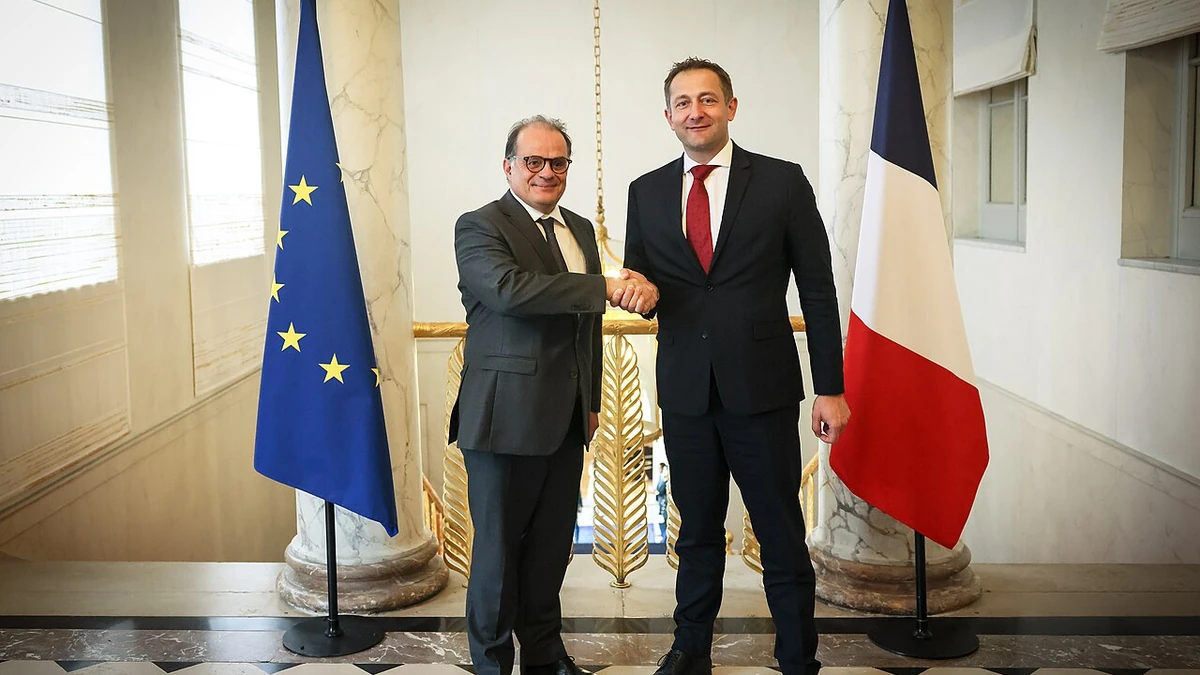
Bank of France Governor Emmanuel Moulin said France needs to secure a deficit-cutting 2027 budget by the end of this year to reassure investors and the public, as higher bond yields add pressure to already strained government finances.
The warning comes as the cost of French borrowing remains elevated. The Banque de France’s daily 10-year constant-maturity Treasury rate, known as TEC10, stood at 4.834% on October 7, up from 4.724% a day earlier. The move is part of a broader rise in global long-term yields, but Moulin said France is feeling additional pressure because its budget deficit is larger than those of many euro-area peers and because investors face uncertainty over whether the 2027 budget will be approved.
In a France Inter interview published by the Banque de France on Wednesday, Moulin described the situation as serious but still manageable. He rejected the idea that France is already facing a financing crisis, noting that Agence France Trésor continues to issue government bonds. His concern is that sustained high yields will gradually raise the interest bill and make future deficit reduction harder.
Moulin calls 5% deficit the upper limit for 2027
The government’s 2027 budget plan aims to reduce the public deficit to 5% of gross domestic product from an estimated 5.4% in 2026. Moulin said that target is realistic, though not especially ambitious, and described 5% as the highest deficit France should accept next year.
The official budget presentation assumes economic growth of 1% in 2027 after a revised 0.5% growth forecast for 2026. It sets out a total fiscal adjustment of €54 billion, including €43 billion of measures in the state budget and social-security financing bills. That makes parliamentary approval more than a procedural milestone: the size and credibility of the adjustment will shape how investors assess the path of French public debt.
Moulin also warned against relying on another stopgap fiscal arrangement in place of a full budget. He said a special law would not provide the savings needed to put the deficit on a downward course. France has constitutional mechanisms that can be used to enact a budget, but his emphasis was on reaching a political outcome that gives the country a credible fiscal plan before year-end.
The governor’s argument is narrower than saying every recent rise in French yields is caused by domestic politics. He said rates have increased across developed markets since the summer amid inflation concerns, expectations for tighter monetary policy, geopolitical risks and heavy bond issuance. France’s fiscal position and uncertainty around the budget vote, however, add a country-specific premium on top of that global backdrop.
Higher yields are feeding into France’s interest bill
The budget arithmetic is becoming more difficult because the cost of servicing debt is rising at the same time the government is trying to reduce the deficit. The Finance Ministry expects interest costs to reach €91.2 billion in 2027, up from €79.2 billion in 2026. Moulin rounded the 2027 figure to about €92 billion and warned that repeated annual increases of roughly €10 billion would absorb savings that could otherwise reduce the deficit or fund other priorities.
Higher market yields do not reprice the entire debt stock at once. France’s negotiable government debt had an average maturity of more than eight years at the end of September, so the effect is transmitted gradually as old securities mature and new debt is issued at prevailing rates. That gradual pass-through still matters when a government has large annual financing needs.
Agence France Trésor’s 2027 financing plan puts the state’s total financing requirement at €339.7 billion, €28 billion above the updated 2026 requirement. It plans €340 billion of medium- and long-term issuance net of buybacks next year, compared with €310 billion in 2026.
The cost of new borrowing has already moved higher. AFT says the weighted average yield on medium- and long-term government securities issued in 2026 was 3.55% through the end of September, up from 3.14% in 2025. At the same time, demand has remained solid: bids for medium- and long-term issues have averaged about 2.5 times the amount offered this year. That supports Moulin’s distinction between higher financing costs and an inability to access the bond market.
France’s debt load leaves little room for a prolonged rate shock
France entered the current bond-market pressure with a large public-debt burden. INSEE reported that Maastricht-defined general government debt reached €3.5955 trillion at the end of the second quarter of 2026, equivalent to 119% of GDP. The ratio was 117.5% at the end of the first quarter, and the debt stock increased by €59.6 billion during the second quarter.
That starting point makes the direction of the deficit especially important. A deficit of 5% of GDP would still be high, but Moulin’s position is that allowing the shortfall to remain above that level would make it harder to convince markets that debt is moving toward a sustainable path. France is also still subject to the European Union’s excessive-deficit procedure, which adds another formal constraint on the government’s fiscal trajectory.
The governor said the consequences of a prolonged rise in sovereign yields would not stay confined to the public accounts. Higher government borrowing costs can feed through to households and companies, including mortgage and business-loan rates, reducing investment and weighing on growth. He said current French mortgage rates remain around 3.30%, but warned they could rise if sovereign financing conditions continue to deteriorate.
Moulin also pushed back on suggestions that the European Central Bank should be expected to solve France’s fiscal problem by intervening in the bond market. He said the ECB’s mandate is centered on price stability and argued that the conditions for an intervention aimed at lowering French borrowing costs are not currently in place. His message was that the immediate response has to come from France’s own fiscal policy.
The next concrete test is the budget process itself. For markets, the year-end deadline will show whether France can turn the proposed 5% deficit target into an enacted plan. For debt management, another milestone follows soon after: AFT is due to publish the detailed medium- and long-term financing program for 2027 in December.
More News
Latest News
View all news- Singapore Announces Haze-Related Healthcare Subsidies Starting October 12
- New Zealand’s ACT Party Proposes NZ$12.4 Billion Cut to 2031 Debt Forecast
- French Finance Minister Seeks to Avoid Budget Ordinances Amid Deficit Pressure
- Florida Renters Insurance Rate Cut Takes Effect for American Modern Policies
- Canada’s New Employment Insurance Eligibility Rules Take Effect October 11
