
BOJ Says All Nine Japanese Regions Are Recovering or Picking Up in October Assessment
The BOJ upgraded Tohoku and Shikoku from July but kept seven other regional views unchanged, with investment and household spending holding up despite uneven conditions.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy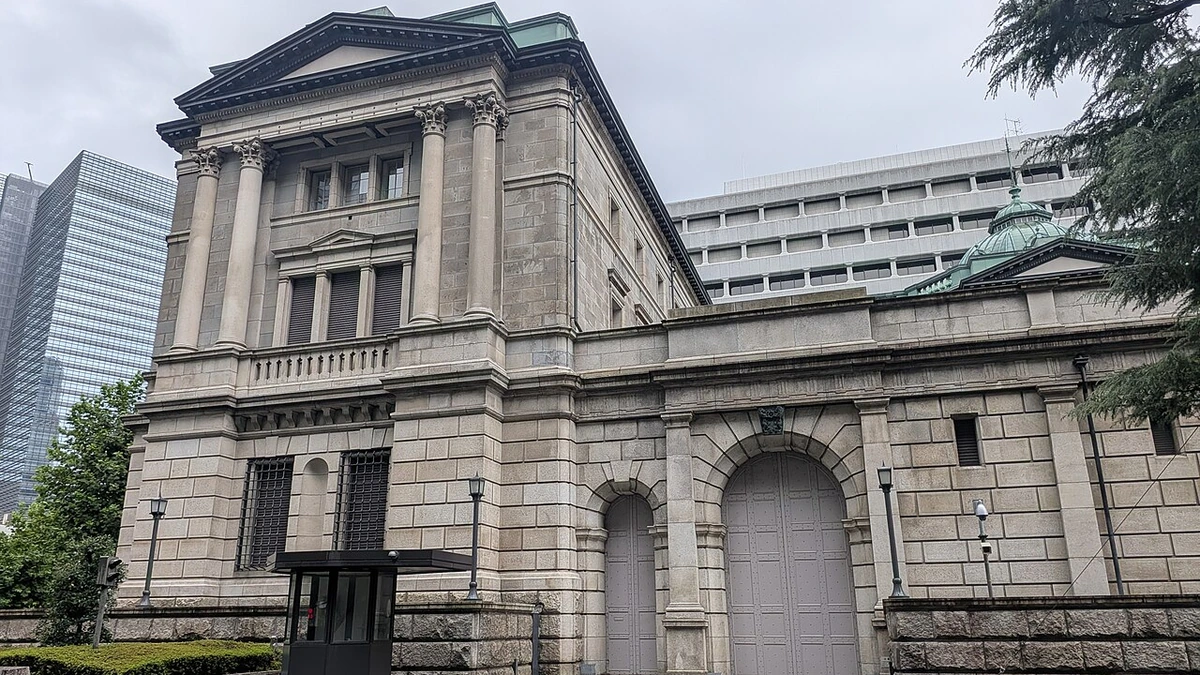
The Bank of Japan said Thursday that all nine of the country’s regions were recovering or picking up in October, lifting its assessments for Tohoku and Shikoku while leaving the other seven unchanged from July. The broadly positive reading comes as the central bank weighs the strength of domestic demand against persistent inflation pressures after raising interest rates in September.
The regional picture is more qualified than the headline might suggest. The BOJ described several economies as recovering moderately but acknowledged pockets of weakness, and its detailed findings show housing investment lagging behind business spending in much of the country. An upgraded assessment also reflects an improvement in the direction or pace of activity, not a measured jump in regional output.
Two regional upgrades, with uneven conditions elsewhere
The BOJ’s October Regional Economic Report upgraded Tohoku from an economy that was ‘picking up’ in July to one that was ‘recovering moderately.’ It also raised Shikoku from ‘picking up moderately’ to ‘picking up.’ In both cases the central bank marked the change as an improvement compared with its previous evaluation.
Neither change should be read as a claim of rapid growth. The BOJ’s comparison system describes whether the pace of improvement or deterioration has changed from one report to the next. Its judgments are qualitative summaries compiled from regional branches for the October 8 meeting of branch general managers, rather than numerical estimates of growth for each area.
The seven unchanged assessments covered Hokkaido, Hokuriku, Kanto-Koshinetsu, Tokai, Kinki, Chugoku and Kyushu-Okinawa. Hokkaido was still picking up moderately, with some weak spots. Hokuriku, Kanto-Koshinetsu, Tokai and Kinki were described as recovering moderately, although the BOJ noted weakness in parts of several of those economies. Chugoku remained on a moderate recovery trend.
The qualifications are particularly important for two regions. In Kanto-Koshinetsu, which includes Tokyo, the report retained a reference to weakness partly related to developments in the Middle East. For Kyushu-Okinawa, the BOJ maintained its overall assessment of moderate recovery but specifically pointed to the effects of the 2026 Kumamoto Earthquake as a source of weakness in some areas. That addition to the wording did not translate into a downgrade in the comparison table.
Taken together, the region-by-region judgments describe an economy that has continued to expand across different parts of Japan without eliminating local or industry-specific strains. The upgrades in Tohoku and Shikoku provide the main evidence of improvement since July; the unchanged ratings elsewhere suggest continuity rather than a fresh nationwide acceleration.
Business investment and wages support activity as housing lags
The more detailed demand assessments help explain why the BOJ could maintain a constructive view across all nine regions. Business fixed investment was increasing in eight regions, while Kyushu-Okinawa reported that it remained at a high level. Tohoku described an increasing trend, and the large Kanto-Koshinetsu and Tokai economies also reported higher capital spending. Those descriptions point to ongoing corporate investment even where other components of demand are less consistent.
Private consumption was generally resilient, but the BOJ did not describe a uniform spending boom. Hokkaido reported firm household demand despite the effects of higher prices. Hokuriku said consumption was picking up even as inflation weighed on purchases. In Kanto-Koshinetsu, spending was increasing gradually against a backdrop of improving employment and incomes, while Kinki reported a moderate rise with some weakness. Shikoku’s consumption was picking up, and Kyushu-Okinawa continued to describe it as firm despite price pressures.
Employment and income assessments offer an important link between those spending readings. Each region reported improvement in labor-market or income conditions, though the strength of that improvement varied. This does not mean higher pay has fully offset rising living costs for every household. It does help explain why the overall evaluations remain positive despite the repeated references to inflation in the consumer-spending findings.
Housing investment is a clearer weak point. The report characterized residential construction as weak in Hokkaido, Kanto-Koshinetsu, Tokai, Chugoku, Shikoku and Kyushu-Okinawa. Tohoku and Hokuriku said it had stopped declining, while Kinki reported activity moving broadly sideways. That is a different picture from the business-investment assessments, which showed increases or high levels throughout the country.
Manufacturing also varied across regions. Production in Hokkaido was broadly flat, with some softness, whereas Tohoku reported a moderate recovery and Tokai described an increasing trend. Kanto-Koshinetsu said production had turned to a modest increase. Kyushu-Okinawa reported a gradual rise, but with weakness in some areas linked to the Kumamoto earthquake. The aggregate regional verdict therefore should not be interpreted as a statement that factories were uniformly gaining momentum.
The distinction between investment, consumption, housing and production matters for judging the durability of the recovery. Corporate capital spending and improving employment conditions offer support, but the weaker housing readings and uneven factory activity limit how much can be inferred from nine positive headline assessments alone.
Regional findings feed into an October policy decision
The economic backdrop has changed since the July regional survey. On September 18, the BOJ’s Policy Board voted 7-2 to raise the target for the uncollateralized overnight call rate to around 1.25%, effective September 24. The central bank said underlying inflation was approaching its 2% objective and judged that financial conditions would remain accommodative after the increase.
In that policy decision, the BOJ also described Japan’s economy as recovering moderately, despite some weakness partly associated with the situation in the Middle East. It cited increasing global demand for artificial-intelligence-related products as one source of support for exports and industrial production. At the same time, it pointed to high crude-oil prices, a weaker yen and rising business costs as factors putting upward pressure on prices.
The relationship between income growth and household spending is especially relevant to the bank’s policy judgment. Stronger wages can help consumers absorb price increases and sustain demand, but higher costs can also erode purchasing power. The October regional report shows both sides of that picture: continued improvement in employment and income, alongside consumer assessments that still mention inflation and areas of weakness.
The latest regional report is evidence about economic conditions, not a signal that a particular interest-rate move has already been decided. The September policy statement said future adjustments would depend on activity, prices, financial conditions and risks to the outlook, including developments in the Middle East, AI-related demand and foreign exchange markets. The BOJ’s next scheduled policy meeting is October 29-30, when those considerations can be evaluated alongside the regional findings.
More News
Latest News
View all news- Singapore Announces Haze-Related Healthcare Subsidies Starting October 12
- New Zealand’s ACT Party Proposes NZ$12.4 Billion Cut to 2031 Debt Forecast
- French Finance Minister Seeks to Avoid Budget Ordinances Amid Deficit Pressure
- Florida Renters Insurance Rate Cut Takes Effect for American Modern Policies
- Canada’s New Employment Insurance Eligibility Rules Take Effect October 11
