
Texas Extends Newborn Health Insurance Coverage Window to 61 Days Under New Rules
Texas has adopted rules implementing SB 896, giving families 60 days to notify a plan and pay any required added premium while extending initial newborn coverage through the 61st day after birth.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy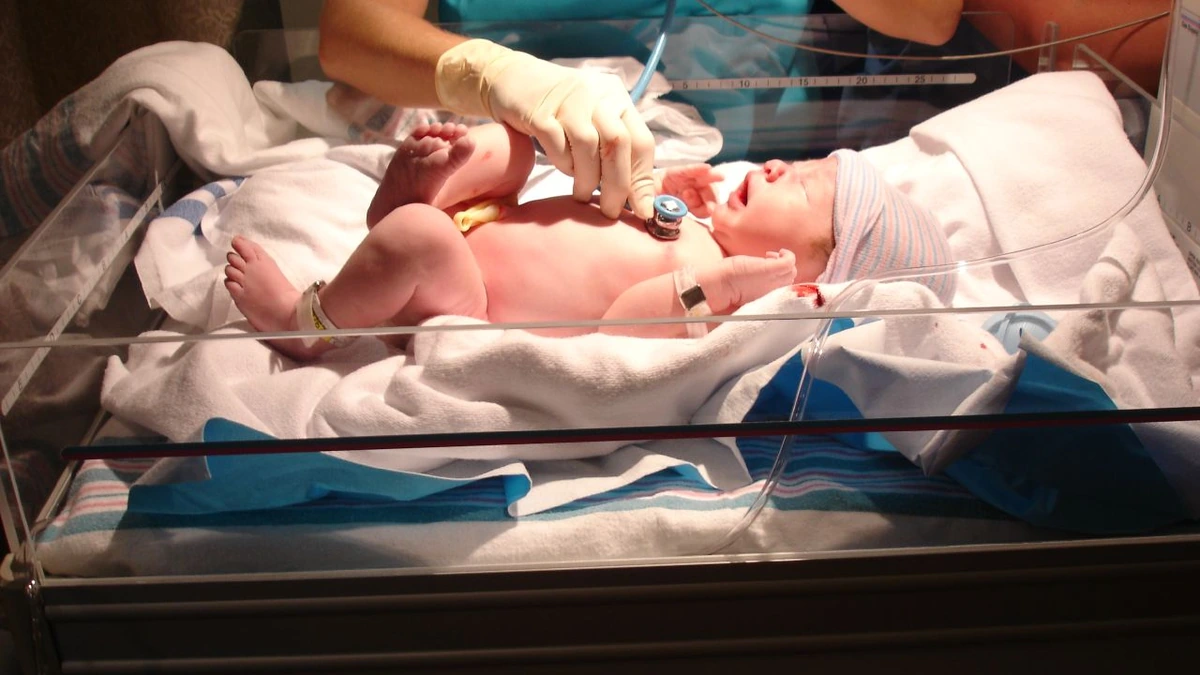
Texas has finalized new insurance rules that give families more time to keep newborn children covered under certain state-regulated health plans. The Texas Department of Insurance adopted rule changes that extend the initial newborn coverage period from the 32nd day after birth to the 61st day after birth, while also extending the deadline to notify a health plan and pay any required additional premium from 31 days to 60 days.
The change implements Senate Bill 896, which the Texas Legislature passed in 2025. For parents, the practical effect is an extra month to complete enrollment steps for a newborn under applicable coverage. For insurers and employers, the update changes plan administration, evidence-of-coverage language, and timing requirements across several parts of the state’s insurance rulebook.
The rule does not mean every newborn automatically stays covered indefinitely without action from a family. Under the Texas framework, the longer initial coverage period applies first, but continuing coverage can still depend on whether the child is eligible under the plan and whether the enrollee gives notice of the birth and pays any added premium by the 60th day. That distinction matters because the headline number in the rule is 61 days, while the key administrative deadline for many families is day 60.
New rules lengthen the initial coverage window
The most direct change is simple: Texas-regulated plans covered by these provisions can no longer cut off initial newborn coverage after the first 31 days. In the adopted rules published in the Texas Register, the Department of Insurance said amendments to Chapter 26 extend the end date of the mandatory coverage period for newborn children under small and large employer health plans from the 32nd day after birth to the 61st day after birth.
The same Texas Register adoption also shows that TDI updated HMO rules and rules for individual and group accident and sickness policies. In Chapter 3, Section 3.3403 now bars covered policies from excluding or limiting initial coverage of a newborn before the 61st day after birth. The rule also says initial coverage must continue for at least 60 days, while allowing the insurer to require notice of birth and any additional premium before coverage continues beyond that initial period.
That structure helps explain why the story is best understood as an extension of the initial coverage and enrollment window, not as a new open-ended benefit. The legal change widens the period during which a newborn is protected under applicable coverage terms, but it does not erase enrollment mechanics. Insurers may still require the family or policyholder to complete the steps needed to keep coverage in force after the initial period expires.
TDI’s HMO adoption order uses similar language. It says the amendments to Section 11.506 expand required coverage for newborn children from 31 days to 60 days following birth and extend the deadline to notify the HMO. Taken together, the Chapter 3, Chapter 11, and Chapter 26 changes bring multiple state insurance rules into line with the statute the Legislature amended through SB 896.
What families, employers, and plans need to know
For families, the operational takeaway is that the old 31-day clock has been replaced by a 60-day one under the affected Texas rules. A newborn may receive the longer initial coverage protection, but the parent or policyholder should still notify the insurer, HMO, or employer plan administrator as soon as possible rather than waiting until the end of the period. Missing the notice or premium deadline could mean the initial coverage ends on the 61st day after birth.
For employer-sponsored coverage, the Chapter 26 amendments are particularly important because they address both small employer and large employer health benefit plans subject to Insurance Code Chapter 1501. The adopted text states that coverage of a newborn child ends on the 61st day after birth unless children are eligible for coverage under the plan and the issuer receives notice of the birth and any required additional premium by the 60th day. That gives families more time than before, but it preserves the plan’s right to require those steps.
The broader Chapter 3 amendments matter as well because they reach individual and group accident and sickness policies that provide maternity benefits or additional newborn-child coverage. In other words, this is not just a technical employer-plan adjustment buried in one section of the code. Texas regulators revised multiple rule sets so that insurers, HMOs, and employer-plan issuers use the longer newborn coverage timeline consistently where the statute applies.
Employers and plan administrators will also need to ensure their coverage materials match the new timing. Evidence-of-coverage documents, enrollment instructions, internal claims procedures, and premium collection processes all need to reflect that the initial newborn period now runs through day 60 and that termination for failure to complete enrollment steps would occur on day 61, not day 32. That is a compliance issue for carriers, but it also affects the practical experience of new parents who rely on written plan instructions in the weeks after a birth.
Texas says the change aligns state rules with a longer enrollment period
The policy rationale came through clearly in a Texas Department of Insurance bulletin summarizing 2025 legislation. TDI said SB 896 extends the time to enroll a newborn child in a health plan that provides maternity benefits or accident and health coverage for additional newborn children from 31 days to 60 days and aligns that period with the special enrollment window available in the individual market under federal law.
The timeline is also important. SB 896 took effect on Sept. 1, 2025, and TDI said it applies to policies issued or renewed after Jan. 1, 2026. The newly adopted rules, which the Texas Register says were filed on Sept. 21, 2026, became effective on Oct. 11, 2026. In practice, that means the statutory policy choice came first, while the 2026 rulemaking completed the agency’s implementation work across the detailed insurance regulations that carriers and HMOs must follow.
For consumers, the change addresses a real-life paperwork problem. The first month after a child’s birth can involve hospital care, follow-up appointments, recovery for the mother, and multiple administrative tasks. Extending the enrollment and notice period reduces the risk that a family loses coverage simply because it could not complete health-plan paperwork inside the old 31-day window. At the same time, the Texas rules stop short of creating automatic permanent enrollment, which is why the notice and premium deadline remains central to understanding the policy.
The updated rules leave in place other important newborn protections. Texas law continues to prohibit plans from excluding coverage for congenital defects of a newborn child, and the statute also addresses coverage for the administration of required newborn screening tests. What changed here is the timing framework surrounding initial coverage and enrollment, not the broader concept that newborns must receive meaningful early-life coverage under the affected plans.
With the rules now in effect, insurers, HMOs, employers, and families in affected plans have clearer guidance: the initial newborn coverage period runs to the 61st day after birth, and any required notice of birth and added premium generally must reach the plan by the 60th day.
More News
Latest News
View all news- New Zealand’s ACT Party Proposes NZ$12.4 Billion Cut to 2031 Debt Forecast
- French Finance Minister Seeks to Avoid Budget Ordinances Amid Deficit Pressure
- Florida Renters Insurance Rate Cut Takes Effect for American Modern Policies
- Canada’s New Employment Insurance Eligibility Rules Take Effect October 11
- Australia Announces A$4.7 Million in Emergency Relief and Debt Counselling Funding
