
Bank of Italy Presents Assessment of 2026 Public Finance Plan to Parliament
Italy’s central bank raised questions about the country’s path out of EU deficit oversight, as the government forecasts higher borrowing in 2027 and 2028 for defense and energy security.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy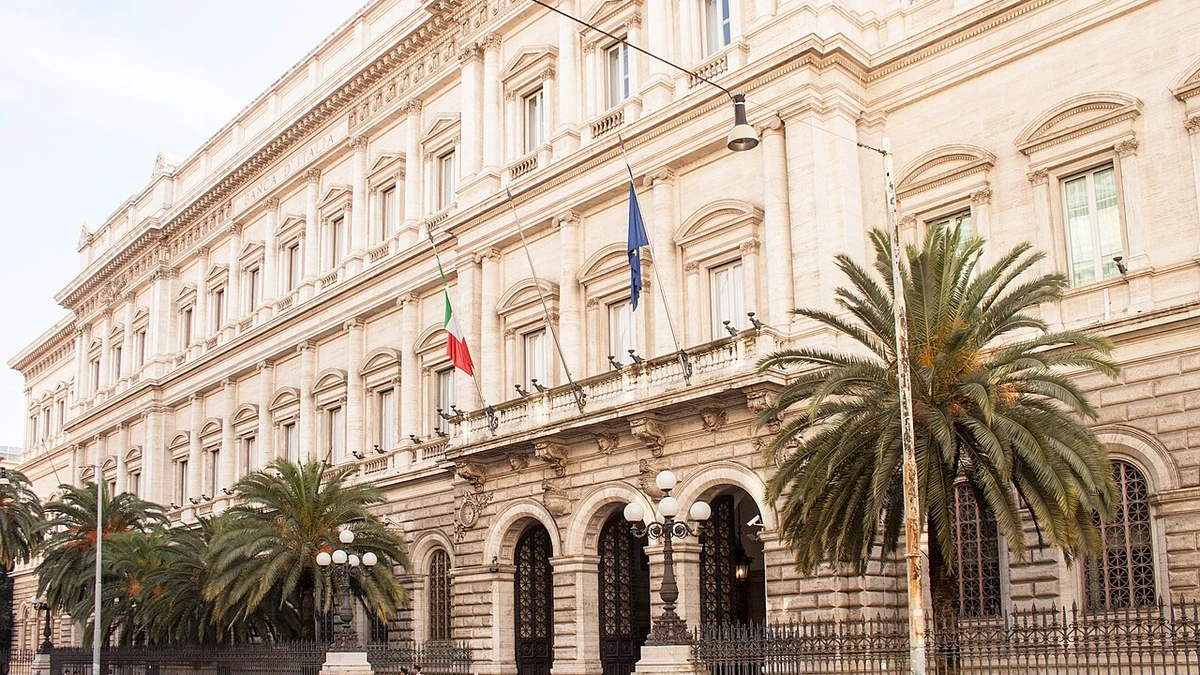
The Bank of Italy presented its assessment of the government’s 2026 public-finance plan to Parliament on Monday, with particular attention to a deficit path that could complicate Italy’s efforts to leave the European Union’s excessive-deficit procedure. Rome expects its budget shortfall to fall below 3% of gross domestic product this year, only to rise above that level in 2027 and 2028 as it seeks additional room for defense and energy-security spending.
Andrea Brandolini, head of the central bank’s Economics and Statistics Department, spoke to the joint budget committees of the Chamber of Deputies and Senate on October 12. The official parliamentary hearing examined the government’s Documento programmatico di finanza pubblica 2026, which sets out the fiscal assumptions and policy direction for the 2027–2029 budget period. The plan was approved by the cabinet on October 2 and subsequently presented to Parliament.
Brandolini described an Italian economy that had held up better than expected in the first part of 2026, according to remarks reported by the Italian news agency ANSA. Growth is expected to continue, though higher energy prices and borrowing costs are likely to keep it subdued. He also identified Middle East tensions and instability in global financial markets as risks to the economic outlook. The question for fiscal policy is whether that modest expansion will generate enough revenue to support the government’s borrowing targets.
A 2026 deficit improvement gives way to higher borrowing
For 2026, the government projects a deficit of 2.9% of GDP, compared with the 3.1% recorded in 2025 by national statistics agency ISTAT. The planned borrowing requirement then rises to 3.4% of GDP in 2027 and 3.2% in 2028 before falling to 2.3% in 2029. These figures are forecasts under the government’s policy scenario, not realized outcomes, and they reflect spending choices that still have to be carried through the budget process.
The expected increase in 2027 and 2028 is tied to proposed use of the EU’s national escape clause for defense and energy security. Italy is seeking flexibility worth as much as roughly €29 billion across those two years, equivalent to about 0.6 percentage point of GDP annually. Excluding that flexibility, the plan projects a deficit of 2.8% in 2027 and 2.6% in 2028. The distinction between the headline figures and the adjusted path is central to the dispute over how Italy’s progress should be judged under EU rules.
Economic growth is expected to provide some help but not a large cushion. The government forecasts GDP growth of 1.0% in 2026, followed by 0.8% in 2027, 0.9% in 2028 and 0.8% in 2029. ISTAT’s latest quarterly accounts showed output rising 0.3% in the first quarter of 2026 and 0.2% in the second. Those readings support Brandolini’s description of an economy still expanding, without indicating that the coming years will produce a rapid improvement in the tax base.
Italy’s independent Parliamentary Budget Office, known as the UPB, has validated the government’s macroeconomic forecasts for 2026 and 2027. It considers the later projections somewhat more optimistic: its own growth estimates are 0.7% for 2028 and 0.6% for 2029, compared with the government’s 0.9% and 0.8%. Such differences may look small, but they matter for a country whose fiscal projections depend on steady growth and a large stock of public debt.
Why EU deficit oversight is still an unresolved issue
The Bank of Italy’s most immediate concern is the way the proposed spending flexibility interacts with a procedure Italy is already in. According to Reuters’ reporting of the hearing, the central bank cautioned that a national escape clause can provide protection against some breaches of EU spending rules without necessarily giving a country already subject to excessive-deficit oversight an automatic route out. That is a narrower point than saying the higher deficits make an exit impossible.
Italy entered the EU’s excessive-deficit procedure in 2024. The European Commission still lists the procedure as ongoing, following a Council recommendation in January 2025 to correct the excessive deficit. Bringing the deficit below 3% in 2026 would be an important step, but ending the procedure also requires a judgment that the improvement is durable. The forecast rebound in the following two years raises the question of how the European authorities will treat spending covered by the requested escape clause.
There is little room for a disappointment in this year’s budget numbers. A 2.9% forecast leaves only one-tenth of a percentage point between the projected deficit and the EU’s 3% reference value. Italy’s 2025 deficit was confirmed at 3.1%, so the country did not secure an earlier exit based on last year’s accounts. The central bank urged careful monitoring of the remainder of 2026, Reuters reported, given how easily a modest departure from the forecast could affect the target.
The UPB’s October 12 assessment adds a separate, independent perspective. It found the government’s macroeconomic forecasts broadly acceptable but warned that, excluding the proposed escape-clause spending, the 2027 budget would have essentially no spare fiscal room for new measures. Additional policies would generally require offsetting spending cuts or higher revenue. The office also said the government needs to explain how increases in defense and energy-related commitments will be financed after the temporary flexibility ends.
Debt and interest costs put the forecasts under pressure
The size of Italy’s existing debt makes the debate over relatively small deficit changes consequential. The government’s plan projects debt at 138.1% of GDP in 2026, rising to 138.5% in 2027 before easing to 137.9% in 2028 and 136.6% in 2029. The scheduled decline assumes that primary-budget improvements and economic growth will eventually outweigh the effect of interest charges and new borrowing.
Higher financing costs could alter that trajectory. The UPB expects government interest spending to reach about 4.6% of GDP in 2028 and 2029. In a sensitivity exercise using less favorable market-rate assumptions, it calculated that interest costs in 2029 could exceed the government’s projections by approximately €4.5 billion. Under that scenario, debt could stand at about 138.4% of GDP in 2029, rather than the government’s 136.6% forecast. Those are conditional stress estimates, not the budget office’s base-case prediction.
Energy prices add another layer of risk. Higher costs can weaken household purchasing power and corporate demand, making the tax and growth assumptions harder to meet. Brandolini’s account of a resilient economy was therefore not an assertion that the risks had passed. The central bank expects expansion to continue, but its assessment points to a country exposed to imported energy shocks and the cost of refinancing public obligations.
The spending decisions will become more concrete as the 2027–2029 budget legislation is prepared. Parliamentary scrutiny of the fiscal plan is continuing, while the European institutions must evaluate the proposed treatment of defense and energy expenditure and any implications for excessive-deficit oversight. Those decisions, together with the final 2026 deficit outcome, will determine whether Italy’s prospective return below the 3% line marks lasting progress or only a temporary dip.
More News
Latest News
View all news- JPMorgan Reports $15.3 Billion Third-Quarter Profit as Revenue Hits $50.2 Billion
- Johnson & Johnson Raises 2026 Sales Outlook After $25.4 Billion Third-Quarter Revenue
- IMF Raises Global Growth Forecast to 3.1% as AI Investment Supports the U.S. Outlook
- Goldman Sachs Posts $5.29 Billion Q3 Profit and $17.01 Earnings Per Share
- FTC Seeks Contempt Sanctions Against Martin Shkreli Over Alleged Biotech Stock Trading
