
CFTC Opens Public Comment on Proposed Framework for Retail Crypto Asset Transactions
The CFTC is considering tailored oversight for certain leveraged and financed retail crypto trades, with public comments due December 14.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy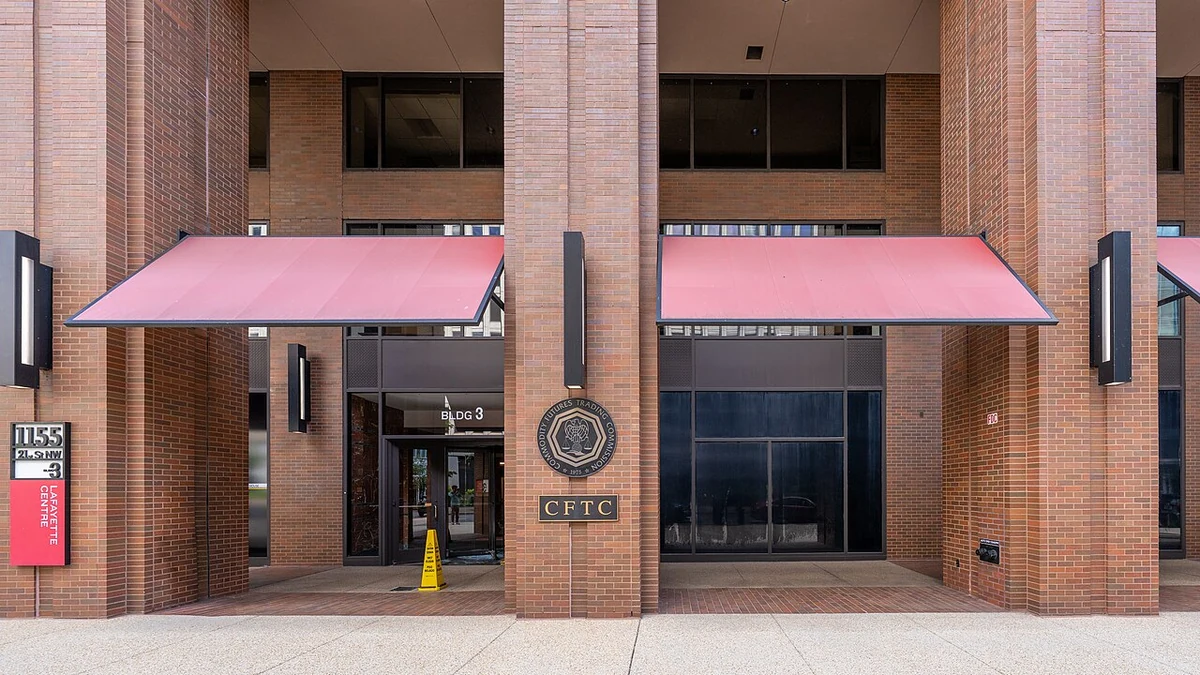
The Commodity Futures Trading Commission is asking the public how it should regulate certain retail cryptocurrency trades, laying out a possible federal framework for digital-asset platforms that offer leverage, margin or financing. The initiative could give those businesses a tailored route into CFTC-supervised markets, but it does not establish new trading rules today.
The agency announced its advance notice of proposed rulemaking on October 5, and the document appeared in the Federal Register on October 13. Comments are due December 14, 2026. The consultation centers on a specific provision of the Commodity Exchange Act rather than an across-the-board overhaul of ordinary cryptocurrency purchases.
In its October 5 announcement, the CFTC said it wants to address abusive practices, clarify how existing law applies to crypto assets and explore a registration category designed for these markets. The commission will use the responses to decide whether and how to advance a formal rulemaking. That distinction matters: the notice describes preliminary interpretations and possible requirements, not obligations that exchanges must now adopt.
Which retail crypto trades would be covered?
The legal starting point is Section 2(c)(2)(D) of the Commodity Exchange Act. It generally reaches certain commodity trades offered to retail customers on a leveraged or margined basis, or financed by the seller, counterparty or a related party, subject to statutory exceptions. The provision was designed to prevent products functioning like futures contracts from escaping federal oversight merely because they were structured as something else.
An important complication is the word “offered.” The statute can apply when leverage or financing is offered even if the customer does not take it. The CFTC is considering how to interpret that feature for digital-asset exchanges, including situations in which a customer pays in full but the asset remains recorded on the platform’s internal books. This is one reason the inquiry reaches beyond the narrower question of how much traders borrow.
Actual delivery is another central issue. The law contains an exception for certain sales that result in actual delivery within 28 days, or another period established under the statute. The commission is examining what delivery means when a digital asset sits in an exchange account rather than a wallet the customer can independently control. A change in an exchange’s account records is not necessarily the same as transferring meaningful possession of the asset.
Those distinctions could influence where a trade is conducted and which safeguards apply before delivery occurs. The notice also asks about onchain systems, including whether a blockchain transfer can give the purchaser sufficient possession and control even when a financing-related security interest remains. The commission has not made a blanket determination that all such protocols qualify for an exception.
It would therefore be misleading to treat the consultation as a plan to bring every crypto spot trade onto a futures exchange. Its focus is the subset of retail commodity activity addressed by the cited law, including questions about statutory exceptions and the point at which a customer’s purchased asset is actually delivered.
A possible registration route for crypto trading platforms
A major feature of the notice is a proposed category called a crypto asset market, or CAM. The CFTC is considering making it a tailored subcategory of designated contract market registration. Platforms listing only the covered retail crypto trades could potentially use that route, while firms already operating as traditional designated contract markets could continue under their existing form of registration.
The distinction reflects how many cryptocurrency platforms work. Conventional futures markets list contracts whose value is tied to an underlying commodity. The retail crypto arrangements under discussion may instead involve the purchase of the asset itself alongside a separate financing agreement. Applying every conventional futures-market requirement without adjustment could leave some of those arrangements poorly matched to the existing rulebook, according to the commission’s preliminary assessment.
The agency is also seeking views on the roles of futures commission merchants, which handle customer-facing brokerage functions and customer property, and derivatives clearing organizations, which manage clearing and settlement obligations. Its outline contemplates adapting those requirements for covered crypto activity rather than simply copying the full conventional futures structure.
Some platforms currently bring trading, custody and settlement services under common ownership or within closely related entities. The notice explores whether a CAM could also hold other CFTC registrations or work through affiliated intermediaries, subject to safeguards. That raises a practical question about separating customer protection and risk management responsibilities when several market functions operate within the same business group.
Asset listing standards are also under consideration. The CFTC is asking whether exchanges should assess matters such as circulating supply, governance arrangements, the availability of source code and the resilience of a blockchain when evaluating susceptibility to manipulation. These would be trading-venue safeguards, not a general endorsement by the government of a token’s investment merits.
Customer protections and the December comment deadline
For retail traders, the most immediate questions concern how borrowed positions and customer holdings would be protected. The commission is asking what a registered crypto market’s rulebook should disclose about financing charges, collateral, margin requirements and liquidation procedures. These details matter because a sharp price movement can trigger the forced sale of a leveraged position, potentially leaving a customer with losses greater than anticipated.
The consultation goes further into custody. It seeks feedback on segregation of customer assets, the reliability of proof-of-reserves arrangements and whether intermediaries should be permitted to reuse customer crypto assets as collateral. The commission also raises questions about how customer property would be treated if a futures commission merchant became insolvent. None of those questions has been resolved by the publication of this notice.
The CFTC has framed the exercise partly as an attempt to put preventive supervision ahead of relying on enforcement after fraud occurs. It points to the failure of FTX when explaining shortcomings it sees in an enforcement-led approach. The notice does not, however, demonstrate that any one proposed market structure would have prevented that collapse; the design and effectiveness of future safeguards remain matters for examination.
The Federal Register notice, published October 13 under RIN 3038-AF80, invites responses from exchanges, financial institutions, technology providers, industry groups, individual investors and other interested parties. Written comments must be received by December 14. Submissions can be made through Regulations.gov, or by the mail and delivery methods described in the official notice.
The commission warns that comments are generally made public, including information a sender may regard as personal or confidential. Anyone seeking confidential treatment is directed to follow the agency’s specified procedures rather than assume ordinary submissions will be redacted. Once the comment period closes, the CFTC can review the record and decide whether to publish an actual proposed rule, revise its approach or take another step; no final adoption date has been announced.
More from Investing
Latest News
View all news- Fed’s Waller Says Higher Treasury Yields Reflect Strong Growth More Than Inflation Expectations
- U.S. Small-Business Optimism Falls to 97.9 as Uncertainty and Hiring Concerns Persist
- U.S. Existing-Home Sales Rise 1.5% in September Despite High Mortgage Rates
- IMF Raises Global Growth Forecast to 3.1% as AI Investment Supports the U.S. Outlook
- FTC Seeks Contempt Sanctions Against Martin Shkreli Over Alleged Biotech Stock Trading
