
Goldman Sachs Posts $5.29 Billion Q3 Profit and $17.01 Earnings Per Share
Goldman Sachs reported third-quarter net earnings of $5.29 billion and diluted EPS of $17.01, with trading and investment banking helping push revenue to $18.68 billion.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy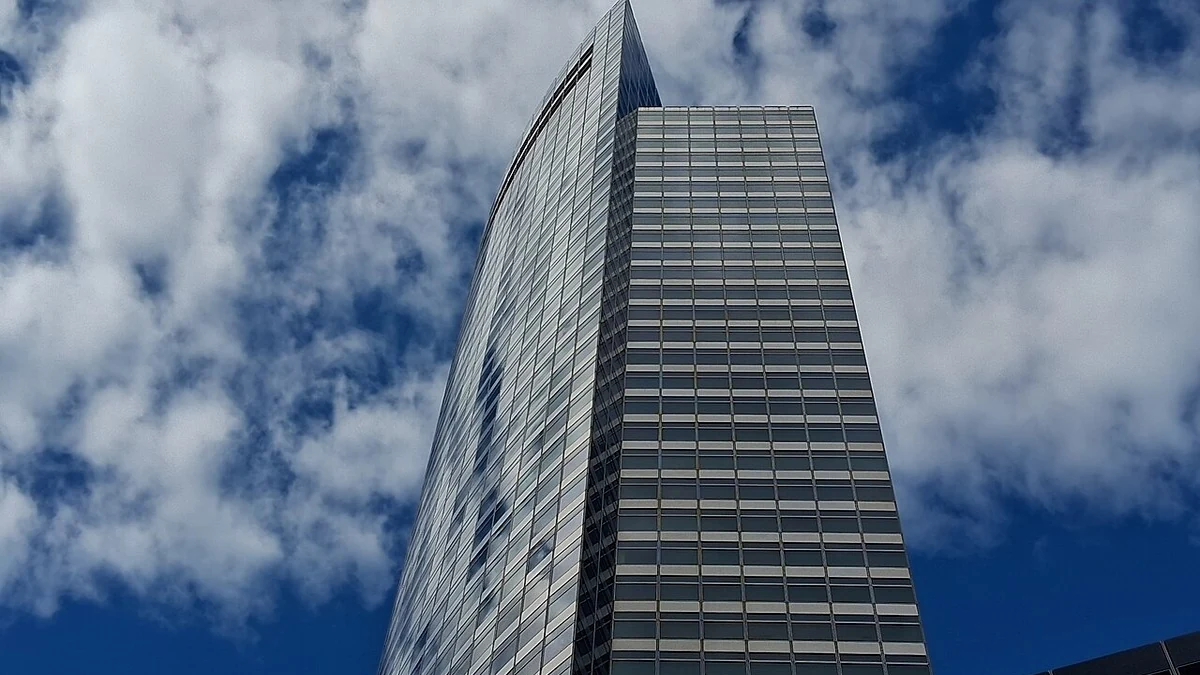
Goldman Sachs reported third-quarter net earnings of $5.29 billion on Tuesday, with revenue of $18.68 billion and diluted earnings per share of $17.01 as client activity stayed strong across the firm’s trading and advisory businesses. The results gave the bank another quarter of high absolute profitability even though earnings came in below the unusually strong second quarter.
Annualized return on average common shareholders’ equity was 18.7% for the three months ended Sept. 30, according to the company’s results. Book value per common share rose to $372.64, up 1.4% during the quarter and 4.2% so far this year. For the first nine months of 2026, Goldman Sachs said net earnings totaled $17.55 billion on revenue of $56.24 billion, with diluted EPS of $55.56 and annualized ROE of 20.7%.
In its official earnings release, Goldman Sachs said the quarter produced its second-highest quarterly net revenue on record and record year-to-date net revenue. Chairman and Chief Executive Officer David Solomon said clients continued to rely on the firm’s advice, execution and financing capabilities despite what he described as a complicated operating environment.
Trading and dealmaking remained central to the quarter
The broad picture from Goldman’s release points to a quarter driven by the businesses that tend to benefit when corporate clients, institutional investors and asset managers stay active. The bank highlighted its second-highest revenue in Global Banking & Markets, record revenue in Advisory and its second-highest revenue in Equities and in FICC financing. Goldman also said it ranked first in announced and completed mergers and acquisitions and in equity and equity-related offerings, second in leveraged lending and third in high-yield debt during the period.
That set of disclosures helps explain why profit held up at a high level even though the quarter did not match the previous one. In the second quarter, Goldman posted net earnings of $6.63 billion and diluted EPS of $20.98. The third-quarter figures therefore represented a sequential slowdown, but they still pointed to a business mix that remained highly favorable relative to historical levels. Compared with the same quarter a year earlier, the improvement was clearer: Goldman’s third-quarter 2025 earnings were $4.10 billion, with diluted EPS of $12.25 and revenue of $15.18 billion.
The company’s presentation also noted that charitable contributions reduced diluted EPS by about $1.00 and annualized ROE by about 1.1 percentage points in the latest quarter. That means headline profitability was achieved even with a measurable offset from those contributions. For investors trying to judge the firm’s underlying earnings power, that detail provides some added context around the quarter’s reported return metrics.
Goldman did not frame the quarter as a simple story of one desk carrying the rest of the franchise. Instead, the official materials emphasized broad client demand across financing, market activity and corporate transactions. That is consistent with the way the bank has positioned itself in recent years, leaning on the scale of its institutional franchise while also building fee-based businesses that can support earnings through changing market conditions.
Asset and wealth fees added another layer of support
The quarter was not only about trading and investment banking. Goldman also reported record management and other fees in Asset & Wealth Management and record assets under supervision of $4.10 trillion. It said the firm logged its 35th consecutive quarter of long-term fee-based net inflows, a sign that the asset-gathering side of the business continued to expand even while market conditions remained uneven.
That matters because the firm’s fee businesses can make the overall earnings profile less dependent on trading volatility. Advisory fees, underwriting revenue and market activity can be highly sensitive to swings in confidence, issuance windows and risk appetite. By contrast, management fees tied to supervised assets usually move more gradually and can provide steadier support when client balances stay elevated. Goldman’s release suggested both engines were contributing at the same time in the third quarter.
The bank also used the update to point to strategic activity beyond quarterly earnings. During the quarter, Goldman announced agreements to acquire NEOS Investments and LCN Capital Partners. Those deals were not the main driver of the reported quarter, but they do show where management still sees room to add capabilities and scale, especially in parts of the asset and wealth platform where recurring fee income can deepen client relationships and diversify the revenue base.
Another capital measure moved in the right direction as well. Book value per common share reached $372.64 at quarter-end, up from $367.67 at the end of the second quarter and $353.79 at the end of the third quarter of 2025. That rise will matter to investors who assess large banks not only on quarterly earnings but also on how efficiently they convert those earnings into shareholder value over time.
What the SEC filing and next quarter comparisons may show
Goldman furnished the results to the market in an October 13 filing with the Securities and Exchange Commission, which included the earnings release and accompanying presentation as exhibits to an 8-K. The filing formalized the figures investors were already focused on from the company’s announcement and provides the source record for the quarter’s reported profit, revenue and return metrics.
For shareholders, the most immediate question after a strong quarter is whether this level of profitability can be sustained. Goldman’s own language was confident but measured. The bank pointed to a complicated operating environment, yet it also said it remained well positioned because of the breadth of its franchises and the depth of its client relationships. That leaves investors balancing two truths at once: earnings remain strong, but they are still tied to conditions in capital markets and client activity that can shift quickly.
The comparison base heading into the final quarter of the year is also important. Goldman’s second quarter was exceptionally strong, so a sequential decline in third-quarter profit does not necessarily indicate a weakening franchise. The year-over-year comparison was more favorable, with earnings, revenue and return on equity all materially above the prior-year third quarter. If advisory pipelines, financing demand and fee inflows remain healthy, the firm enters the last stretch of 2026 with substantial momentum.
Goldman is scheduled to discuss the results on a conference call Tuesday morning. That call may offer more detail on client activity, expense trends, the acquisitions announced during the quarter and management’s view of the business environment heading into year-end.
More from Investing
Latest News
View all news- Fed’s Waller Says Higher Treasury Yields Reflect Strong Growth More Than Inflation Expectations
- U.S. Small-Business Optimism Falls to 97.9 as Uncertainty and Hiring Concerns Persist
- U.S. Existing-Home Sales Rise 1.5% in September Despite High Mortgage Rates
- IMF Raises Global Growth Forecast to 3.1% as AI Investment Supports the U.S. Outlook
- FTC Seeks Contempt Sanctions Against Martin Shkreli Over Alleged Biotech Stock Trading
