
U.S. Existing-Home Sales Rise 1.5% in September Despite High Mortgage Rates
The modest rebound lifted sales to a 3.99 million annual pace, but activity still trailed last year as elevated borrowing costs weighed on buyers.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy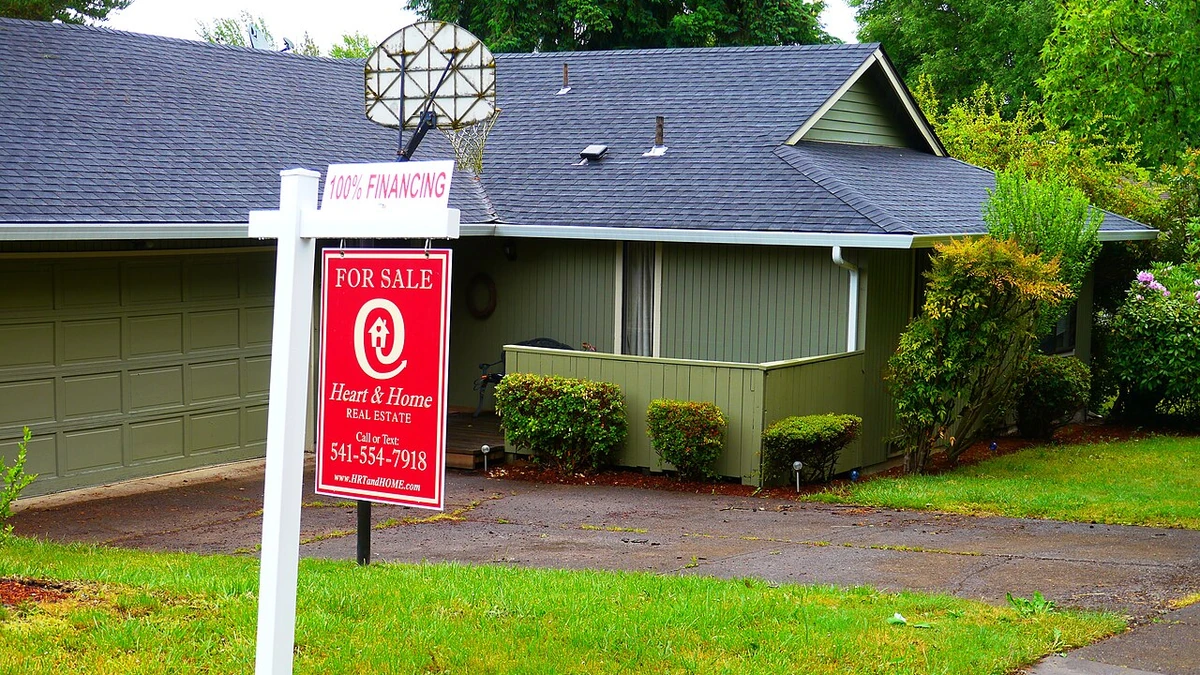
Sales of previously owned U.S. homes rose 1.5% in September, but the increase came from a depressed level of activity and did little to relieve pressure on a housing market constrained by costly mortgages. The National Association of Realtors (NAR) reported Tuesday that sales reached a seasonally adjusted annual rate of 3.99 million, still 2.2% below the pace a year earlier.
A small monthly advance can signal some buyers are finding ways to move despite high borrowing costs. It is not, on its own, evidence of a sustained recovery. NAR chief economist Lawrence Yun noted that August and September were the slowest months of the year, even after the September improvement. Mortgage rates have climbed further since the month ended, adding another obstacle for households considering a purchase.
The distinction between a monthly rebound and a stronger market is especially important for existing homes, which account for the great majority of U.S. home sales. NAR tracks closed purchases of houses, townhouses, condominiums and co-ops, so September’s report measures completed deals rather than the contracts buyers signed during the month. Its annualized rate describes what a full year would look like if September’s seasonally adjusted pace continued, not the actual number of homes sold in September.
More listings are giving buyers room to negotiate
Inventory and selling time point to a market with less urgency than in previous years. In its September existing-home sales report, NAR put unsold inventory at 1.60 million homes, up 4.6% from a year earlier. That represented 4.8 months of supply at the current selling pace, compared with 4.5 months a year ago. A larger selection gives buyers more alternatives, although national totals cannot capture the sharp differences between individual neighborhoods or price brackets.
Homes spent a median of 33 days on the market in September, two days longer than in August and the same as a year earlier. The measure does not establish that every seller is cutting a price, but additional listings and longer marketing periods can reduce the pressure on purchasers to make immediate offers. Yun said sellers might need to adjust prices or provide incentives to meet local demand rather than count on the competition that characterized tighter markets.
The national median existing-home sale price reached $417,500, a 1.3% increase from September 2025. That was the 39th consecutive month of annual price gains, according to NAR. The relatively modest increase suggests that the balance between demand and available homes is different from the conditions that once produced much faster appreciation. A national median is also affected by which homes sell, so it should not be treated as a measure of how much any particular property gained in value.
Buyers are not all responding to the same financing constraints. First-time purchasers made up 31% of September sales, compared with 30% in August. All-cash purchases accounted for 27%, unchanged on the month but below 30% a year ago. Investors and people buying second homes represented 20% of purchases, up from 15% in August and September 2025. These shares describe the buyers who successfully closed sales, not the larger pool of households that may still want a home but cannot qualify at current rates.
Mortgage rates create a tougher backdrop for the next reports
Mortgage borrowing costs had already been rising through September. NAR cited an average 30-year fixed mortgage rate of 6.86% for the month, up from 6.67% in August and 6.35% in September last year. Those differences matter to buyers because a higher interest rate raises the monthly payment on a given loan amount, even if the home’s price barely changes. The relationship also makes it harder for some purchasers to qualify under lenders’ debt-to-income requirements.
The pressure continued after the sales month ended. Freddie Mac’s Primary Mortgage Market Survey showed the 30-year fixed rate averaging 7.40% as of October 8, up from 7.28% the previous week and 6.30% at the same point in 2025. That October reading should not be mistaken for the mortgage rate buyers faced when every September purchase closed. It instead shows that the financing environment has become more difficult for purchases now being arranged.
Consider the difference for a borrower taking out a $350,000 fixed-rate mortgage over 30 years. At 6.30%, monthly principal and interest would be about $2,166; at 7.40%, about $2,423. That is roughly $257 more per month before property taxes, insurance, mortgage insurance or other ownership costs. The figures are illustrative calculations, not quotes available to an individual borrower, but they show why changes in mortgage rates can matter more to affordability than a small change in the median selling price.
NAR’s Housing Affordability Index was 105.4 in September, below 106.7 a year earlier. Affordability declined year over year in the Northeast, Midwest and South, with the West the only region showing an improvement in the index. The index is a national and regional gauge rather than a measure of what an individual household can pay. Still, it supports the picture that sales volumes remain restrained even as inventory offers buyers somewhat more leverage.
The South and West carried September’s sales increase
Regional data show that the month’s improvement was uneven. Sales increased 2.8% in both the South and West from August, reaching annualized rates of 1.86 million and 730,000, respectively. The Midwest was unchanged at 930,000, while the Northeast fell 2.1% to 470,000. All four regions registered fewer sales than in September 2025, so the monthly improvement was not a broad-based annual recovery.
Different types of housing also moved in opposite directions. Existing single-family home sales advanced 2.0% on the month to a 3.64 million annual pace, while condominium and co-op sales declined 2.8% to 350,000. The median single-family price was $422,700, up 1.2% on the year; the median condo and co-op price was $363,700, also up 1.2%. This split helps explain why the overall market could record a gain despite weakness in a smaller category.
The broader housing signal is therefore mixed. More homes are on the market, sellers are generally waiting longer, and September sales edged upward after a weak August. Yet annual sales remain lower, prices are still rising modestly, and the latest mortgage-rate figures point to a more challenging environment for new buyers. September’s closings cannot settle whether demand will hold up as those higher rates filter into offers and financing decisions.
The next scheduled NAR report on existing-home sales, covering October activity, is due November 12. It will provide a clearer reading on whether September’s increase marked the start of a recovery in completed purchases or only a temporary bounce in an otherwise subdued market.
More News
Latest News
View all news- JPMorgan Reports $15.3 Billion Third-Quarter Profit as Revenue Hits $50.2 Billion
- Johnson & Johnson Raises 2026 Sales Outlook After $25.4 Billion Third-Quarter Revenue
- Goldman Sachs Posts $5.29 Billion Q3 Profit and $17.01 Earnings Per Share
- FTC Seeks Contempt Sanctions Against Martin Shkreli Over Alleged Biotech Stock Trading
- DOJ Details Meta’s Removal of 3.7 Million Scam Accounts, Pages and Groups in Fraud Crackdown
