
Fed’s Waller Says Higher Treasury Yields Reflect Strong Growth More Than Inflation Expectations
Federal Reserve Governor Christopher Waller said the recent rise in longer-dated Treasury yields appears to reflect firm U.S. growth and other market forces more than a jump in long-run inflation expectations.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy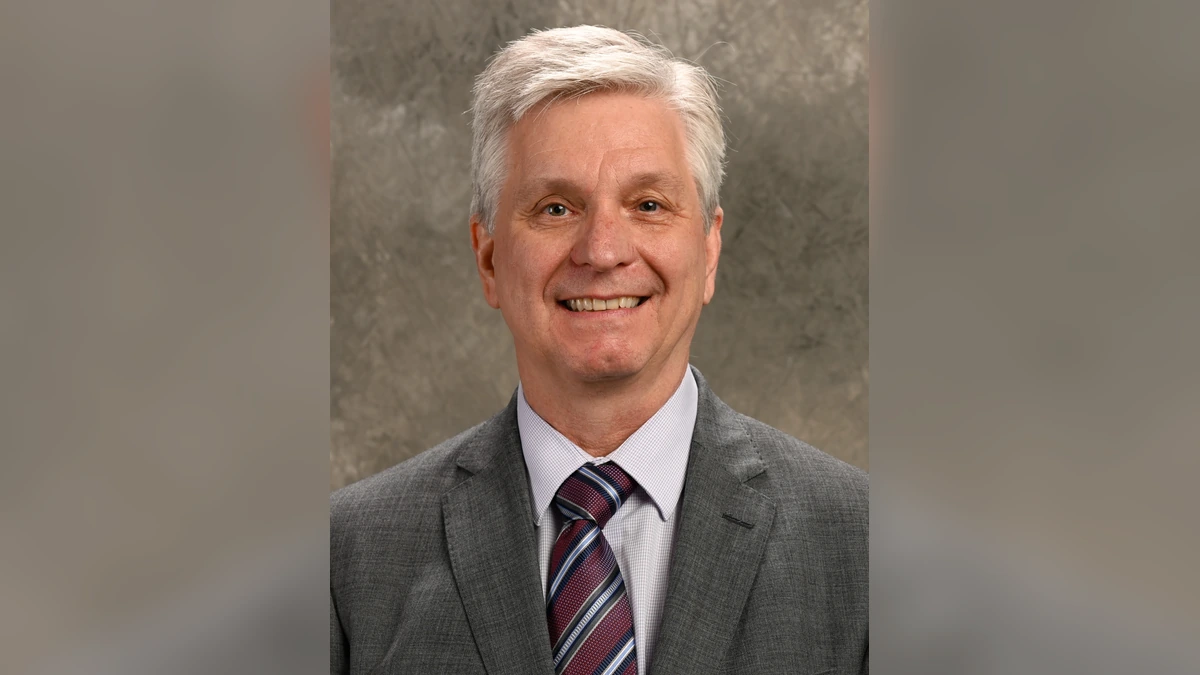
Federal Reserve Governor Christopher Waller said Tuesday that the recent rise in U.S. Treasury yields looks driven more by solid economic growth and other market forces than by a damaging shift in inflation expectations, according to Reuters. Speaking at a Bloomberg event in Mumbai, he said market-based inflation expectations remain well anchored even as longer-term borrowing costs climb.
The distinction matters because Fed officials do not read every increase in long-term yields the same way. If yields rise mainly because investors expect stronger real growth, heavier government borrowing or demand different compensation for holding long-dated debt, that can tighten financial conditions without necessarily signaling that the central bank is losing control of inflation. A rise driven by unmoored inflation expectations would point to a more serious policy problem and a more urgent monetary-policy response.
Waller pointed to growth and broader bond-market forces
According to Reuters, Waller said the move in yields appears to reflect economic strength more than a change in the public’s inflation outlook. He also pointed to several forces outside simple near-term Fed rate expectations: a bigger supply of government debt, sustained capital spending tied to artificial intelligence, and a softer global bid for U.S. Treasuries as the world’s unquestioned safe-haven asset. Reuters reported that Waller said weaker demand of that kind could be adding 50 to 70 basis points to yields.
Those comments fit a market environment in which investors have been forced to sort through several overlapping influences on long rates. A 10-year Treasury yield can move higher because the expected path of short-term Fed rates shifts up, because inflation compensation rises, or because investors demand a larger term premium to absorb duration risk and expanding Treasury issuance. When an official says higher yields are not mostly about inflation expectations, the implication is that growth, supply and term-premium dynamics may be doing more of the work than fears of a fresh inflation spiral.
The Federal Reserve Board’s October 2026 calendar shows Waller taking part in a Bloomberg New Economy Forum discussion in India on Oct. 13, in a slot labeled around AI. That backdrop is relevant because AI-related investment has become part of the explanation some policymakers and investors use for the economy’s resilience. If large capital outlays on data centers and related infrastructure are helping keep activity firmer than expected, it becomes easier to understand why real yields could rise even without a fresh break higher in long-run inflation expectations.
Why the inflation-expectations distinction matters for policy
Waller has spent much of this year drawing a line between inflation that remains too high and longer-run inflation expectations that, in his view, have not yet broken loose. In a July speech, he said market-based measures of inflation compensation over the two- to five-year horizon were still near the Fed’s 2% goal. In an Oct. 8 speech, he argued that a stronger labor market and persistent inflationary pressures had shifted the policy balance, but he still framed the question around incoming evidence rather than suggesting that the Fed had already lost its grip on inflation psychology.
That framework helps explain why Tuesday’s remarks are important. If inflation expectations remain anchored, the Fed can interpret higher long-term yields as partly doing the tightening on its behalf. Higher mortgage rates, corporate borrowing costs and hurdle rates for investment can slow demand even if the federal funds rate itself does not change at the next meeting. That does not automatically mean the central bank is finished. It does mean the discussion changes from whether markets are sending an inflation alarm to how much additional restraint policymakers still need to impose directly.
The other side of the argument is less comfortable. A growth-driven rise in yields can still keep pressure on the Fed if the same resilience that lifts real rates also keeps labor markets tight and demand firm enough to slow the return of inflation to target. Officials can therefore welcome evidence that expectations are anchored and still conclude that policy must stay restrictive. Reuters reported that Waller continued to sound open to further rate increases, which is consistent with the hawkish tone he has adopted when inflation progress appears incomplete or too slow.
Treasury yields remain central to the market outlook
Official Treasury data show why the issue has become central for investors. The U.S. Treasury’s Daily Treasury Rates page shows the 10-year par yield at 5.24% on Oct. 1, 5.67% on Oct. 2, 5.70% on Oct. 5 and 5.68% on Oct. 6. Those early-October readings underline how quickly long-term borrowing costs moved higher and why Fed officials have been pressed to explain whether the rise reflects inflation risk, stronger activity or a larger term premium.
Moves of that size matter far beyond the bond market. Mortgage rates, auto loans, corporate borrowing costs and equity valuation models all take their cue from the Treasury curve. When long rates jump because real growth looks stronger, that can coexist with a healthier economic story than a pure inflation scare would imply. At the same time, it can still tighten financial conditions enough to slow spending by households and businesses. For policymakers, the practical question is whether that market tightening will persist and whether it will do enough cooling work to reduce the need for another increase in the policy rate.
Investors therefore have two signals to weigh at once. One is Waller’s message that the bond market is not flashing a simple inflation-warning sign. The other is that elevated yields themselves can alter the macro outlook if they stay high. The Federal Reserve’s policy calendar shows the next Federal Open Market Committee meeting is scheduled for Oct. 27-28. Between now and then, officials will be watching inflation readings, labor-market data and the behavior of longer-dated yields to judge whether markets have merely reflected a stronger economy or have already delivered some of the restraint the Fed might otherwise have had to provide.
For now, Waller’s remarks argue for a more nuanced reading of the Treasury selloff. In his telling, the rise in yields says at least as much about growth, financing needs and the structure of demand for U.S. debt as it does about fears of runaway inflation. That does not resolve the policy debate. It does shape the next phase of it, because if inflation expectations stay contained while long rates remain elevated, the Fed will have to decide whether the bond market is simply recognizing a stronger economy or has already done part of the central bank’s job.
More News
Latest News
View all news- JPMorgan Reports $15.3 Billion Third-Quarter Profit as Revenue Hits $50.2 Billion
- Johnson & Johnson Raises 2026 Sales Outlook After $25.4 Billion Third-Quarter Revenue
- Goldman Sachs Posts $5.29 Billion Q3 Profit and $17.01 Earnings Per Share
- FTC Seeks Contempt Sanctions Against Martin Shkreli Over Alleged Biotech Stock Trading
- DOJ Details Meta’s Removal of 3.7 Million Scam Accounts, Pages and Groups in Fraud Crackdown
