
New York Manufacturing Index Jumps to 25.5, Highest Since December 2021
A sharp recovery in factory orders and shipments lifted New York manufacturing activity, even as supply constraints worsened and price pressures persisted.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy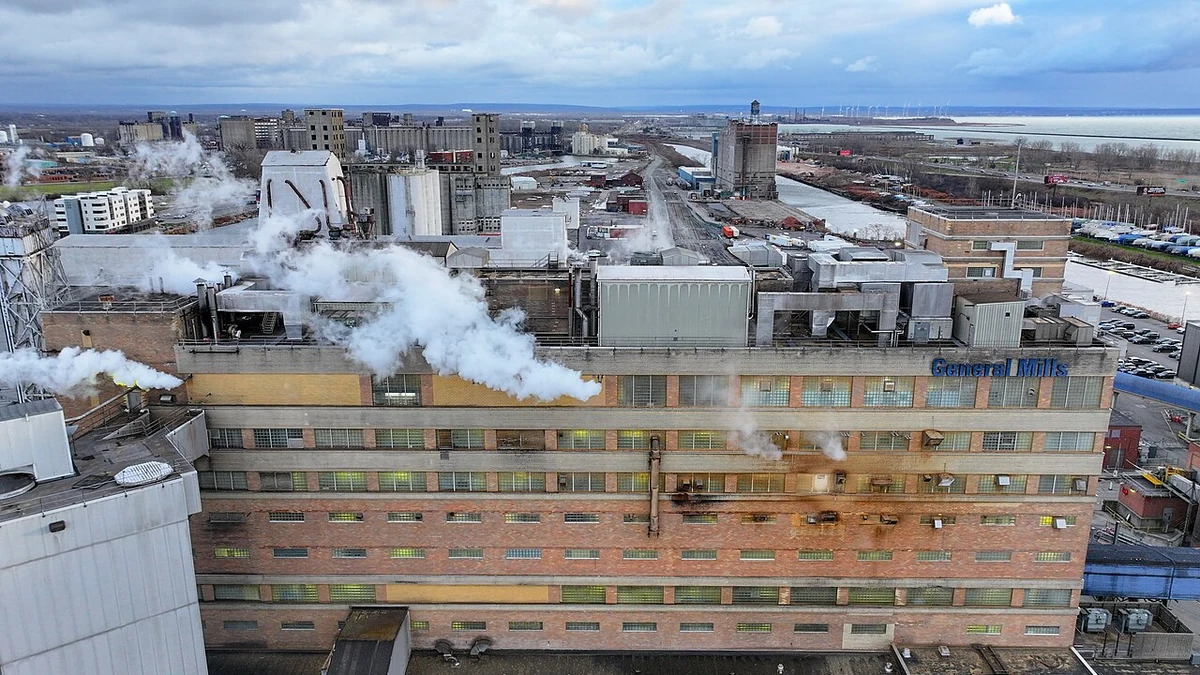
Manufacturing activity in New York State accelerated sharply in October, lifting the Federal Reserve Bank of New York’s general business conditions index to 25.5, its highest level since December 2021. The closely watched gauge was up from 7.6 in September, a gain of nearly 18 index points.
A rebound in demand accounted for much of the improvement. New orders rose strongly after barely increasing the previous month, and shipments returned to growth following a modest September decline. The strength was not matched by an equally upbeat six-month outlook: manufacturers became less optimistic about future business conditions even as their assessment of current activity improved.
The October Empire State Manufacturing Survey covered responses collected October 2–9. Its readings are diffusion indexes, measuring the difference between shares of respondents reporting increases and decreases. A level of 25.5 is therefore not a 25.5% jump in factory production, nor is this regional survey a measure of national manufacturing output.
Orders recover, but delivery delays and supply constraints persist
The new orders index climbed to 23.2 from 2.0 in September. That represented a marked change in what factories reported seeing in their order books: 42.9% of respondents said orders had increased, compared with 19.7% reporting a decrease. The balance was almost even a month earlier. This is one of the clearest reasons the headline index rebounded so decisively.
Shipments showed a comparable shift. Their index reached 13.1, up from -3.2, as the share of firms reporting higher shipments overtook the share reporting declines. The October figure points to an improvement in shipping activity across respondents, although it does not quantify how many goods were shipped or their total dollar value.
Evidence of stronger demand also appeared in unfinished work. The unfilled orders index advanced to 14.0 from 5.9, while the inventories index rose to 11.6 from 8.9. An increase in outstanding orders can accompany healthy demand, but it can also reflect difficulty filling orders promptly. The separate measures of delivery times and supplies make that distinction important in this survey.
Delivery times continued to lengthen, with the corresponding index at 19.8, compared with 18.8 in September. Supply availability deteriorated further: its index slipped to -15.1 from -11.9, the weakest reading since June 2022. The negative supply measure indicates that more respondents were seeing availability worsen than improve, even as their overall business conditions became stronger.
October consequently offers a more complicated picture than the headline alone suggests. Firms reported a broader pickup in business, but the same survey points to friction in getting inputs and moving work through production. Without data on the value of output or individual industries, the survey cannot establish how much of the demand improvement will translate into finished goods in the coming weeks.
Manufacturers become less optimistic about the months ahead
The gap between current conditions and expectations is unusually relevant this month. The index measuring business conditions expected six months ahead fell to 21.0 from 29.0. It remained positive, meaning firms still anticipated improvement overall, but confidence weakened at the same time that the current conditions index reached a nearly five-year high.
In October, 45.1% of manufacturers expected better general business conditions over the next six months and 24.2% expected worse conditions. In September, those shares were 50.5% and 21.5%, respectively. The change is a reminder that stronger orders today do not necessarily translate into a more confident assessment of the next half-year.
Forward-looking demand indicators were positive but not uniformly stronger. The expected new orders index declined to 22.4 from 25.3, while the expected shipments index edged up to 26.2 from 25.5. Hiring expectations remained positive as well. Capital spending plans, however, were subdued, with that index easing to 14.0 from 14.9, suggesting manufacturers were not significantly raising investment intentions in response to October’s reported surge.
Supply and cost expectations added another qualification. The future supply availability index fell to -11.6 from -8.9, indicating that respondents continued to anticipate worsening access to inputs. The six-month prices paid index increased to 70.9 from 67.3, and the future prices received index rose to 48.0 from 42.3. Both measures suggest that expectations for price increases became more widespread, even as the broad future activity index declined.
Prices stay elevated as factory employment grows modestly
Current pricing data were consistent with continued cost pressure. The prices paid index eased to 59.5 from 63.1, which the New York Fed had described as a four-year high in September. That retreat did not mean input costs were falling: 60.5% of October respondents reported higher prices paid, compared with only 1.0% reporting lower prices. The index captures the breadth of increases, not the rate at which prices rose.
The prices received index moved in the opposite direction, rising to 30.6 from 28.1. A larger net share of firms reported charging more for their goods. These figures are relevant to assessing the persistence of factory-level inflation pressure, but they do not provide a direct calculation of profit margins or establish how individual manufacturers are passing costs on to customers.
Labor conditions were steadier than the order figures. The number of employees index was 10.3, little changed from September’s 10.6, with the readings indicating modest employment growth. The average workweek index was also positive at 9.1, though it was down from 17.0. Respondents therefore reported continued increases in staffing and hours, but neither indicator exhibited the sharp month-to-month acceleration seen in orders.
Those distinctions matter when interpreting the October result. The Empire State survey asks a recurring group of New York manufacturing executives about changes in their businesses; the Fed says roughly 100 responses are typically received each month from a pool of about 200. It provides a timely reading of business conditions rather than a definitive account of manufacturing production or employment across the United States.
The next Empire State Manufacturing Survey is scheduled for November 16. Its orders, shipments and supply measures will offer a further check on whether October’s stronger activity was sustained while manufacturers faced longer delivery times and elevated costs.
More News
Latest News
View all news- Prologis Q3 Core FFO Rises to $1.60 a Share as Leasing Demand Holds Firm
- U.S. Natural Gas Storage Rises 67 Bcf to 3,567 Bcf, EIA Reports
- U.S. Business Inventories Increase 0.4% in August as Sales Climb 1.1%
- Philadelphia Fed Manufacturing Index Falls to 20.9 as Factory Growth Moderates
- ManpowerGroup Q3 Earnings Rise as Revenue Reaches $4.8 Billion
