
Prologis Q3 Core FFO Rises to $1.60 a Share as Leasing Demand Holds Firm
Prologis posted higher third-quarter core FFO and net earnings as leasing demand, occupancy and rent growth stayed solid across its logistics portfolio.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy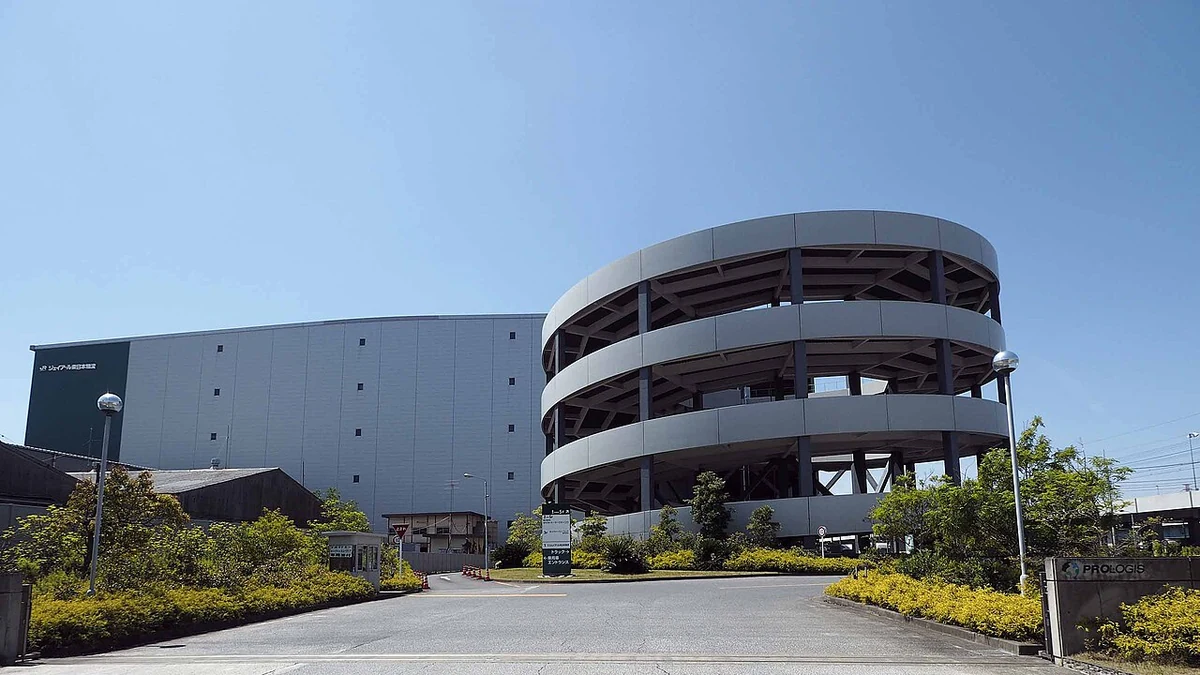
Prologis reported stronger third-quarter results on Thursday, with core funds from operations rising to $1.60 per diluted share from $1.49 a year earlier, as customer demand for warehouse space remained steady and rent growth stayed robust.
Net earnings per diluted share rose to $0.86 from $0.82 in the same quarter of 2025. The industrial real estate investment trust also said period-end occupancy improved to 95.6%, while cash same-store net operating income grew 5.9% and cash rent change reached 23.4% on a Prologis-share basis.
The company outlined the results in its third-quarter earnings release, which pointed to healthy demand from customers tied to e-commerce, advanced manufacturing and the build-out of data center supply chains. Those end markets matter for Prologis because they influence how much inventory customers hold and how much logistics space they need to lease near major population centers.
Signed leasing activity remained substantial at 60 million square feet during the quarter, even as the market continues to normalize from the exceptionally tight conditions that followed the pandemic-era logistics boom. For a landlord the size of Prologis, that volume suggests many large customers are still committing to distribution space rather than pulling back sharply on network capacity.
Leasing activity and rents continued to support operating performance
Operational metrics released with the quarter showed a business that is still performing from a position of strength. Average occupancy across the owned and managed portfolio was 95.1%, leases commenced in the operating and development portfolio totaled 55.9 million square feet, and retention came in at 75.9%.
Rent growth remained another important support for earnings. Prologis said net effective rent change reached 38.0%, while cash rent change was 23.4%. Those figures help explain why core FFO kept moving higher even though the company is operating in a period of slower economic growth and a higher interest-rate environment than in the ultra-cheap capital era that preceded it.
Scale remains a major advantage. According to the company’s supplemental report, Prologis owned or had investments in properties and development projects expected to total about 1.3 billion square feet in 20 countries at Sept. 30, serving roughly 6,500 customers. That breadth gives the company exposure to large global supply chains, but it also helps smooth results because leasing demand does not have to depend on a single market or customer group.
Investors also tend to focus on core FFO rather than only on net income when judging REIT performance because the measure strips out certain items and is designed to better reflect recurring operating results. On that basis, the move to $1.60 a share suggested that leasing demand and embedded rent growth were still translating into cash-generating performance even as the broader industrial property market moves back toward a more balanced footing.
Guidance was adjusted modestly while capital deployment moved higher
Management narrowed and lifted its 2026 core FFO guidance to $6.25 to $6.29 per diluted share, from a prior range of $6.22 to $6.30. That revision was modest, but it still signaled confidence that the company can hold earnings power near the upper part of its earlier forecast despite a mixed macroeconomic backdrop.
The outlook for net earnings attributable to common stockholders was revised to $4.05 to $4.15 per diluted share, versus the earlier $4.40 to $4.55 range. Prologis noted in its release that the net earnings guidance should be read alongside the U.K. Takeover Code disclosure tied to its offer for SEGRO.
Several operating assumptions changed at the same time. The top end of the average occupancy outlook was trimmed slightly to 95.50% from 95.75%, while cash same-store NOI guidance was raised to 7.00% to 7.50% from 6.75% to 7.25%. Net effective same-store NOI guidance was also nudged up, to 5.50% to 6.00% from 5.25% to 5.75%.
Capital deployment expectations moved higher as well. Development stabilizations were increased to a range of $2.5 billion to $3.0 billion, development starts to $5.0 billion to $5.75 billion and acquisitions to $2.1 billion to $2.3 billion. At the same time, expected contributions and dispositions were revised lower at the midpoint, while realized development gains were left unchanged.
The more detailed supplemental financial report filed with the SEC showed that third-quarter acquisitions totaled $702 million, development stabilizations reached $401 million and development starts came to $964 million on a Prologis-share basis. Dispositions and contributions totaled $169 million. Taken together, those figures show a company still actively allocating capital rather than simply defending its existing portfolio.
Liquidity remained strong as Prologis advanced broader strategic plans
Balance-sheet capacity remains one of the more important parts of the Prologis investment case, especially at a time when real estate companies must weigh expansion opportunities against borrowing costs. During the quarter, Prologis and its co-investment ventures closed an aggregate $1.3 billion of debt at a weighted average interest rate of 4.0% and a weighted average term of 4.5 years.
By quarter-end, available liquidity stood at about $8.8 billion. Debt to adjusted EBITDA was 4.5 times, and debt represented 23.9% of total market capitalization. The weighted average interest rate on the company’s share of total debt was 3.3%, with a weighted average term of 7.6 years. Those figures indicate that Prologis still has funding flexibility even as financing conditions remain more restrictive than they were several years ago.
The company also said 99% of forecast earnings for 2026, 98% for 2027 and 97% for 2028 are in U.S. dollars or hedged through derivative contracts, and that 96% of its equity was in U.S. dollars at quarter-end. That currency profile reduces one source of volatility for a global landlord whose portfolio spans North America, Europe, Asia and other markets.
Management also highlighted progress on its pending acquisition of SEGRO, saying shareholder approval marked an important milestone. Prologis did not use the earnings release to declare the acquisition complete, but the reference underscored that the company is still pursuing a larger European platform alongside its ongoing leasing, development and capital-allocation work.
For investors, the quarter’s main message was relatively straightforward: leasing demand has cooled from the hottest periods of the cycle but remains healthy enough to support high occupancy, strong rent spreads and growing core FFO. That combination, together with a large liquidity buffer and active development pipeline, leaves Prologis entering the final stretch of 2026 with operating momentum still intact.
More from Investing
Latest News
View all news- U.S. Producer Prices Surge 1.3% in September, Biggest Monthly Increase Since 2022
- U.S. Retail Sales Rise 0.8% in September to $745 Billion
- U.S. Weekly Jobless Claims Edge Up to 199,000 as Layoffs Remain Low
- U.S. Natural Gas Storage Rises 67 Bcf to 3,567 Bcf, EIA Reports
- U.S. Business Inventories Increase 0.4% in August as Sales Climb 1.1%
