
Cleveland-Cliffs Returns to Profit With $165 Million in Third-Quarter Net Income
Cleveland-Cliffs swung back to profit in the third quarter as steel pricing, shipments and costs improved, while management projected higher adjusted EBITDA in the fourth quarter.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy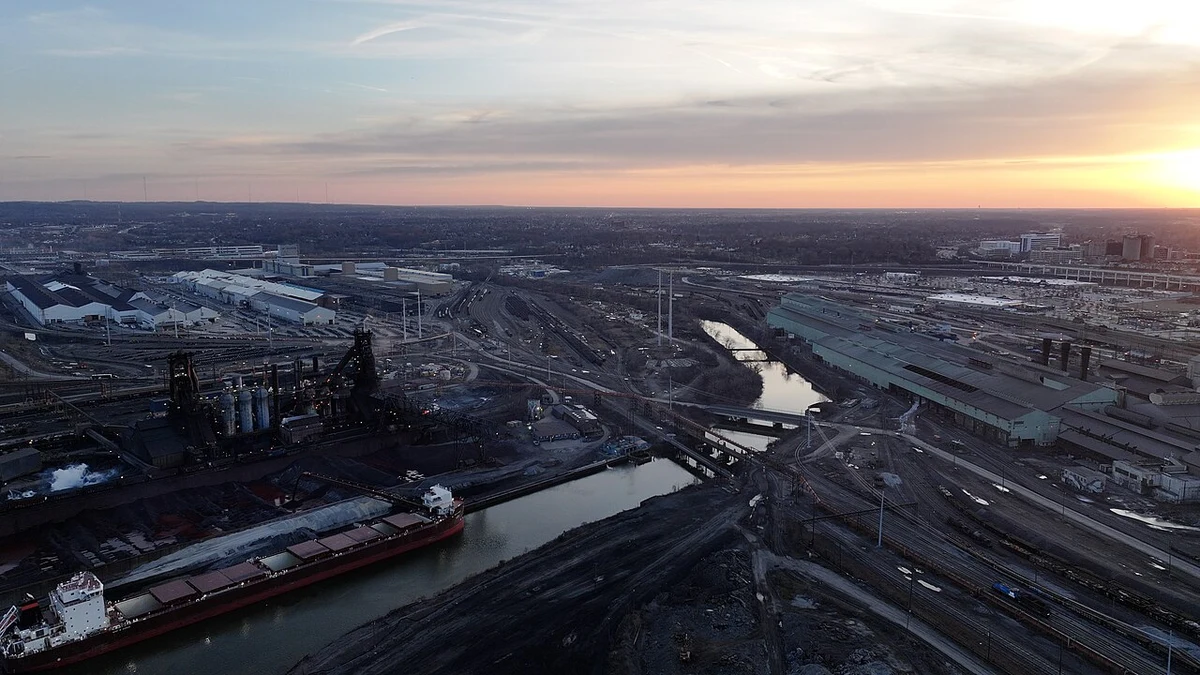
Cleveland-Cliffs returned to profit in the third quarter, reporting net income of $165 million after posting a loss in the prior quarter, as the steelmaker benefited from higher selling prices, slightly stronger shipments and lower unit costs.
The company said revenue rose to $5.6 billion in the three months ended Sept. 30, from $5.2 billion in the second quarter. Adjusted EBITDA climbed to $612 million, more than double the prior quarter’s $286 million, while diluted earnings came in at $0.26 a share on a GAAP basis.
The result marked a notable turn from the June quarter, when Cleveland-Cliffs reported a GAAP net loss of $134 million. It also represented the company’s strongest quarter in three years on an adjusted EBITDA basis, according to management in its third-quarter earnings release.
Pricing and shipments lifted quarterly earnings
Third-quarter steel product sales volumes totaled 4.15 million net tons, compared with 4.03 million a year earlier and 4.03 million in the second quarter. Average net selling price per ton improved to $1,177, up from $1,124 in the prior quarter and from $1,032 in the year-earlier period. Those gains mattered because Cleveland-Cliffs remains heavily tied to the health of North American steel pricing, especially in flat-rolled products.
Within the shipment mix, 46% of third-quarter steel sales volume came from hot-rolled steel, 31% from coated products, 15% from cold-rolled products, and the remainder from plate plus stainless and electrical products. That mix matters because value-added coated and cold-rolled products generally carry different pricing and margin profiles than commodity-grade hot-rolled steel.
The company’s steelmaking segment generated $5.447 billion in revenue during the quarter and produced cash margin of $685 million, up sharply from $349 million in the second quarter. Gross margin for the segment improved to $454 million from $113 million in the prior quarter and from a negative $56 million in the year-earlier quarter. Cleveland-Cliffs said lower cash cost of goods sold also supported the recovery.
Sales to distributors and converters represented the largest end market, accounting for $1.8 billion of steelmaking revenue, or 34% of the total. Automotive and infrastructure and manufacturing each contributed about $1.5 billion, or 28% apiece, while sales to other steel producers accounted for $532 million, or 10% of steelmaking revenue. That customer split shows that Cleveland-Cliffs remains broadly exposed to industrial demand rather than dependent on a single outlet.
Liquidity stood at $3.2 billion at Sept. 30, compared with $3.1 billion at June 30. Management said debt declined during the quarter and signaled that additional debt reduction could come in the fourth quarter with the help of stronger free cash flow and property sale proceeds. The company did not, in the earnings release, provide a detailed quarter-end debt table alongside that comment.
Stelco contribution improved as Cliffs reshaped Canadian operations
Chairman and Chief Executive Officer Lourenco Goncalves said the company’s Canadian operation, Stelco, delivered its strongest quarter since Cleveland-Cliffs acquired it two years ago. He attributed that improvement to a better Canadian hot-rolled market, which turned Stelco into a positive contributor to adjusted EBITDA during the quarter.
At the same time, management said it decided to indefinitely idle galvanizing lines at Stelco because it does not expect policy action soon enough to address what it described as an oversupplied galvanized steel market in Canada. Cleveland-Cliffs said the move would not cut total production tonnage at Stelco because the company intends to concentrate on hot-rolled products that it believes have stronger market demand.
The company also said about 2,000 Canadian jobs would be preserved under that operating plan. That detail matters because it suggests Cleveland-Cliffs is trying to protect output and employment even as it pulls back from a weaker product niche. For investors, the more immediate takeaway is that the Canadian business is no longer acting as the kind of drag that has complicated earnings in prior periods.
Management tied the broader quarter to better discipline on price, volume and cost. Goncalves said all three moved in the right direction from the second quarter, helping Cleveland-Cliffs outperform the $575 million adjusted EBITDA guidance it had provided three months earlier. Beating internal guidance does not by itself guarantee a sustained upcycle, but it does indicate that conditions improved faster than the company itself had projected in mid-summer.
Fourth-quarter guidance and 2027 outlook point to further improvement
Cleveland-Cliffs said it expects fourth-quarter 2026 adjusted EBITDA of about $715 million. That would represent another step up from the third quarter, though management cautioned that typical year-end seasonality, planned maintenance outages, higher input costs and incentive compensation accruals will partly offset the benefit of increased pricing.
The company also offered a more upbeat longer-range view. Based on contract changes already signed with customers and prevailing price forecasts, Cleveland-Cliffs said it expects 2027 adjusted EBITDA to exceed $4 billion. Management linked that outlook to what it described as a supportive trade environment for U.S. steel, with import volumes still below historical levels and customers placing greater value on domestic supply chains.
Those projections were also filed with the Securities and Exchange Commission as part of the company’s Form 8-K earnings exhibit, which repeated the company’s expectation for fourth-quarter adjusted EBITDA of roughly $715 million and a 2027 figure above $4 billion. Because both figures are management guidance rather than reported results, they should be read as expectations, not confirmed outcomes.
The third-quarter report nonetheless gives Cleveland-Cliffs a stronger base heading into year-end. Revenue improved, margins widened, the company returned to profitability, and management now sees another sequential improvement in adjusted EBITDA in the current quarter. The next key test will be whether stronger pricing and contract terms hold up well enough for Cleveland-Cliffs to convert this quarter’s rebound into the larger earnings profile it is projecting for 2027.
More from Investing
Latest News
View all news- USPS Introduces New Rules for International Mailers Facing Customs Charges
- U.S. Treasury Sanctions Chinese Venture-Capital Funds Under Intellectual-Property Law
- IRS Finalizes Framework for Direct Credit- and Debit-Card Tax Payments
- Fifth Third Reports $1.13 Adjusted Third-Quarter EPS Following Comerica Conversion
- DOJ Reports $849 Million in Approved Claims Under Expanded Radiation Compensation Program
