AT&T Reports 5.3% Revenue Growth, Updates Earnings and Investment Outlook
The telecom company lifted its full-year adjusted earnings forecast as internet customer additions grew, while trimming planned network investment for 2027 and 2028.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy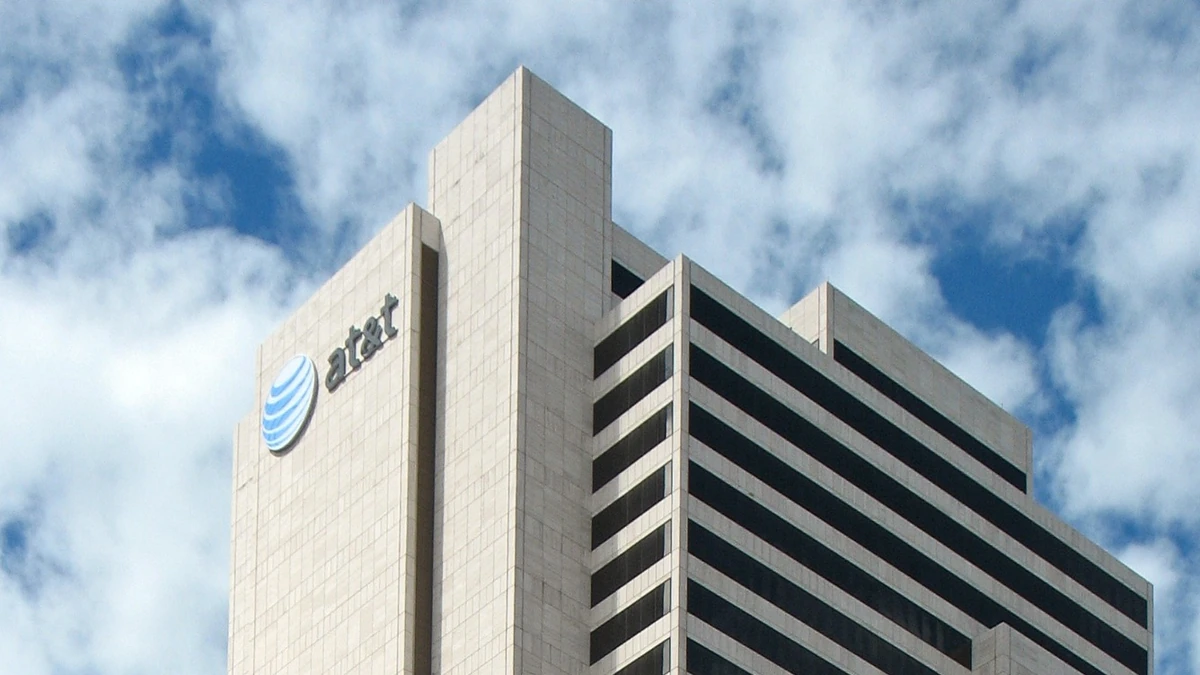
AT&T reported third-quarter revenue of $32.3 billion, up 5.3% from a year earlier, and raised its 2026 adjusted earnings outlook as demand for fiber and wireless services supported growth. The company also cut its capital investment forecasts for 2027 and 2028, while retaining its spending range for this year.
The results, released October 21, show how AT&T’s expansion in newer connectivity services is reshaping its finances. Adjusted profit rose, although reported earnings were weighed down by a charge related to the planned sale of its Mexico wireless business. The distinction matters because the company is forecasting stronger underlying earnings alongside substantial spending on its network.
Revenue growth extends beyond subscriber services
AT&T’s third-quarter earnings release put revenue at $32.322 billion, compared with $30.709 billion a year earlier. Growth came from wireless services, equipment sales and fiber operations, including the contribution of a business acquired this year. Declining revenue from older copper-based services partly offset those gains.
The financial schedules filed with the Securities and Exchange Commission show service revenue increased 3.8% to $26.301 billion. Equipment revenue grew faster, climbing 12.1% to $6.021 billion. This means the 5.3% increase in total revenue was not solely the result of customers paying more for ongoing phone and internet subscriptions.
Within Advanced Connectivity, which includes the company’s principal wireless and newer internet operations, revenue grew 7.2% to $29.481 billion. Service revenue in that segment increased 6.1% to $23.902 billion. Wireless service sales rose 5.0% to $17.764 billion, and advanced home internet revenue climbed 23.4% to $2.975 billion.
The home internet figure includes customers and operations from AT&T’s acquisition of substantially all of Lumen’s mass-markets fiber business, which closed in February. The acquired business contributed to reported fiber revenue growth, so the published increases should not be mistaken for a measure of growth from AT&T’s pre-existing customer base alone.
There was a sharp contrast between reported and adjusted profits. Diluted earnings from continuing operations were $0.13 per share, down from $1.29 a year earlier. AT&T recorded a $2.6 billion noncash impairment associated with its Mexico wireless business, which it has agreed to sell. The comparable 2025 quarter also benefited from a gain on the sale of its DIRECTV investment.
After removing specified items, adjusted earnings were $0.65 per share, up from $0.54. AT&T’s operating expenses increased to $28.2 billion from $24.6 billion, reflecting the impairment as well as separation charges, higher equipment costs and other expenses. Reported operating income fell to $4.1 billion from $6.1 billion, but adjusted operating income increased to $7.6 billion from $6.6 billion.
Cash performance offered another view of the quarter. Operating cash flow from continuing operations was $10.5 billion, compared with $10.2 billion a year ago, and free cash flow edged up to $5.0 billion from $4.9 billion. Adjusted EBITDA, another measure that excludes certain accounting items, rose 5.4% to $12.5 billion. These measures are not interchangeable with reported net income, and AT&T supplies reconciliations for its non-GAAP figures.
Fiber additions rise as the older copper business contracts
Customer additions were concentrated in AT&T’s newer internet services. The company reported a record 769,000 net additions across its consumer and business Advanced Connectivity internet offerings, comprising 442,000 fiber connections and 327,000 fixed-wireless connections. It also added 379,000 postpaid phone customers, with postpaid phone churn of 0.92%.
AT&T is increasingly seeking households that buy both home internet and mobile service. It said the number of these converged relationships grew by approximately 350,000 during the quarter. Among households with AT&T’s advanced home internet services, 42.8% also had AT&T wireless service. That percentage describes an overlap within the company’s advanced home internet base, not its share of the wider U.S. broadband market.
Its fiber footprint reached 39.7 million consumer and business locations by the end of September. AT&T expects that measure to exceed 40 million by the end of 2026 and 60 million by the end of 2030. The figure includes both locations served by AT&T’s own network and locations reached through fiber ventures, including assets associated with its recent acquisition.
The transition is also shrinking a different part of the business. Legacy segment revenue fell 24.5% from a year earlier as customers moved away from older copper-based connections. Legacy operating income was $498 million, down $181 million. AT&T aims to decommission the large majority of its copper network by the end of 2029, although it cautions that necessary approvals could delay the retirement of infrastructure in some areas.
That divergence between growth in newer networks and contraction in older services helps explain AT&T’s investment priorities. Building out fiber increases potential customer reach, but it requires capital before customers are connected. Retiring copper networks can eventually remove costs, provided customers are migrated and network shutdowns can proceed. AT&T has not portrayed those operational changes as complete.
AT&T raises 2026 earnings outlook but trims later investment
For the full year, management now expects adjusted earnings of approximately $2.40 per share. That is an increase from the $2.25-to-$2.35 range reiterated in July. The company also sees adjusted EBITDA growth in the upper portion of its previous 3% to 4% range for 2026, with growth of at least 5% projected by 2028.
Its updated capital investment plans are more selective. AT&T retained the $23 billion-to-$24 billion range for 2026 but lowered its expectation for each of 2027 and 2028 to $22 billion-to-$23 billion, versus the $23 billion-to-$24 billion annual range set out in its second-quarter outlook. The change amounts to a $1 billion reduction at both ends of the projected yearly range for those later years; it is not a cut to the current year’s forecast.
Capital investment is an AT&T-defined measure that includes traditional capital expenditures and cash paid under vendor-financing arrangements. In the third quarter, the company recorded $5.1 billion in capital expenditures and $0.5 billion in vendor-financing payments, producing $5.6 billion of capital investment. Treating those different figures as though they describe the same spending measure would misstate the comparison with guidance.
AT&T kept its free cash flow expectations of at least $18 billion in 2026, $19 billion in 2027 and $21 billion in 2028. These remain forecasts rather than committed results. Its long-term guidance is presented on a continuing-operations basis and excludes certain discontinued operations; the figures for 2027 and 2028 also exclude the Mexico wireless business that is currently held for sale.
Cash returns to investors remain a central part of the financial plan. AT&T expects to maintain its current annualized common-stock dividend of $1.11 per share and now projects at least $24 billion of share repurchases across 2026 through 2028, including approximately $10 billion this year. It says dividends and repurchases together are expected to return at least $45 billion over that three-year period. In the third quarter alone, total shareholder returns were approximately $4.8 billion, including $2.8 billion in common-stock buybacks.
Debt remains a constraint on how aggressively the company can deploy cash. AT&T reported $159.6 billion in total debt and $149.8 billion in net debt at September 30, reflecting an increase following the closing of its EchoStar spectrum purchase. Management expects the ratio of net debt to adjusted EBITDA to return to a level consistent with its roughly 2.5-times target during 2029.
The near-term operating milestone is AT&T’s expectation of reaching more than 40 million locations with fiber by the end of 2026. Progress toward that target, alongside cash generation and the planned sale of the Mexico business, will provide concrete evidence of how the higher earnings forecast and revised investment budget translate into results.
More from Investing
Latest News
View all news- U.S. Median Weekly Pay Rises 1.5%, Trailing 3.5% Consumer Inflation
- U.S. Mortgage Applications Drop 5.3% Even as 30-Year Rate Falls to 7.41%
- U.S. Energy Department Offers Up to 315,000 Barrels From Heating Oil Reserve
- U.S. Crude Inventories Fall 3.1 Million Barrels in Latest EIA Report
- OCC Issues Final Rule to Implement GENIUS Act Stablecoin Regulations