
New U.S. Home Sales Slip 0.6% in September to 676,000 Annual Rate
The supply of newly built houses eased to 8.4 months, while the median sale price rose from August but remained below its year-earlier level.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy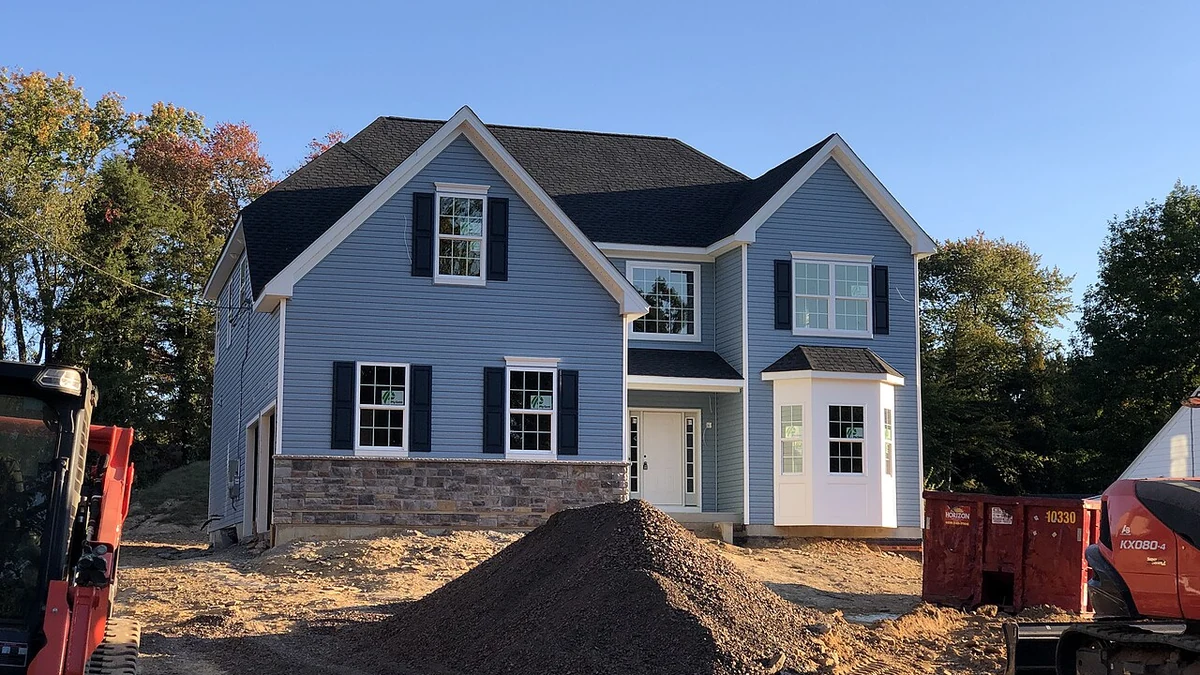
Sales of new single-family homes slipped 0.6% in September to a seasonally adjusted annual rate of 676,000, compared with a revised 680,000 in August. The figures reported Tuesday from the U.S. Census Bureau and Department of Housing and Urban Development also put sales 5.3% below the 714,000 pace recorded a year earlier.
The month-to-month decline was small, but it adds to evidence that demand for newly built houses remains uneven. The number of properties available for sale fell, yet the supply of unsold homes still exceeded eight months at September’s sales pace. Higher mortgage costs and weak buyer traffic have given builders little reason to assume that a sustained recovery is underway.
The Census Bureau’s New Residential Sales program measures newly built single-family houses sold through a signed contract or accepted deposit, including houses that have not yet been completed. Its headline rate is annualized and adjusted for seasonal patterns. It does not mean 676,000 new homes changed hands during September itself.
That distinction matters when interpreting a narrow monthly movement. New-home sales are measured through a sample survey, and initial estimates can change as additional information becomes available. A difference of a few thousand in the annualized rate should not be mistaken for a decisive shift in the housing market.
August’s downward revision narrows the monthly decline
September’s 676,000 reading was 4,000 below the revised August figure of 680,000. When the August report was initially published, its estimate stood at 684,000. The subsequent revision reduced the starting point for September’s comparison, illustrating why revisions need to be considered alongside each new monthly number.
The annual comparison gives a broader perspective. September’s rate was 38,000 below the 714,000 recorded in September 2025, a 5.3% decrease. That year-over-year gap is larger than the monthly change, although both comparisons are subject to the statistical uncertainty inherent in the survey.
A seasonally adjusted annual rate is especially useful for comparing one month with another because ordinary seasonal buying patterns are removed. Even so, it should be read as an estimated pace rather than as a count of completed purchases. The Census survey identifies a sale when an agreement is made, not when the buyer moves in or the mortgage closes.
For builders, contracts offer an early indication of demand for new supply. The timing can also create a gap between sales and construction activity: a house may be sold before work begins, during construction or after completion. Monthly sales figures therefore cannot be equated directly with the number of housing units newly started or finished.
Fewer homes for sale, but inventory remains substantial
The estimated number of new houses for sale declined to 476,000 at the end of September, from a revised 481,000 in August. Inventory was also 2.3% lower than the 487,000 available a year earlier. The reduction in listings did not produce a correspondingly tight market because sales remained subdued.
At the reported sales pace, the available stock represented 8.4 months of supply, compared with 8.5 months in August and 8.2 months in September 2025. Months of supply expresses how long the current stock would last if homes kept selling at the prevailing rate and no additional supply was added. It is a gauge of the balance between new-home listings and buyer demand, not a prediction that every property will sell within that exact period.
The price figures moved differently from sales volumes. The median price of a new home sold in September was reported at $400,400, up from a revised $385,400 in August. That is a 3.9% monthly increase, although the September median remained 3.9% below its year-earlier level. The average sale price, at $472,800, was up slightly on the month but 6.7% lower than a year earlier.
Neither the monthly increase in the median nor the drop from a year ago measures changes in the value of an otherwise identical house. Median and average selling prices can shift when the mix of properties sold changes by size, location or price range. The apparent rebound in September’s median is therefore not, by itself, evidence that house prices broadly accelerated.
The inventory numbers also leave room for variation in builder strategies. A company with finished houses still waiting for buyers faces a different cost calculation from a builder holding vacant lots or homes in earlier stages of construction. The national report summarizes these different conditions, so it cannot explain the pressures facing every local market.
Mortgage costs and construction figures point to continuing pressure
Financing costs remain central to the outlook. Freddie Mac’s weekly mortgage survey put the average 30-year fixed mortgage rate at 7.32% on October 22, down from 7.40% a week earlier but above the 7.03% recorded on September 24. The latest reading came after the month covered by the new-home sales report, so it should not be treated as the rate paid by September buyers.
Rates above 7% make the monthly principal-and-interest payment on a typical mortgage larger than it would be with lower-cost financing. That limits how much some households can borrow at a given payment level and can lengthen the time it takes builders to secure contracts. Builder concessions, including mortgage-rate buydowns, may soften the effect for some buyers, although the sales release does not measure how much those incentives contributed.
Builders themselves described weaker conditions in October. The National Association of Home Builders/Wells Fargo Housing Market Index fell three points to 29, its lowest reading since June 2012. In the association’s survey, 43% of builders reported cutting prices in October, and 65% said they were using sales incentives. Those responses measure industry sentiment and reported practices, not a separate count of completed home sales.
Construction data for September offered a similar note of caution. The Census Bureau reported that single-family housing starts fell 4.6% to an annualized 859,000, while single-family building permits dropped 4.0% to 845,000. Both measure activity at different stages of development rather than signed new-home sales contracts, but together they help show why the pace of future building may respond to softer demand.
Conditions in the existing-home market were not identical. The National Association of Realtors reported a 1.5% monthly rise in September sales of previously owned homes, to a 3.99 million annual rate, even as those sales were down 2.2% from a year earlier. The existing-home market had a 4.8-month supply, substantially below the 8.4 months reported for newly built houses. The measures cover different segments and should not be treated as directly interchangeable.
The next Census Bureau report on new residential sales is scheduled for November 25 and will cover October. It will provide another reading on whether sales are stabilizing as mortgage costs rise and builders adjust the amount of housing they bring to market.
More News
Latest News
View all news- UPS Revenue Climbs 6.7% to $22.9 Billion as Company Raises 2026 Outlook
- Richmond Fed Manufacturing Index Holds at Minus 2 as New Orders Weaken
- FTC Begins $15.8 Million Refund Distribution to 2.1 Million Cleo AI Customers
- U.S. Home Prices Rise 0.3% in August, FHFA Reports
- Coca-Cola Raises 2026 Guidance After Third-Quarter Revenue Grows 7%
