
Chicago Business Barometer Falls to 55.3 in October but Signals Continued Expansion
The Chicago-area activity gauge slipped from 58.8 in September as production and order measures softened, even as employment rebounded.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy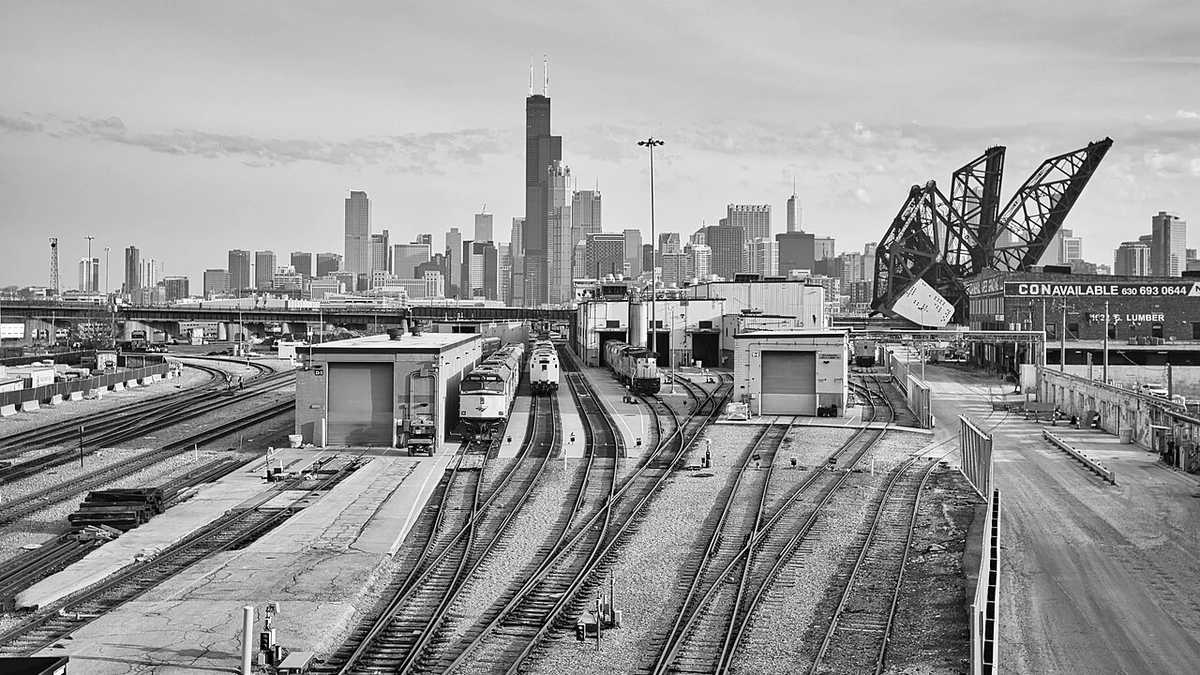
Business activity in the Chicago area continued to expand in October, although the pace slowed after a sharp rebound the previous month. The Chicago Business Barometer fell 3.5 points to 55.3 from 58.8 in September, according to MNI Indicators. It remained above the 50-point line that separates expansion from contraction for a second consecutive month.
The drop shows that conditions were less favorable than in September, not that regional economic output shrank by 3.5%. The barometer is a survey-based measure of the direction of business activity, and its level stayed on the expansionary side. September’s reading had jumped 11.7 points following an August dip below 50, making October’s retreat a partial reversal of that recovery.
The October survey results showed weakness in four of the five components that make up the headline index: supplier deliveries, production, order backlogs and new orders. Employment was the exception, rising sharply enough to offset part of the decline. Separate measures of input prices and inventories added to a picture of continued activity accompanied by uneven demand and rising costs.
Production and orders soften after September rebound
Production fell 5.2 points, but its index stayed above 50 for a second month. That distinction matters: the survey suggests production activity was still improving overall among respondents, just less strongly than in September. A fall in the production component does not mean factories or other surveyed businesses cut output by 5.2%.
New Orders edged down only 0.6 point and remained firmly in expansionary territory, also for a second consecutive month. The relatively small change suggests the flow of new business held up better than production or supplier deliveries. It offers some support for the view that October’s lower headline reading was a cooling of momentum rather than a broad loss of demand.
Order Backlogs presented a weaker picture. That component slipped 4.4 points and remained below the neutral threshold for a fourth straight month, although it was still above its August low. A shrinking backlog can reflect work being completed faster than new orders arrive, weaker incoming demand, or some mix of the two. The survey result alone does not establish which explanation dominated.
Inventories improved modestly, rising 4.0 points, yet the index remained in contractionary territory for a third consecutive month. That suggests inventory conditions had not turned decisively positive despite the pickup. Set beside the still-contracting order backlogs, the inventory reading leaves less room to describe October as an across-the-board expansion.
Supplier Deliveries recorded the largest fall among the headline components, sliding 10.3 points to the lowest level since February. The measure nevertheless stayed in expansionary territory for a 21st consecutive month. MNI said the decline largely unwound September’s increase, with respondents giving mixed accounts of delivery conditions. Some reported shorter delivery times that were still slow, while others continued to encounter delays on shipments from Asia.
Supplier delivery readings also need care when interpreting the overall barometer. Slower deliveries can lift that particular diffusion measure, even when the cause is a bottleneck rather than stronger demand. A decrease in the component therefore does not carry exactly the same meaning as a drop in production or new orders. Its sharp fall helped pull down the October composite, but it should not be treated as proof that sales or output collapsed.
Employment strengthens as input prices rise
The strongest counterweight to weaker activity came from Employment. Its index rose 10.3 points, returning to expansionary territory after slipping below 50 in September. The October reading was the highest since April 2021, reflecting a larger share of businesses reporting that employment had increased. This improvement ran against the direction of the headline barometer and the production and order measures.
The hiring signal is meaningful, but it has limits. A survey component tracks whether participating businesses report higher, lower or unchanged staffing, rather than counting the number of jobs created. It cannot by itself establish that overall Chicago employment or national payrolls grew at a comparable pace. The contrast between firmer staffing and softer production is still an important feature of October’s results.
Businesses also reported a renewed rise in costs. The Prices Paid index increased 8.9 points to its highest level since December 2021. Respondents highlighted chemical- and petroleum-based inputs as well as fuel surcharges and freight expenses. For an eighth straight month, none reported paying lower prices than in the preceding month, according to the survey’s summary.
Prices Paid is not one of the five components used to calculate the headline barometer, so its rise did not mechanically push the 55.3 reading higher. It is a separate indication that cost pressures remained prominent even as some measures of activity eased. Such costs can put pressure on business margins, although the survey does not show how much firms were able to pass along to customers.
A regional signal, not an output estimate
The Chicago Business Barometer, often called the Chicago PMI, is a weighted diffusion index based on New Orders, Production, Employment, Order Backlogs and Supplier Deliveries. A reading of 50 is neutral; values above it point to expansion, and values below it signal contraction. The numbers describe the direction and breadth of reported changes, not a percentage growth rate for the regional economy.
The survey draws on purchasing and supply-management professionals working for businesses in the Chicago area, primarily members of ISM Chicago, as the regional ISM chapter explains. That makes it a useful early reading on operating conditions, but not a direct substitute for official measures of U.S. production, employment or gross domestic product. Changes in the mix of its components can make one monthly headline less straightforward than it first appears.
October illustrated that limitation particularly well. Production and new orders remained expansionary, and employment strengthened substantially, but backlogs were still shrinking and the supplier-deliveries component weakened sharply. Rising input prices presented a different concern from the slower growth pace. The net reading was positive, even though the details showed neither uniformly stronger demand nor broad cost relief.
MNI collected responses from October 1 through October 13, so the result reflects conditions reported early in the month rather than a complete accounting of everything that happened through October 31. That timing is useful for an advance business survey, but it is another reason to avoid treating the reading as a precise measure of full-month output.
The next Chicago Business Barometer is scheduled for November 30, according to MNI’s published release calendar. Its production, orders and backlogs measures will help show whether the October pullback was a temporary pause after September’s rebound, while the employment and prices-paid readings will provide a further check on hiring and cost pressures.
More News
Latest News
View all news- Chevron Posts $9.9 Billion Quarterly Profit as U.S. Refinery Throughput Hits Record
- AbbVie Raises 2026 Earnings Outlook After Revenue Climbs 10.3%
- Federal Radiation Compensation Approvals Reach $909 Million, With More Than 50,000 Claims Pending
- Spain Inflation Holds at 4.9% in October as Core Stays at 3.1%
- Italy Inflation Surges to 5.4% in October as Energy Prices Jump
