
Treasury Sets 5.51% Rate for Newly Issued Series I Savings Bonds
I bonds issued through April 2027 carry a 1.40% fixed rate, while the inflation-linked portion will reset after the first six months.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy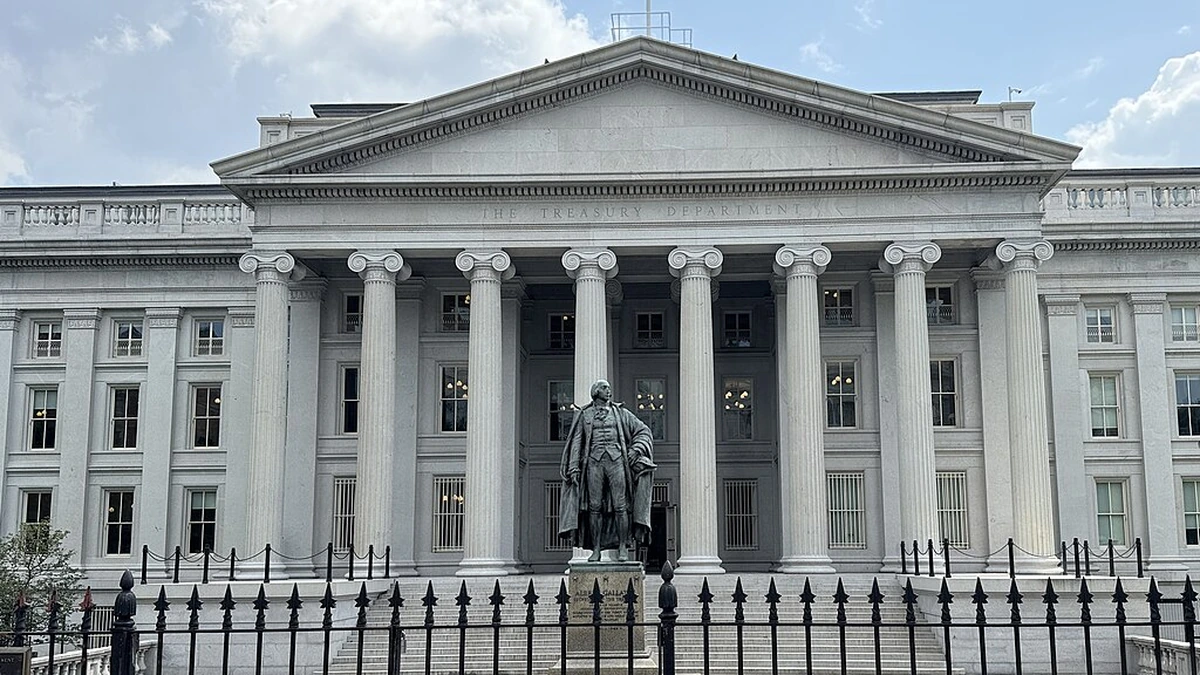
The U.S. Treasury has raised the initial interest rate on newly issued Series I savings bonds to 5.51%, giving purchasers from November 1, 2026, through April 30, 2027, a higher starting return than buyers received during the previous six-month issue period.
The annualized composite rate is up from 4.26% for bonds issued from May through October. The new rate consists of a 1.40% fixed component that stays with the bond and an inflation adjustment based on a 2.04% rise in the relevant consumer price index over six months. That inflation component will change, so a purchaser is not locking in a 5.51% annual return for the bond’s entire life.
The increase has two distinct consequences for savers. New buyers receive a higher first six months of interest, and the 1.40% fixed component gives this issue of I bonds a larger permanent return above the inflation adjustment than recent issues. Existing bondholders will receive the new inflation adjustment as their individual bonds reach their next six-month reset, but their original fixed rates will not change.
A 1.40% fixed rate changes the longer-term calculation
The fixed portion of an I bond is determined when the bond is issued. Treasury resets the fixed rate for new purchases in May and November, but it remains attached to each bond until redemption or final maturity, which can be as long as 30 years. The inflation portion, by contrast, changes every six months. Treasury details that distinction in its I bond interest-rate rules.
For bonds issued from May through October 2026, the fixed component was 0.90%. Raising it to 1.40% for the new issue period increases the permanent portion of the return by half a percentage point. Buyers of older bonds do not receive that adjustment simply because Treasury has announced a higher fixed rate for newly issued securities.
The distinction matters when inflation subsides. A bond with a 1.40% fixed rate retains that fixed component, subject to Treasury’s composite-rate calculation, even if subsequent inflation adjustments are much smaller. Someone holding an I bond issued when the fixed rate was zero has no fixed return to fall back on. The actual composite rate in either case can change as inflation rises or falls.
I bonds are not conventional fixed-rate certificates of deposit. The 5.51% figure describes an annualized rate that applies to the first six months of a newly issued bond, not a guaranteed yield for five, ten or thirty years. What stays constant is the 1.40% fixed rate, not the complete headline rate.
September inflation data explain the variable component
The inflation adjustment reflects the change in the non-seasonally adjusted Consumer Price Index for All Urban Consumers, or CPI-U, between March and September. The Bureau of Labor Statistics reported an index level of 336.940 for September 2026. Treasury’s earlier rate release recorded a March 2026 index level of 330.213. The difference represents an increase of roughly 2.04% over six months.
This measure is not the same as the 3.7% year-over-year inflation rate reported by BLS for September. I bonds use the specific six-month change between the two index readings to determine the semiannual inflation component. Treasury then annualizes that component and makes a small additional adjustment for the fixed rate.
With a 1.40% fixed rate and a 2.04% semiannual inflation rate, Treasury’s published formula produces a 5.51% composite rate after rounding. The inflation portion alone represents 4.08 percentage points on an annualized basis. An additional fraction of a percentage point arises from applying the fixed rate to the inflation adjustment.
The corresponding six-month inflation change used for the previous issue period was 1.67%. A higher inflation adjustment therefore accounts for most of the jump in the advertised composite rate, with the increase in the fixed component contributing the remainder. The total rate has risen 1.25 percentage points from the 4.26% available to new buyers during May through October.
Treasury does not apply the 5.51% rate to every I bond in circulation. A bond issued in a different period has its own fixed rate, and its six-month interest period begins according to its issue month. For example, a bond originally issued in June changes its inflation-linked rate in June and December, rather than automatically on every May 1 or November 1 announcement.
What buyers and existing owners should know
Series I bonds accrue interest monthly and compound semiannually. After six months, accrued interest is added to principal and the next six-month rate applies to that larger balance. The rate reset does not require an owner to buy a new bond, but the owner’s fixed component remains the one established at original issue.
For someone investing $10,000 in a new bond, a 5.51% annualized rate implies roughly $275 in interest over the initial six months before taking account of Treasury’s exact accrual and rounding conventions. It would be incorrect to multiply that initial six-month amount into a long-term earnings projection, because the inflation component will be reset for the following six-month period.
An older bond with a fixed rate of 0.90%, for example, would earn approximately 5.00% after its next reset using the new 2.04% semiannual inflation component. That differs from the 5.51% offered to new buyers because the older bond retains its original 0.90% fixed rate. It also illustrates why the announced headline rate should not be read as a universal rate for all I bond accounts.
The higher rate comes with restrictions that distinguish I bonds from money held in an ordinary bank savings account. Buyers must hold an I bond for at least 12 months, except in limited circumstances, and redemption before five years forfeits the most recent three months of interest. I bonds are designed to be held rather than traded; they cannot be sold on a secondary market to obtain cash early.
New purchases are electronic through TreasuryDirect. The minimum is $25, and an individual generally may buy up to $10,000 in electronic I bonds per calendar year. Treasury ended the option of obtaining new paper I bonds through federal income-tax refunds beginning in 2025. The purchase cap means the higher rate cannot necessarily be applied to an unlimited savings balance.
Interest is subject to federal income tax but exempt from state and local income taxes. Owners generally may choose to report interest annually or defer federal reporting until redemption or maturity. Some taxpayers may qualify for a federal tax exclusion when eligible bond proceeds are used for higher education, subject to the program’s rules and income limits.
For holders assessing whether to redeem an older issue and buy a new one, the comparison requires more than the advertised rates. A redemption penalty may reduce the benefit, an older bond could already carry an attractive fixed rate, and a new purchase must satisfy a fresh 12-month holding period. The annual purchase limit is another constraint.
The next scheduled reset for newly issued I bonds is tied to the May 2027 rate announcement and the inflation data available at that point. Their 1.40% fixed component will remain in place, but the composite rate for the following six months will depend on the next inflation reading.
More from Banking
Latest News
View all news- Virginia Restricts SNAP Spending on Soda and Certain Energy Drinks
- Texas Raises Assigned-Risk Auto Insurance Rates for Private and Commercial Vehicles
- HealthCare.gov Opens Enrollment for 2027 Health Insurance Coverage
- New Federal Rules Limit How Medical Billing Disputes Can Be Batched
- Federal Sentencing Guidelines Update Financial Penalties for Economic Crimes
