Bank of Japan Releases Governor Ueda’s Analysis of Japan’s Current Account Surplus
The BOJ governor says Japan's overseas investment income now offsets trade deficits, reflecting decades of corporate saving and restrained domestic investment.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy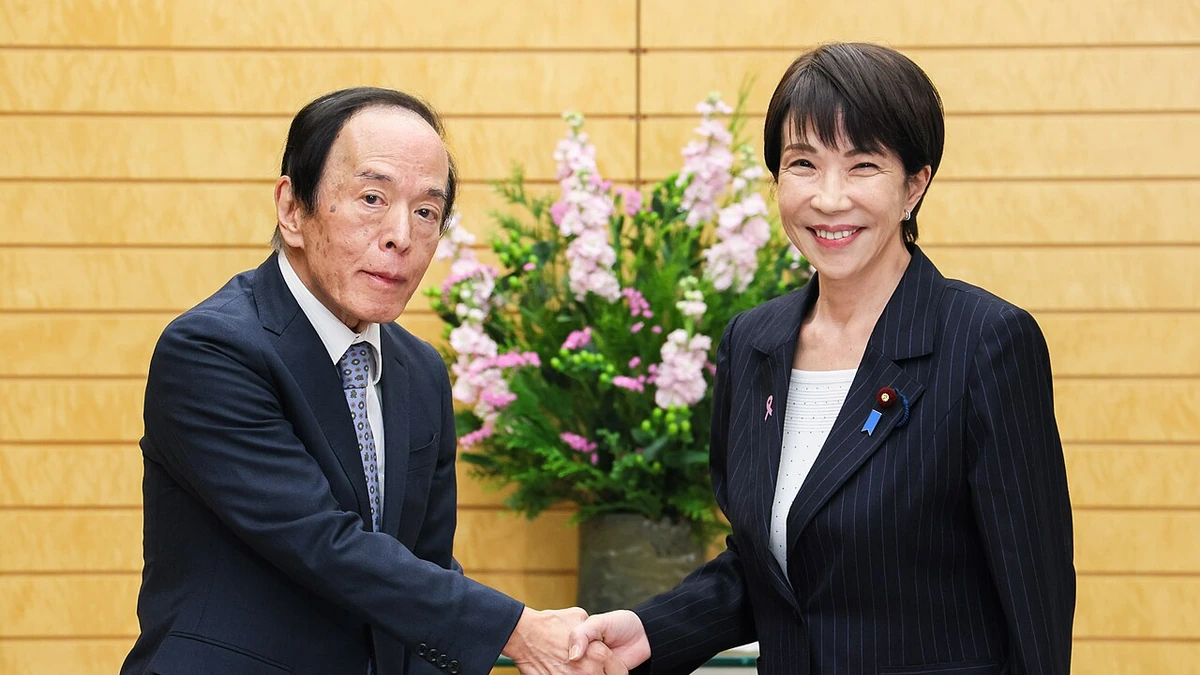
The Bank of Japan has published Governor Kazuo Ueda’s account of why the country continues to run a current account surplus despite a long decline in its goods trade balance. His explanation places Japanese companies’ saving and investment decisions, rather than exports alone, at the center of a change that has unfolded over several decades.
Speaking at the International Monetary Fund’s Michel Camdessus Central Banking Lecture on November 6, Ueda described an economy that increasingly earns income from businesses and assets overseas. Japan’s merchandise trade surplus exceeded 4% of gross domestic product in the mid-1980s, he said, but the goods balance has since turned negative. The primary income surplus, meanwhile, has grown to more than 6% of GDP.
The contrast helps explain why a country can buy more goods from abroad than it sells and still record a sizeable external surplus. In the speech released by the Bank of Japan on November 7, Ueda said the overall current account surplus had generally remained around 2% to 4% of GDP for much of the past four decades, even as the sources of that surplus changed.
Revised Ministry of Finance figures provide a more recent illustration. Japan recorded a current account surplus of roughly ¥32.2 trillion in calendar 2025, with a primary income surplus of about ¥41.8 trillion. Those figures appear in the ministry’s revised balance-of-payments data and differ from the lower preliminary totals released earlier in 2026. Income from overseas holdings was more than sufficient to offset deficits elsewhere in the current account.
Why Japanese companies became persistent net savers
The accounting behind a current account surplus is broader than a trade ledger. National saving must exceed domestic investment, with the difference reflected in a country’s external balance. For years, Japan’s household saving helped produce that excess, but an aging population gradually reduced the household sector’s contribution. Government budget deficits also worked in the opposite direction. The corporate sector came to fill the gap.
Ueda traced that change to the aftermath of Japan’s asset-price bubble. The yen’s appreciation following the 1985 Plaza Accord was accompanied by efforts to stimulate domestic demand, while an investment boom and steep increases in property and equity prices developed later in the decade. Once the bubble collapsed, companies were left with weaker asset values and debts that had not fallen alongside them. Cutting investment and paying down borrowings took priority over expansion.
The consequences lasted well beyond the initial crisis. Domestic business investment declined through the 1990s and into the following decade, and nonfinancial firms moved from net borrowing to net saving around the late 1990s. Rather than treating every improvement in their finances as a reason to build new capacity, businesses often held back. That left a large pool of corporate saving relative to investment, helping sustain Japan’s external surplus as household saving diminished.
This explanation is supported by the Bank of Japan’s earlier survey of corporate behavior. Conducted from late 2023 to early 2024, it received responses from 2,256 firms across different sizes and industries. Businesses described how the bubble’s collapse, the banking crisis and later economic shocks shaped their approach to borrowing and risk. Many came to value strong balance sheets and cash reserves, while weak expectations for domestic growth discouraged new projects.
The survey does not establish that every company followed the same path. Large manufacturers, smaller businesses and service providers faced different conditions. Its value for Ueda’s argument lies in showing that cautious investment behavior was not simply the result of a shortage of funds. In many cases, companies were able to save but saw insufficient reason to spend more inside Japan.
Overseas investments took a larger share of the surplus
Corporate deleveraging eventually eased. Ueda identified 2011 and 2012 as an important turning point, when domestic investment and borrowing began to recover but corporate saving remained high. An increasing portion of available capital went to foreign direct investment, including overseas operations and acquisitions, rather than being committed entirely to new plants and equipment at home.
The returns helped reinforce that preference. According to the governor’s presentation, returns on Japan’s outward direct investment remained above 8% for much of the period after the balance-sheet adjustment, even as returns on some portfolio assets weakened. From 2012 onward, direct investment became a more prominent channel for outward capital flows than portfolio investment, giving Japanese firms a larger operating presence in foreign markets.
That distinction matters when reading the balance-of-payments numbers. Primary income can include returns that Japanese companies earn through overseas subsidiaries, not just payments transferred back to bank accounts in Japan. Some of those profits are retained by foreign affiliates and reinvested locally. They still enter the international accounts as investment income and, through reinvested earnings, can be recorded as additional direct investment.
The revised 2025 figures show how large the difference between trading goods and earning investment income has become. The goods balance was a deficit of approximately ¥0.57 trillion and services added a deficit of about ¥3.44 trillion. Net primary income was far larger than those shortfalls. The overall surplus therefore should not be read as evidence that Japan’s factories still sell substantially more merchandise abroad than the country imports.
Ueda also used a historical comparison to explain the pattern. Britain built extensive overseas assets as its economy matured, allowing investment income to support its external position even after its trade balance weakened. Japan’s experience is not identical, but the parallel draws attention to accumulated foreign assets and the income they generate. An external surplus can survive even when the activities producing it look very different from those of an earlier era.
Domestic investment is recovering, but the outlook is unsettled
Population aging remains an important part of Japan’s economic story, although Ueda argued that demographics alone cannot explain the timing of the change in corporate behavior. A shrinking working-age population might be expected to restrict the supply of labor and encourage companies to shift production abroad. Yet Japan’s output gap was generally negative from 1993 through 2012, and unemployment remained relatively elevated by the country’s historical standards. The labor market was not consistently constrained in the way that a simple labor-shortage explanation would suggest.
He instead emphasized expectations about future demand. Companies anticipating a smaller domestic market could see fewer attractive projects at home, even before a lack of workers became an immediate operating problem. Employment was also supported over time by rising workforce participation among women and older people. Those developments complicate the idea that demographic aging directly and immediately forced Japanese businesses to invest abroad.
More recently, the direction of some investment decisions has shifted. In the central bank’s corporate survey, more than 70% of firms reported investing more actively in Japan during 2023 and 2024 than previously. Labor shortages were the most frequently cited reason, as businesses sought equipment and systems that could produce more with fewer available workers. Larger companies also identified projects involving digital technology, decarbonization and supply chains.
Ueda said domestic business fixed investment after the pandemic had surpassed its early-1990s peak. He also pointed to bank lending growth exceeding 5% at the time of his remarks, a pace he characterized as the fastest in about three decades apart from the exceptional support period in 2020. These signs suggest companies may be more willing to finance activity within Japan, although a rebound in investment does not by itself establish that the longstanding external surplus will disappear.
Higher domestic capital spending would absorb more corporate saving, potentially narrowing the gap that has supported the current account. Continued population aging could also reduce household saving further. Against those pressures stands Japan’s large stock of foreign investments, which can keep generating income regardless of whether the goods trade balance returns to surplus. Ueda’s analysis did not specify a date when these forces would outweigh one another or announce a change in monetary policy.
More from Banking
Latest News
View all news- Berkshire Hathaway Reports Lower Q3 Operating Earnings, $9.6 Billion in Share Buybacks
- $753 Million Los Angeles Port Bridge Project Begins as 16-Month Closure Takes Effect
- New Zealand Election Results Leave Economic and Tax Policy Outlook Uncertain
- Novo Nordisk Heart Drug Fails to Cut Cardiovascular Events in Full ZEUS Trial Results
- UK Announces New Satellite-Monitoring Trial Under £3 Billion Space Defence Programme