
Italy Sells €7.25 Billion in Government Bonds as Three- and Seven-Year Yields Fall
The Treasury sold the full amount offered across three BTP issues, with demand of about €11.38 billion and lower yields on its 2029 and 2033 maturities.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy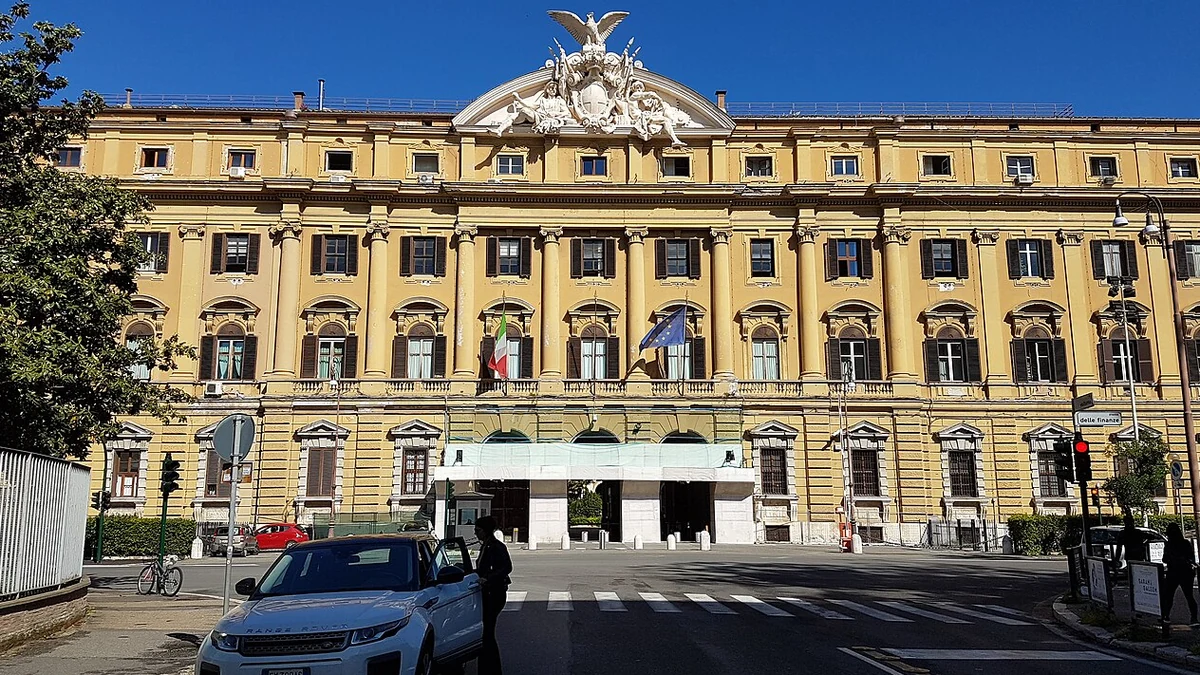
Italy sold €7.25 billion of government bonds on Thursday, November 12, with yields on its three-year and seven-year securities falling from the previous month’s auctions. The Treasury allotted the full amount available across three bond reopenings, including a long-dated green bond.
The three-year BTP cleared at a gross yield of 3.58%, down from 3.69% in October, while the seven-year issue yielded 4.04%, compared with roughly 4.24% at its previous sale. The reductions indicate that buyers accepted lower returns for these securities than they had at the earlier auctions. They do not, by themselves, establish a broader change in Italy’s borrowing outlook.
The results covered €2.5 billion of the shorter BTP, €3.25 billion of the seven-year security and €1.5 billion of a green BTP maturing in 2046. Total bids came to approximately €11.38 billion. The Bank of Italy’s official auction-results releases provide the primary record of the placements it conducts for the Ministry of Economy and Finance.
Demand exceeded the amount allocated for each of the three bonds. That gives the Treasury evidence of investor appetite at the auction prices, but it does not show that every investor who submitted a bid received the full amount requested, or that borrowing costs will continue to decline at later sales.
Three- and seven-year BTPs account for most of the borrowing
The Treasury allotted €2.5 billion of the three-year BTP, the upper end of its announced offering range. The bond carries a 3.00% annual coupon and matures on September 15, 2029. It was the ninth tranche of an existing issue rather than the launch of an entirely new bond, so the added securities share the same terms and maturity with bonds already outstanding.
Orders for that maturity totaled about €3.84 billion, producing a bid-to-cover ratio of approximately 1.54. This measure compares the volume investors requested with the volume issued. A ratio above one means bids exceeded supply, although demand should be interpreted alongside the yield and the price at which an auction clears.
The seven-year BTP accounted for the largest single allocation, at €3.25 billion. Its maturity is September 15, 2033, and its annual coupon is 3.35%. This was the seventh tranche of the security. The auction attracted just over €5 billion in bids, again corresponding to a coverage ratio close to 1.54.
Together, those two conventional BTPs raised €5.75 billion, almost four-fifths of Thursday’s total. They give the government financing across different repayment dates without concentrating the entire issue in one maturity. The two bonds also serve different investors: buyers of the seven-year security take on more exposure to changes in market interest rates before maturity than buyers of an otherwise comparable shorter-dated bond.
Reopening existing securities is a routine part of Italian debt management. It increases the outstanding amount of a bond that already trades in the market and can support liquidity by bringing additional supply into that issue. The number of tranches does not change the date on which the principal is due or the coupon rate written into the bond’s terms.
Lower auction yields ease the terms for the new supply
The three-year yield was 11 basis points below October’s 3.69% result. The seven-year yield fell by approximately 20 basis points from about 4.24% to 4.04%. A basis point is one-hundredth of a percentage point, so these changes are modest in absolute terms but relevant when applied to substantial government borrowing over several years.
A bond’s coupon and its yield are not the same thing. The 2029 BTP pays a fixed 3.00% coupon on its nominal value, yet investors accepted it at a price consistent with a 3.58% gross yield. Similarly, the 2033 bond has a 3.35% coupon but a 4.04% auction yield. When a fixed-coupon bond is sold below its face value, the discount contributes to the return an investor can earn by holding it until maturity, assuming the issuer pays as promised.
This distinction matters for Italy’s financing costs. The auction yield describes the market terms on the additional bonds sold on November 12, not a repricing of all Italian government debt already outstanding. Existing fixed-rate obligations continue to carry their contracted payments. Changes in funding costs feed into the government’s overall interest bill gradually as debt matures and new issuance replaces it.
The Bank of Italy uses a uniform-price, or marginal, auction method for BTPs, as distinct from the competitive auction method applied to Treasury bills. Successful bidders in a BTP auction are allocated securities at a common accepted price. That process produces the published auction yield and allows investors to compare the result with other sales of the same security.
Thursday’s decline in the two yields is a comparison between particular auction dates, not proof that all Italian bond yields moved lower throughout the trading day. Secondary-market prices can fluctuate before and after an auction, and differences in the securities offered can complicate comparisons across maturities. The clearest conclusion from these results is that the Treasury raised the new three- and seven-year funds on lower gross-yield terms than at their previous sales.
Green bond attracts the highest coverage ratio
The third security was a BTP Green maturing on April 30, 2046. Italy allotted €1.5 billion, the top of the amount offered, against roughly €2.54 billion in bids. Its bid-to-cover ratio of about 1.69 exceeded the ratios for both conventional BTPs, giving the long-dated issue the strongest relative demand in Thursday’s auction.
The green BTP carries a 4.10% annual coupon and was reopened for a third tranche. Its much longer maturity means investors face a different interest-rate exposure from those buying the 2029 or 2033 securities. An attractive coverage ratio does not necessarily mean the longer bond was cheaper for the Treasury to issue; coupon rates, market prices and remaining maturities must be assessed together.
Italy’s green sovereign bonds are linked to qualifying environmental expenditures in the state budget. The Ministry of Economy and Finance’s Green Bond Framework describes eligible spending categories, including energy efficiency, low-emission transport, renewable energy and protection of the natural environment. These requirements distinguish how the proceeds are accounted for, rather than creating a separate claim on the projects for bondholders.
Under that framework, green-bond proceeds enter the Treasury’s general cash account while an accounting process tracks eligible expenditure against the amount raised. Investors therefore hold an obligation of the Italian state, not ownership in a particular energy or transport project. The framework also provides for reporting on the allocation and impact of qualifying spending.
Adding a green bond to the November sale broadened the range of maturities being offered, from just under three years to nearly two decades. For the Treasury, the result was €7.25 billion of funding at the maximum amounts set for all three issues. For investors assessing the auction, the more informative figures are the separate yields, bids and maturity dates rather than the aggregate total alone.
The scheduled settlement date for the three placements is November 16, when the newly allotted securities are due to be delivered and paid for. The next comparison for Italy’s shorter BTP yields will come from later auctions of those maturities, when prevailing market prices and investor demand will determine the terms of any additional borrowing.
More from Investing
Latest News
View all news- Nvidia Announces Jensen Huang’s Departure, Names Colette Kress Interim CEO
- India’s Inflation Hits 6.09% in October, Breaching RBI’s Upper Tolerance Limit
- U.S. Weekly Jobless Claims Rise to 200,000 as Labor Market Remains Resilient
- U.S. Existing-Home Sales Plunge 5.5% to Lowest Level Since 2010
- Chicago Fed Releases New Reading on U.S. Financial Conditions
