Fed Governor Barr Warns AI Could Widen Wealth Inequality
Barr cited concentrated investment ownership and a declining labor share as risks, while acknowledging that widely available AI could benefit workers and smaller firms.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy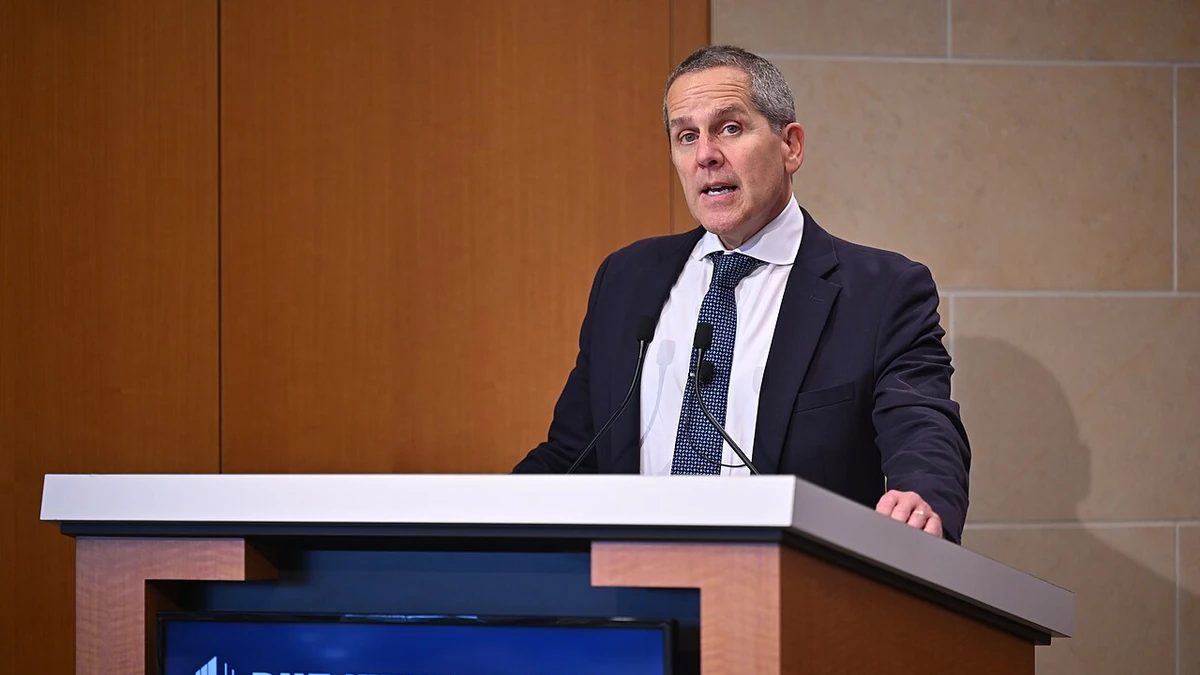
Federal Reserve Governor Michael S. Barr warned Thursday that artificial intelligence could deepen wealth inequality in the United States if the gains from the technology flow mainly to a small number of dominant companies and their investors. He also urged preparation for potentially serious disruptions to employment if AI replaces workers faster than they can move into new jobs.
Barr did not say that outcome was inevitable. Speaking about AI and inequality in remarks prepared for Yale University on November 12, he described two very different possibilities: a market in which affordable AI tools raise productivity across the economy, or one in which control of advanced technology allows a few companies to capture an outsized share of its financial rewards.
The warning draws on an already unequal distribution of American wealth. In his remarks published by the Federal Reserve, Barr used newly released household survey results and the long-term decline in labor’s share of national income to explain why the ownership of AI businesses could matter as much as the technology’s effect on individual jobs.
Existing wealth concentration could magnify AI gains
The wealthiest 10% of U.S. households own nearly three-fourths of the country’s wealth, according to the Fed’s 2025 Survey of Consumer Finances, which was published in October. The top 1% hold about one-third, while the entire bottom half of households hold just over 2%. Those figures describe an existing wealth gap, not an increase caused by artificial intelligence.
Ownership matters because returns from a successful technology can arrive through higher share prices, business profits and private investments rather than wages. Barr said capital income provides much of the income of the wealthiest households, whereas middle-income families depend primarily on paychecks. A surge in the value of a concentrated group of AI companies could therefore reward households that already own substantial financial assets more than those without meaningful investments.
The Fed’s latest survey also illustrates how unevenly stock ownership is distributed. Households ranked between the 50th and 90th percentiles of wealth own only 17% of publicly traded stocks by value, even though roughly three-fourths of that group own stocks, mostly through retirement accounts. More people participating in the market does not mean investment gains are divided evenly. The dollar amounts held by the wealthiest families remain much larger.
The difference is visible in broader measures of household finances. The 2025 survey put median family net worth at about $215,900, compared with mean net worth of $1.24 million. The mean is far higher because very large fortunes influence an average much more than a midpoint. The survey does not tell researchers precisely who will profit from AI, but it establishes why additional gains concentrated among asset owners could widen an already substantial gap.
A record-low labor share adds to the concern
Barr linked the inequality question to a separate measure: how much national income goes to workers rather than owners of capital. The labor share stood at 52.8% in the second quarter of 2026, a record low on the measure cited in his speech. In the decades after World War II, it had generally been between 60% and 65%. The decline began long before the current AI boom and cannot be attributed to AI alone.
He identified several forces behind that longer trend, including technological changes that replace some tasks, greater concentration of economic activity among large firms, and reduced bargaining power for employees. Measurement issues can affect the precise split between labor and capital income, Barr acknowledged, but he said the broader downward movement remains clear even after adjustments.
Advanced AI could intensify those forces if it allows businesses to produce more with relatively fewer workers, increasing profits without comparable wage growth. An investment-heavy industry also rewards owners of the computing facilities, technology and intellectual property behind the systems. That possibility is central to Barr’s warning: productivity gains can raise total economic output without ensuring the people doing the work receive a proportionate share.
Market structure may be just as important as automation. Leading AI developers and large cloud-computing companies have advantages in data, computing capacity and the resources needed to improve models. Barr raised the possibility that those advantages could allow a limited group of companies to dominate the market, build market power and accumulate substantial returns for shareholders and executives. Smaller firms might then struggle to access tools on comparable terms, leaving their workers with fewer productivity benefits.
That is a scenario, not a finding that the AI industry has already reached such an outcome. Barr also pointed to active competition among developers and the prospect that smaller, less expensive models could meet many businesses’ needs. If AI tools become broadly available, companies without the resources to develop their own frontier models could still use the technology to improve services, make employees more productive and compete with larger rivals.
Early employment effects are mixed, and timing matters
The labor-market evidence so far does not establish widespread displacement from AI. Barr said there has been relatively little worker replacement to date, alongside evidence that the technology is helping some employees become more productive, supporting demand in certain areas and creating new occupations. He nevertheless pointed to emerging signs of substitution in some sectors, particularly affecting younger and less-experienced workers.
Workers whose duties involve routine, well-defined tasks may be more exposed where software can produce measurable results with limited supervision. Jobs requiring judgment, managing relationships or overseeing complex work may instead gain from AI assistance. These distinctions concern the nature of tasks, not a firm prediction that particular occupations will disappear. Many jobs contain work that could be automated as well as responsibilities that are harder to replace.
The speed of adoption could determine how painful the transition becomes. A gradual shift would give workers and employers more time to develop new skills and reorganize jobs. Rapid deployment could leave displaced employees searching for opportunities before training programs or expanding industries can absorb them. Barr called for society to consider investment in worker training, new job creation and efforts to connect people with emerging employment opportunities.
There is also a more favorable path for income distribution. Widely accessible AI could help smaller businesses perform tasks that previously required costly expertise, creating room for growth outside the largest technology companies. Employees who use the tools to increase their output could benefit if competition for their skills and effective bargaining translate productivity into stronger pay. Barr’s argument was that such an outcome is possible, not assured.
His remarks were an assessment of economic risks rather than an announcement of a Federal Reserve interest-rate decision or a specific new regulatory proposal. The central uncertainty remains the division of AI-generated gains between business owners and workers as adoption spreads. Barr said the technology is still at a relatively early stage, which is why he considers preparation for labor-market disruption and concentrated economic power important now rather than after those effects become entrenched.
More News
Latest News
View all news- National Vision More Than Doubles Adjusted Earnings Per Share but Cuts Sales Outlook
- U.S. Existing-Home Sales Plunge 5.5% to Lowest Level Since 2010
- Chicago Fed Releases New Reading on U.S. Financial Conditions
- Canadian Building Permits Fall 4.1% as Residential Construction Intentions Weaken
- Dutch Business Bankruptcies Surge 27% in October, Official Data Shows