Bundesbank Says German Economy Is Losing Momentum Temporarily in Third Quarter
Low Rhine water, weaker exports and temporary industrial disruptions are weighing on activity, but the central bank expects growth to strengthen again in the fourth quarter.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy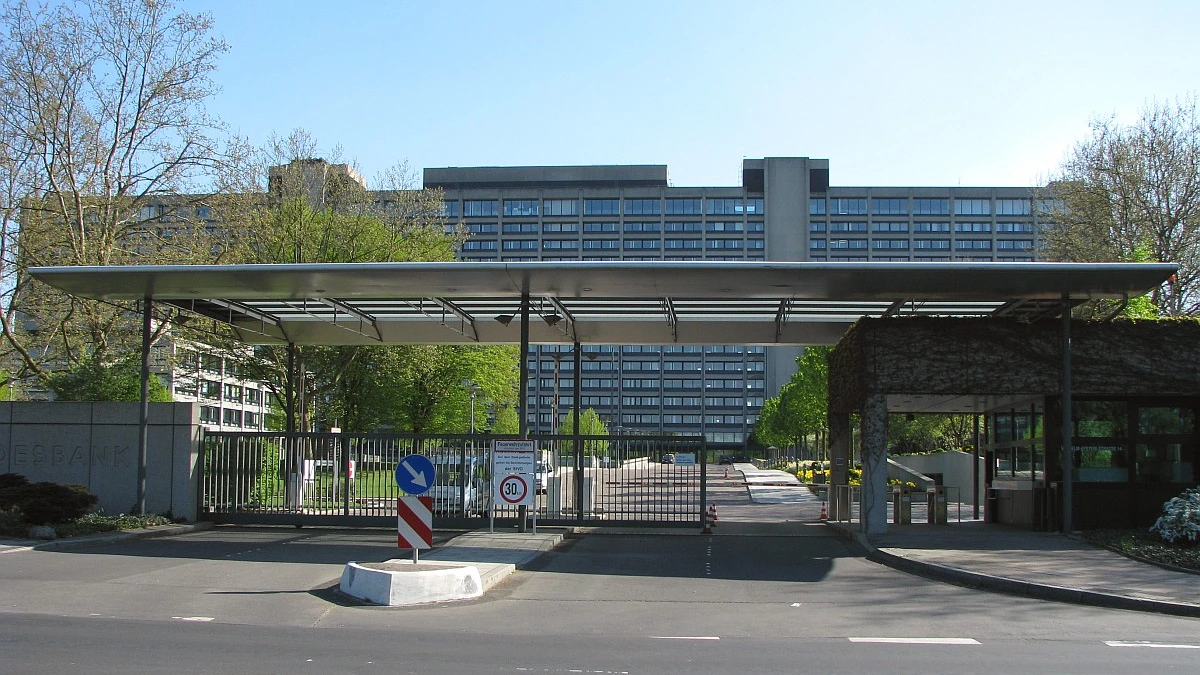
Germany’s economy is likely to lose momentum temporarily in the third quarter of 2026, with real gross domestic product expanding only slightly after stronger growth earlier in the year, the Deutsche Bundesbank said Monday.
That softer quarter, in the central bank’s view, does not mark a break from the recovery path. Much of the slowdown reflects temporary strains, led by exceptionally low water levels on the Rhine, weaker industrial output, a smaller contribution from exports and subdued consumer spending. Growth should strengthen again in the fourth quarter if those pressures ease, although the outlook also depends on developments in the Middle East and the return of more normal water levels on major waterways.
The expected slowdown follows two quarters of expansion. Germany’s price, seasonally and calendar adjusted GDP rose 0.4% in the first quarter and 0.3% in the second quarter, according to detailed second-quarter figures from the Federal Statistical Office. Destatis revised the second-quarter increase up from an earlier estimate of 0.2%, with exports making an important contribution to growth.
Low Rhine water and factory disruptions weigh on industry
Industry provides the clearest evidence of the third-quarter loss of momentum. In its September Monthly Report commentary, the Bundesbank said low Rhine water levels that emerged in July disrupted transport on major rivers and sharply increased freight costs. Pressure was especially visible in energy-intensive industries such as chemicals, metals, and the production of coke and refined petroleum products, which were also dealing with high fossil-fuel prices.
Official production data reinforce that picture. German industrial production fell 1.1% in July from June after seasonal and calendar adjustment. Production in industry excluding energy and construction declined 2.2%, while output in energy-intensive industrial branches fell 1.7%. Automotive production recorded a particularly sharp 9.2% monthly drop, partly reflecting a multi-week shutdown at a factory that was being converted to produce electric vehicles.
That automotive disruption should fade as production normalizes, but low water levels remained a drag through August. The Bundesbank said the transport problems were likely to weigh on output and foreign trade over the remainder of the quarter as well. Destatis separately reported that the value of German goods exports fell 0.8% in July from June on a calendar and seasonally adjusted basis. Exports are also expected to contribute less to third-quarter growth than they did earlier in the year.
Consumer demand is not providing a strong offset. Private consumption is likely to remain subdued, according to the Bundesbank, with high energy prices reducing household purchasing power and spending capacity for other goods. Higher energy costs are also raising input costs for businesses, adding another headwind even though several of the most visible industrial drags are temporary.
Orders offer a more mixed signal beneath the headline
The outlook for German industry is not uniformly weak. New manufacturing orders rose 2.5% in July from the previous month, but the headline increase was heavily influenced by large orders. Destatis said orders excluding large-scale items fell 1.4%, and the Bundesbank noted that this measure declined for a fourth consecutive month.
Other transport equipment, a category that includes aircraft, ships, trains and military vehicles, accounted for much of the July strength. Orders in that segment more than doubled from the previous month after seasonal and calendar adjustment. Automotive orders, by contrast, fell 12.5%. Those figures show why the 2.5% headline gain does not amount to evidence of a broad-based industrial rebound.
Even so, the Bundesbank sees reasons to expect improvement once the temporary disruptions pass. Manufacturing surveys showed a better order situation in August and extended production plans, while export expectations improved sharply. In the central bank’s assessment, underlying industrial demand still has an upward tendency, creating room for output to return to the firmer pace seen before the third-quarter disruptions.
Construction is another area offering some support. Output increased across construction sectors in July and returned to the second-quarter average after a weak June. Bundesbank economists expect the recovery to continue, with civil engineering benefiting from increased federal infrastructure investment. Housing construction remains more difficult because high financing rates and rising building costs continue to restrain demand.
A fourth-quarter pickup is expected, but the risks have not disappeared
For the fourth quarter, the central case is that German growth strengthens again as low-water effects and industrial one-offs fade. That assessment frames the current loss of momentum as a pause within a recovery rather than the start of a renewed downturn. It is still a conditional forecast, not a statement that the third-quarter weakness will automatically reverse.
Energy is one of the main uncertainties. European energy commodity prices rose sharply again in August and September as the Middle East conflict intensified, the Bundesbank said. Higher prices for gas, electricity and petroleum products can squeeze household purchasing power while raising production and transport costs for companies. German inflation as measured by the Harmonised Index of Consumer Prices increased to 2.9% in August from 2.8% in July, while the core rate excluding energy and food remained at 2.6%.
Labor market conditions also point to a recovery that is still incomplete. Employment fell by 14,000 in July on a seasonally adjusted basis to 45.66 million people, and registered unemployment stood at a seasonally adjusted 2.996 million in August, with the unemployment rate unchanged at 6.4%. At the same time, forward-looking employment indicators showed early signs of stabilization, including a rise in new vacancies subject to social security contributions to their highest level since the beginning of 2024.
For the near-term outlook, the key distinction is between temporary supply and production disruptions and more persistent weaknesses in demand. Normalizing river levels and the end of factory shutdown effects would remove some of the third-quarter drag. A durable acceleration would also need exports, investment and household demand to hold up against high energy costs and financing conditions. The Bundesbank’s September assessment therefore leaves Germany on a recovery path, but with less momentum in the current quarter and a fourth-quarter pickup that remains sensitive to both domestic constraints and external shocks.
More News
Latest News
View all news- Priority Technology to Go Private in $1.6 Billion Deal Led by CEO Thomas Priore
- Microchip Technology Completes Hailo Acquisition to Expand Edge AI Portfolio
- Clearwater Paper Refinances Debt With $275 Million Term Loan and New Revolver
- Strive Buys 1,355 More Bitcoin, Raising Holdings to 26,355 BTC
- UK Help to Save Bonus Payments Pass £300 Million as Government Plans Wider Eligibility