
Japan Household Spending Falls 3.1% in Real Terms in August
A ninth straight annual decline masked a slight monthly rise, while workers’ household incomes fell after inflation despite stronger payroll figures.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy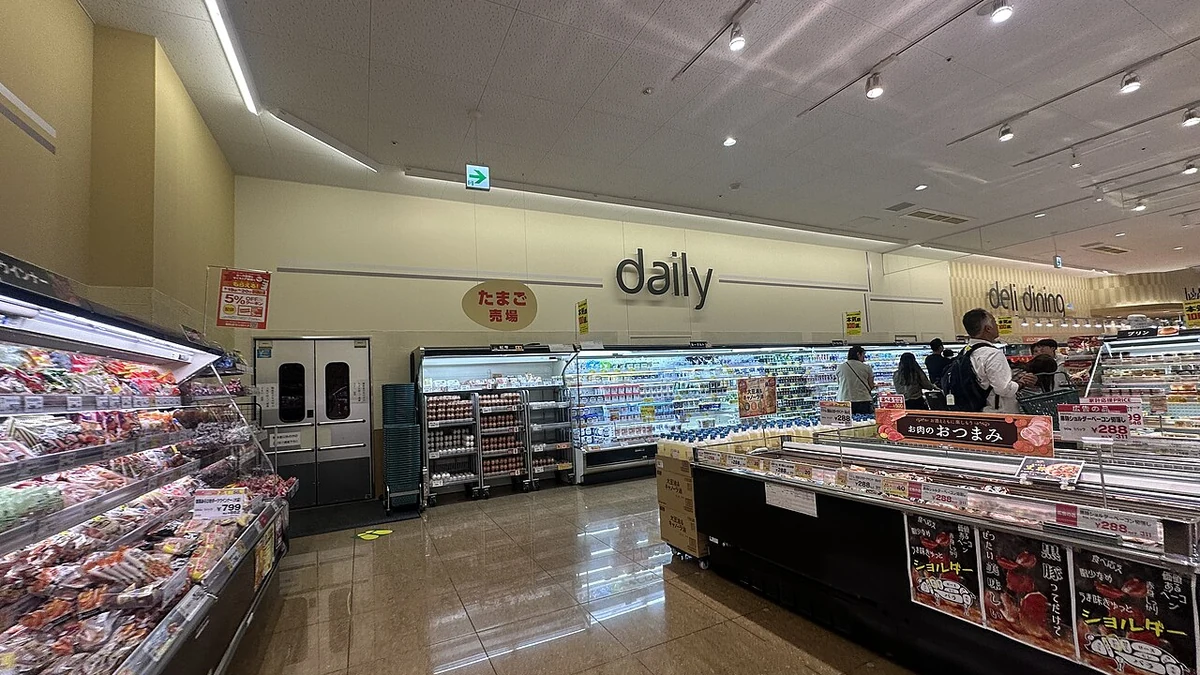
Japanese household spending fell 3.1% in real terms in August from a year earlier, extending a run of annual declines to nine months even as some wage indicators have improved. Households with two or more people spent an average of ¥310,975 during the month, Japan’s Statistics Bureau said Friday, October 9.
The decrease was smaller than July’s 3.6% year-over-year drop. Spending also edged up 0.1% from July on a seasonally adjusted, inflation-adjusted basis, following a 0.5% monthly increase in July. Those gains are modest beside the prolonged annual contraction, which shows that households were still purchasing less than they had a year earlier.
In the Family Income and Expenditure Survey, spending declined 1.0% when measured in nominal yen. The steeper 3.1% real decline reflects the difference made by adjusting for changes in prices. The report covers two-or-more-person households, rather than all Japanese households, and its monthly figures are not interchangeable with national consumer spending in gross domestic product.
The annual fall was less severe than the 3.6% decrease expected in a Reuters survey of economists. That narrower-than-forecast contraction provides some context for the release, but the stronger reading relative to expectations does not erase the weakness visible across most spending categories.
Food, clothing and household goods dragged on spending
The pullback reached items that families buy regularly as well as expenses they can more easily postpone. Real spending on food declined 1.4% from August 2025, with the average two-or-more-person household allocating ¥97,037 to the category. Food accounted for roughly 31% of the month’s consumption budget, so even a comparatively small fall in its inflation-adjusted spending matters to the overall result.
Utilities, which include electricity, gas and water, registered a 5.2% real decline, and spending on housing fell 5.8%. Those movements should not automatically be interpreted as equivalent changes in household need or living standards. Utility bills can be influenced by weather and public support measures, while housing expenditure can vary sharply with maintenance and repair payments.
Several categories associated with purchases that can be deferred were weaker. Spending on clothing and footwear dropped 8.7% in real terms, furniture and household goods fell 6.3%, and culture and recreation declined 4.3%. Education spending was down 12.3%, although education represented a much smaller share of the average household budget than food or transportation.
Transportation and communications was the only one of the ten main categories to register a real increase, rising 0.2% from a year earlier. That small gain was not enough to offset losses elsewhere. The broad pattern shows why the headline decline cannot be explained by one unusually weak purchase category, even though some spending items, including vehicles and home repairs, can vary considerably from month to month.
The split between categories also makes the nominal and real numbers important to read separately. A household may spend much the same number of yen at the supermarket but take home fewer goods if prices are higher. Conversely, lower utility spending can reflect price changes or usage patterns, not necessarily households deliberately cutting essential consumption. The survey records the outcome, rather than identifying one cause for every category’s movement.
Worker-household income fell after inflation
The income side of the survey points to a squeeze that headline wage growth alone does not capture. Among two-or-more-person households classified as workers’ households, average monthly income was ¥616,704 in August. That was 1.3% higher in nominal terms than a year earlier but 0.9% lower in real terms under the survey’s principal inflation adjustment.
The income figure is a household average, not the pay of an individual employee. It includes earnings received by household members as well as other forms of income, and it can be affected by the timing of bonuses or changes in the makeup of surveyed households. It therefore measures something different from the pay earned by an individual working at a business.
That distinction matters because Japan’s Ministry of Health, Labour and Welfare reported a 1.5% rise in real cash earnings per worker in August, its eighth consecutive annual increase. Average nominal cash earnings rose 3.8% to ¥311,364 in the ministry’s separate employer-based survey. The two sets of numbers are not inherently contradictory: they cover different populations, use different units of measurement and are subject to different influences.
Employees receiving pay rises may be better placed to spend, but pensioners and households without the same wage gains will not necessarily share that improvement. Nor does an increase in average earnings tell policymakers how much additional income households will choose to spend rather than save. Friday’s data show that stronger aggregate pay indicators have not yet been accompanied by a clear, sustained recovery in the household spending measure.
Price pressures remain part of that picture. Japan’s national consumer price index rose 1.9% in August from a year earlier, according to a separate Statistics Bureau release, while the index excluding fresh food increased 1.7%. Inflation was slower than in some earlier periods, but prices were still rising. The particular inflation measures used to calculate real wages, real household income and real consumption are not always identical, so their percentage changes should not be treated as a single accounting identity.
A mixed signal ahead of the Bank of Japan’s next decision
The weak household figures sit beside a more constructive assessment from the central bank. In its October 8 regional economic report, the Bank of Japan said all nine of its regions were recovering or picking up, although some continued to show weaknesses. Regional business reports and the household budget survey capture different aspects of activity, allowing both assessments to be true at the same time.
The contrast presents a policy challenge. More durable consumer demand would make it easier to judge whether wage increases are supporting spending and whether the economy can absorb higher borrowing costs. Persistent annual declines in household purchases point to caution, even when employment conditions and some wage measures look firmer. A single monthly release, however, cannot establish the timing or direction of a central-bank decision.
The modest 0.1% seasonally adjusted gain in August does not amount to a sharp turn in momentum. July’s annual decline was deeper, and the latest increase follows a volatile sequence of monthly moves. Officials will need to distinguish short-lived changes in purchases from a persistent improvement in household purchasing power and willingness to spend.
The Bank of Japan is scheduled to meet on October 29 and 30 and publish its updated outlook on October 30. The Statistics Bureau has scheduled September household spending data, alongside the July-to-September quarterly figures, for November 10. That later release will offer a fuller view of whether August’s smaller annual decline developed into a meaningful improvement in consumption.
More News
Latest News
View all news- Singapore Announces Haze-Related Healthcare Subsidies Starting October 12
- New Zealand’s ACT Party Proposes NZ$12.4 Billion Cut to 2031 Debt Forecast
- French Finance Minister Seeks to Avoid Budget Ordinances Amid Deficit Pressure
- Florida Renters Insurance Rate Cut Takes Effect for American Modern Policies
- Canada’s New Employment Insurance Eligibility Rules Take Effect October 11
