
TJX Reports 4% Comparable-Sales Growth and $1.34 in Adjusted Quarterly Earnings Per Share
The off-price retailer reported $15.95 billion in quarterly revenue and lifted the lower end of its full-year adjusted earnings outlook, with HomeGoods and international stores leading sales growth.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy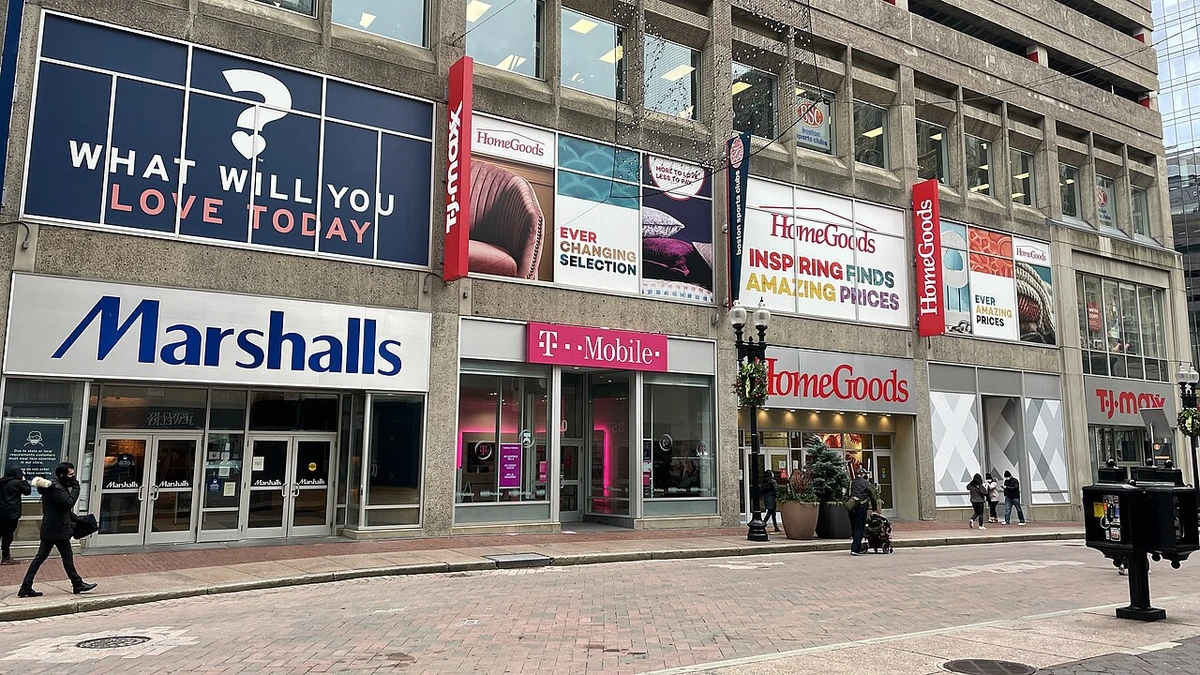
The TJX Companies reported a 4% increase in comparable sales and adjusted diluted earnings of $1.34 per share for its fiscal third quarter, as stronger results at HomeGoods and its international businesses helped offset slower growth at the company’s largest U.S. division. The off-price retailer, which operates T.J. Maxx, Marshalls and other chains, released the results Wednesday for the quarter ended October 31, 2026.
Net sales rose 6% to $15.95 billion from $15.12 billion a year earlier. Net income increased to $1.54 billion from $1.44 billion, with reported diluted earnings rising 9% to $1.39 per share. The reported figure included a net $0.05-per-share benefit related to refunds of previously paid tariffs. Excluding that benefit, adjusted diluted earnings grew 5% from the prior-year quarter.
Comparable sales growth was slightly below the 5% recorded a year earlier, but exceeded TJX’s plan for the latest quarter. The company also said both reported and adjusted pretax profit margins and diluted earnings came in above its internal expectations. The figures are detailed in its earnings release furnished to the U.S. Securities and Exchange Commission.
HomeGoods and overseas divisions lead comparable-sales growth
Marmaxx, the U.S. division that includes T.J. Maxx, Marshalls and Sierra, posted a 2% comparable-sales increase, down from 6% growth in the year-earlier period. Its net sales reached $9.33 billion, up 3% from $9.04 billion. That makes it by far the largest of TJX’s reported divisions, so a relatively modest change in its sales trend carries weight in the consolidated result.
HomeGoods, which includes the HomeGoods and Homesense chains in the United States, delivered 5% comparable-sales growth, matching its increase a year earlier. The division’s net sales advanced 8% to $2.74 billion. Its performance helped lift the consolidated comparable-sales figure above the pace at Marmaxx, despite HomeGoods being a much smaller part of the business.
TJX Canada reported 6% comparable-sales growth and net sales of $1.61 billion, an 8% increase on a reported basis. The company’s European and Australian businesses recorded 8% comparable-sales growth, compared with 3% a year ago, and net sales rose 11% to $2.28 billion. On a constant-currency basis, sales growth was 9% in Canada and 12% internationally, underscoring the distinction between local operating performance and reported dollar revenue.
The mix of results matters because TJX’s total sales growth does not measure the same thing as comparable sales. Revenue reflects the entire store network and foreign-currency effects, while the comparable-sales metric tracks performance at eligible established stores and related businesses. During the quarter, TJX added a net 64 stores, bringing its worldwide total to 5,349. Total selling square footage grew 1.2% from the previous quarter.
Chief Executive Officer Ernie Herrman said sales and profitability topped the company’s plans and pointed to continued strength at HomeGoods, Canada and international operations. He also said he expects Marmaxx to improve further in the fourth quarter, an outlook that has yet to be tested by the holiday selling season.
Tariff refunds explain the difference between reported and adjusted profit
The $0.05 difference between reported and adjusted diluted earnings is an important feature of this quarter’s results. TJX received $132 million in refunds of tariffs it had previously paid under the International Emergency Economic Powers Act. Related incremental accruals for year-end incentive compensation and discretionary bonuses totaled $55 million, leaving a net pretax benefit of $77 million. The company’s adjusted figures remove that net effect to present results without the refund-related benefit.
Reported pretax profit margin reached 13.0%, an increase of 0.3 percentage points from a year earlier. On the company’s adjusted basis, pretax margin was 12.5%, down 0.2 percentage points from the prior-year period, although still ahead of plan. The different directions show why the reported margin improvement should not be interpreted as an equivalent increase in underlying profitability.
The same distinction appears in gross profit. TJX reported a 32.9% gross margin, versus an adjusted gross margin of 32.1% after accounting for the specified tariff-related benefit. Adjusted selling, general and administrative costs represented 19.8% of sales, compared with a reported 20.1%, because the compensation-related accruals affect the expense calculation. These adjustments are specific to the tariff refunds and associated costs, rather than a broad restatement of the quarter.
For the first nine months of fiscal 2027, net sales totaled $45.46 billion, up 7%, and comparable sales increased 4%. TJX received $463 million in tariff refunds over that period and recorded $167 million in related incremental compensation accruals, for a net pretax benefit of $296 million. Nine-month reported diluted earnings were $3.94 per share, while adjusted diluted earnings were $3.75, up 14% from the comparable prior-year figure. This longer view also shows that the refund effect was not confined to the latest quarter.
Full-year earnings range edges higher before the holiday quarter
Following the results, TJX now expects comparable sales to grow 4% for fiscal 2027, rather than the previous range of 3% to 4%. It increased the lower end of its adjusted diluted earnings outlook to $5.17 per share from $5.15, while retaining the $5.20 upper end. The reported earnings forecast is now $5.33 to $5.36 per share, compared with $5.31 to $5.36 previously. The company continues to expect a full-year adjusted pretax margin of 12.0% to 12.1%.
For the fourth quarter, which includes the crucial holiday shopping period, management plans for a 2% to 3% comparable-sales increase. It projects adjusted diluted earnings of $1.42 to $1.45 per share and reported diluted earnings of $1.39 to $1.42. TJX does not expect additional tariff refunds during the quarter, but it anticipates about $0.03 per share of expense from compensation accruals associated with refunds already received. Its updated profit outlook also incorporates higher fuel costs than previously assumed.
Herrman said unusually warm weather in the United States and Canada had weighed on demand in some merchandise categories. Management expects sales momentum to strengthen as the holiday season progresses, although that expectation depends on consumer demand and the timing of colder weather. The improvement forecast for Marmaxx is particularly relevant given the division’s size and its slower comparable-sales growth in the third quarter.
TJX ended the quarter with $9.8 billion in inventory, up from $9.4 billion a year earlier. The company said inventory per store was flat on a reported and constant-currency basis after excluding goods in transit and e-commerce inventory. That detail provides more context than the companywide dollar increase alone, given the expansion of the store network. Management said merchandise availability remains favorable ahead of holiday shopping.
Cash generation also supported shareholder distributions. TJX reported $1.7 billion of operating cash flow in the quarter and ended October with $4.6 billion in cash. It repurchased $1.0 billion of shares and paid $529 million in dividends during the period, bringing combined shareholder returns to about $1.5 billion. The company expects roughly $3.0 billion in repurchases across the full fiscal year, subject to adjustment.
The next scheduled earnings update will provide a clearer measure of whether the expected improvement at Marmaxx and stronger holiday demand materialize. TJX’s official reporting calendar currently lists February 24, 2027 as the expected date for its fourth-quarter results; the company notes that scheduled release dates can change.
More from Investing
Latest News
View all news- U.S.-China Congressional Commission Posts 2026 Report Examining Trade, Commodities and AI
- U.S. Mortgage Applications Fall 2.3% as 30-Year Rate Rises to 7.35%
- U.S. Housing Starts Rise 9.9% in October Even as Building Permits Drop 7.4%
- Infinity Natural Resources Signs Reorganization Agreement, Targets December 1 Closing
- U.S. Outdoor Recreation Economy Reaches $704.2 Billion, New Federal Data Show
