
U.S. Mortgage Applications Fall 2.3% as 30-Year Rate Rises to 7.35%
Higher borrowing costs cooled mortgage demand in the latest MBA survey, with both purchase and refinance applications declining as the average 30-year rate climbed to 7.35%.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy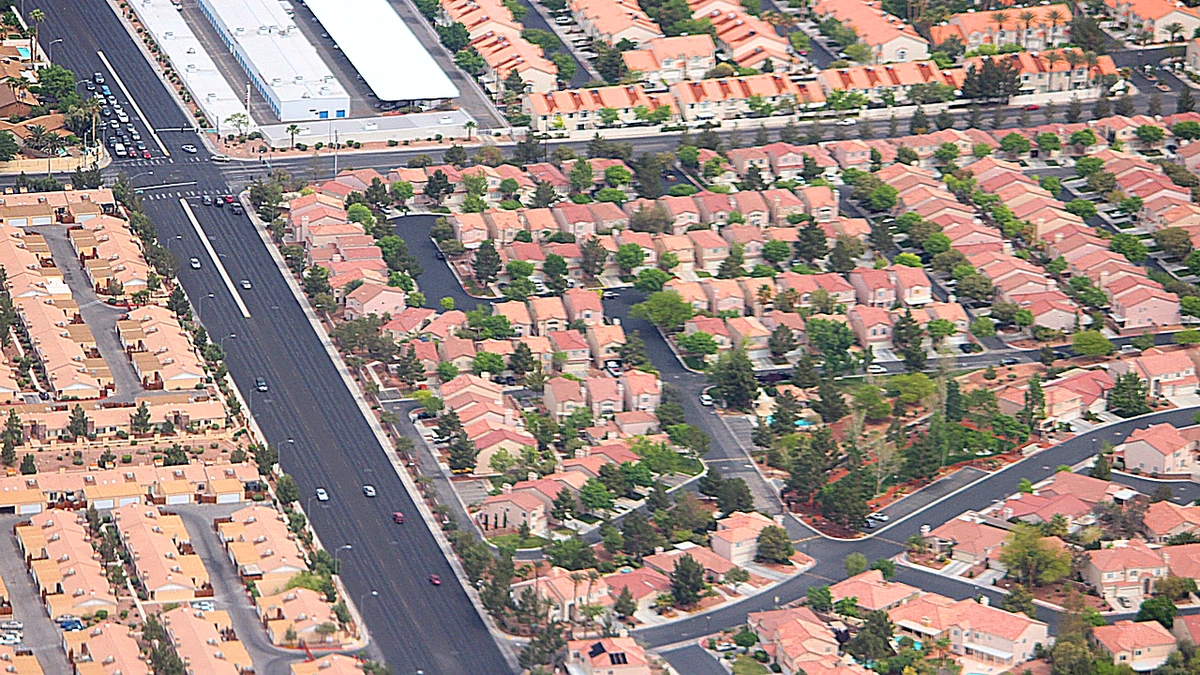
U.S. mortgage applications fell 2.3% last week as borrowing costs moved higher again, reversing some of the prior week’s improvement and underlining how sensitive housing demand remains to even modest rate moves. The average contract rate on a 30-year fixed conforming mortgage rose to 7.35% from 7.21%, according to the latest weekly survey from the Mortgage Bankers Association.
The pullback hit both major demand channels. Purchase applications, which serve as a timely gauge of homebuying demand, fell 3% on a seasonally adjusted basis from the previous week and were 18% lower than the same week a year earlier. Refinance applications slipped 2% on the week and remained 54% below year-ago levels, showing that elevated rates are still keeping most existing borrowers out of the market.
Rates rebound after prior week’s decline
Mortgage demand had strengthened in the previous survey as rates eased to their lowest level since mid-September. That momentum did not last. In the MBA’s weekly applications survey for the week ended Nov. 13, the trade group said rising Treasury yields helped push mortgage rates higher after inflation data for October came in hotter and Federal Reserve officials signaled that additional rate increases could still be needed.
The 30-year conforming rate was the headline move, climbing 14 basis points to 7.35%, the highest level in three weeks. Costs also rose in other parts of the market. The average contract rate for 30-year jumbo loans increased to 7.31% from 7.21%. FHA-backed 30-year loans rose to 7.06% from 6.98%. The average rate for 5/1 adjustable-rate mortgages increased to 6.38% from 6.28%, while the rate on 15-year fixed mortgages held at 6.64%.
Borrowers also faced somewhat higher upfront costs. Points on conforming 30-year loans increased to 0.79 from 0.75 for 80% loan-to-value loans, including the origination fee. Jumbo-loan points rose to 0.56 from 0.47, and FHA points edged up to 1.07 from 1.06. Even when headline rates are steady, changes in points can alter the effective cost of financing, especially for borrowers trying to make a purchase work at already-stretched home prices.
That mix matters because mortgage demand has been fluctuating around a low base rather than showing a durable recovery. The prior week’s survey had recorded a 6.2% increase in total applications as rates declined. Last week’s reversal suggests buyers and refinancers are still reacting quickly to rate changes near the 7% level, with little cushion from income growth or improved affordability.
Purchase and refinance activity both weakened
The weekly decline was broad enough to include both purchase and refinance demand, although the underlying pressures were not identical. Purchase applications fell 3% on a seasonally adjusted basis and 7% on an unadjusted basis from the previous week. Relative to the same week in 2025, unadjusted purchase activity was down 18%, a sign that affordability continues to weigh on prospective buyers even during what would normally be an active fall market.
For the purchase market, higher mortgage rates add strain at a time when home prices remain elevated in many parts of the country. A move of 14 basis points in the average 30-year rate may not seem dramatic on its own, but for households already close to the edge of qualifying, it can raise monthly payments enough to push a target home out of reach. That pressure is one reason purchase applications have struggled to build consistent momentum despite occasional weekly rebounds.
Refinance activity also slipped, falling 2% from the prior week. The level remained far below last year’s pace, but there was still some variation within the category. MBA said FHA refinances increased nearly 7% over the week, helped by the fact that the FHA rate remained about 30 basis points below the conforming rate. Even so, the broader refinance market remains constrained because relatively few borrowers have an incentive to replace older mortgages with new loans carrying rates above 7%.
The composition of applications shifted modestly. Refinancing accounted for 41.1% of total mortgage activity, up from 39.8% a week earlier. The adjustable-rate mortgage share eased to 10.8% from 10.9%. Government-backed segments gained a little ground: the FHA share rose to 16.1% from 15.5%, the VA share increased to 12.8% from 12.4%, and the USDA share was unchanged at 0.5%. Those changes point to borrowers looking across loan types for any available pricing advantage as financing conditions remain tight.
Higher borrowing costs continue to weigh on affordability
MBA’s weekly survey is not a measure of closed home sales, but it is one of the timeliest indicators of mortgage demand and often provides an early read on changes in buyer and refinance interest. The report covers U.S. closed-end residential mortgage applications originated through retail and consumer-direct channels, with responses from mortgage bankers, commercial banks, thrifts and credit unions. Because the survey tracks application activity rather than completed closings, it tends to react quickly when rates move.
Last week’s data fit a broader pattern that has defined much of the housing-finance market this year. Whenever rates drift lower, purchase and refinance demand can stabilize or improve for a short period. When rates rebound, applications usually soften again, because affordability remains tight and many households still face high home prices, limited inventory in some markets and monthly payments that remain well above levels common before the Federal Reserve’s tightening cycle.
That backdrop helps explain why the latest weekly decline matters even though it followed only one week of stronger activity. Purchase applications are a useful signal for future housing turnover, lender volume and related housing-market activity. Refinance demand, meanwhile, influences fee income for lenders and can provide relief to homeowners when rates fall enough to make a new loan worthwhile. With the benchmark 30-year conforming rate back at 7.35%, neither side of the market appears to have much room to accelerate.
The next weekly MBA survey will show whether this was a brief setback or the beginning of another stretch of softer demand. For now, the latest reading suggests that the recent dip in rates was not enough to change the larger picture. Mortgage activity remains subdued, and a relatively small jump in rates was enough to pull both home-purchase and refinancing demand lower again.
More News
Latest News
View all news- TJX Reports 4% Comparable-Sales Growth and $1.34 in Adjusted Quarterly Earnings Per Share
- McGraw Hill Sets 5%–8% Long-Term Revenue Growth Target, Outlines Cash Flow Plan
- U.S. Outdoor Recreation Economy Reaches $704.2 Billion, New Federal Data Show
- Atlanta Fed Lowers Fourth-Quarter GDPNow Growth Estimate to 3.2%
- U.S. Pending Home Sales Fall 4.7% in October, Marking Second Straight Month of Record-Low Contracts
