U.S. Corn Export Sales Hit Marketing-Year High of 2.88 Million Tonnes
Mexico accounted for roughly 2 million tonnes of the new bookings, which more than doubled from the prior week even as USDA cut its annual export forecast.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy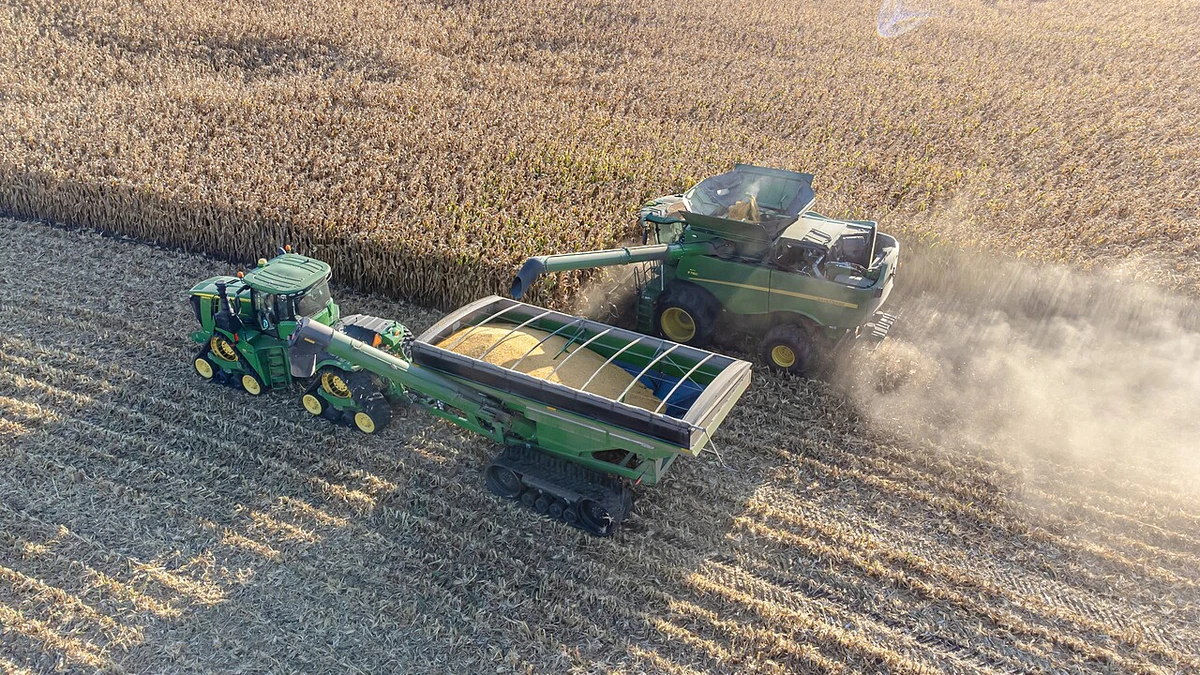
U.S. corn export sales rose to roughly 2.88 million metric tonnes in the week ended November 5, the highest weekly total of the 2026/27 marketing year so far. The U.S. Department of Agriculture released the figures on Friday, November 13, with Mexico accounting for approximately 2 million tonnes of the new business.
The volume was more than twice the roughly 1.29 million tonnes reported for the previous week. It represents net sales commitments for delivery during the current marketing year, rather than grain that has necessarily left the United States. That difference matters when judging how quickly overseas demand is translating into physical exports.
The weekly tally comes at a complicated point for the U.S. corn outlook. Recent buying shows that importers are still placing large orders, but shipments have not kept pace with the comparable period last year. USDA also lowered its full-season export forecast just three days before the latest sales figures were released.
The figures are part of the USDA Foreign Agricultural Service’s weekly export-sales system, which records new orders and adjustments across major agricultural commodities. Exporters report activity by destination and marketing year, and the agency publishes the aggregated data through its Export Sales Query System.
Mexico accounted for most of the week’s orders
Mexico was responsible for about seven-tenths of current-year corn net sales in the November 5 reporting week. Its share is unusually important to the interpretation of the headline number: a strong total driven by one major buyer tells a different story from equivalent growth spread evenly across several destinations.
USDA’s daily export-sale notices help show how the orders developed. On November 2, the agency disclosed a private sale of 1,729,740 tonnes of corn to Mexico. Of that amount, 1,135,380 tonnes were for delivery in 2026/27, and 594,360 tonnes were for 2027/28. The second portion belongs to a later marketing year and is not part of the 2.88 million-tonne current-year total.
A further 315,000 tonnes of corn for Mexico were announced on November 3 for 2026/27 delivery, alongside 136,000 tonnes for South Korea. These daily notices identify particularly large sales; they are not a substitute for the weekly net figure, which captures a broader range of reported activity and incorporates adjustments to earlier commitments.
That distinction also prevents double-counting. The daily announcements are included in the weekly reporting framework, so adding them to the Friday total would inflate the amount of business actually recorded. Likewise, orders for the next marketing year must be tracked separately rather than treated as immediate demand for this season’s crop.
The concentration of buying in Mexico demonstrates the importance of a nearby established destination for U.S. corn. It does not, on its own, establish whether import demand will remain at the same rate over the next several weeks. New bookings can be revised or canceled, and the pace of eventual delivery depends on shipment schedules and other commercial factors.
Grain inspections show a slower physical export pace
A separate USDA series offers a useful check on the sales news. Federal grain export inspections for corn totaled 905,267 tonnes in the week ended November 5, compared with 898,391 tonnes in the preceding week. That was a modest increase in inspected volume, nowhere near the scale of the week’s new sales commitments.
For the marketing year through November 5, cumulative corn export inspections stood at 11.59 million tonnes, down from 13.79 million tonnes at the same point a year earlier. The difference is about 15.9%. Mexico, Colombia and Japan were among the principal destinations recorded in the latest inspections figures.
Sales and inspections answer different questions. The Foreign Agricultural Service’s net sales data show changes in export commitments, including business intended for later delivery. Inspection figures measure grain presented for export inspection during the reporting period. Neither measure should be described as interchangeable with the other.
Large orders can strengthen the sales book before the grain is loaded, inspected or delivered. Conversely, a shipment may be fulfilling a contract signed many weeks earlier. The lag between those stages means a single strong sales report is not proof that the physical export pace has already accelerated.
For producers and grain traders, that gap is worth following rather than treating as a contradiction. The latest bookings could support future movement if buyers take delivery as scheduled. The inspections series will provide one indication of whether this demand begins to appear in export channels, although it is not a complete substitute for final shipment statistics.
USDA recently lowered its full-season export forecast
The latest sales report followed a more cautious annual projection from the Agriculture Department. In its November 10 World Agricultural Supply and Demand Estimates, USDA reduced projected U.S. corn exports for 2026/27 by 25 million bushels to 3.275 billion bushels, equivalent to about 83.2 million metric tonnes.
That forecast covers the entire marketing year, not just the week in which Mexico placed substantial orders. The cut therefore does not negate the sales surge, just as one exceptionally strong weekly figure does not by itself require an increase in the annual outlook. USDA weighs expected demand against the broader supply situation and evidence from the export pipeline.
Supply estimates changed more sharply than the export forecast. USDA lowered projected corn production by 141 million bushels to 15.893 billion bushels after reducing its yield estimate to 179.6 bushels per acre from 181.2 in October. The agency also lowered its projection for feed and residual use by 25 million bushels.
With the expected crop smaller, projected corn ending stocks fell by 91 million bushels to 1.758 billion. That revision occurred despite the reductions to both feed use and exports. USDA put the season-average farm price at $4.60 per bushel, 10 cents below its October estimate, a forecast rather than a current cash-market quote.
Strong short-term orders alongside a lower annual export estimate leave two questions open. Will the latest commitments turn into sustained shipment growth, and will the agency see enough follow-through to change its forecast? The next weekly export-sales report is scheduled for November 19, while the next monthly supply-and-demand update is due December 10.
More News
Latest News
View all news- India’s ₹34,000-Crore Government Bond Auction Clears at 7.3203% Yield
- Vertiv Raises Annual Dividend 60% to 40 Cents a Share
- Swiss Dental Company vVARDIS Prices $175 Million U.S. IPO at $18 a Share
- Danish Disposable Income Rose 4.5% in 2025, New Official Data Show
- German Wholesale Prices Rise 8.8% in October, Fastest Annual Increase Since Early 2023