U.S. Commerce Publishes Final Antidumping Duty Review Results for Vietnamese Shrimp
Commerce set final dumping margins of 10.71% for Fimex, 6.36% for STAPIMEX and 7.59% for 27 other eligible exporters. The Vietnam-wide rate stays at 25.76%.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy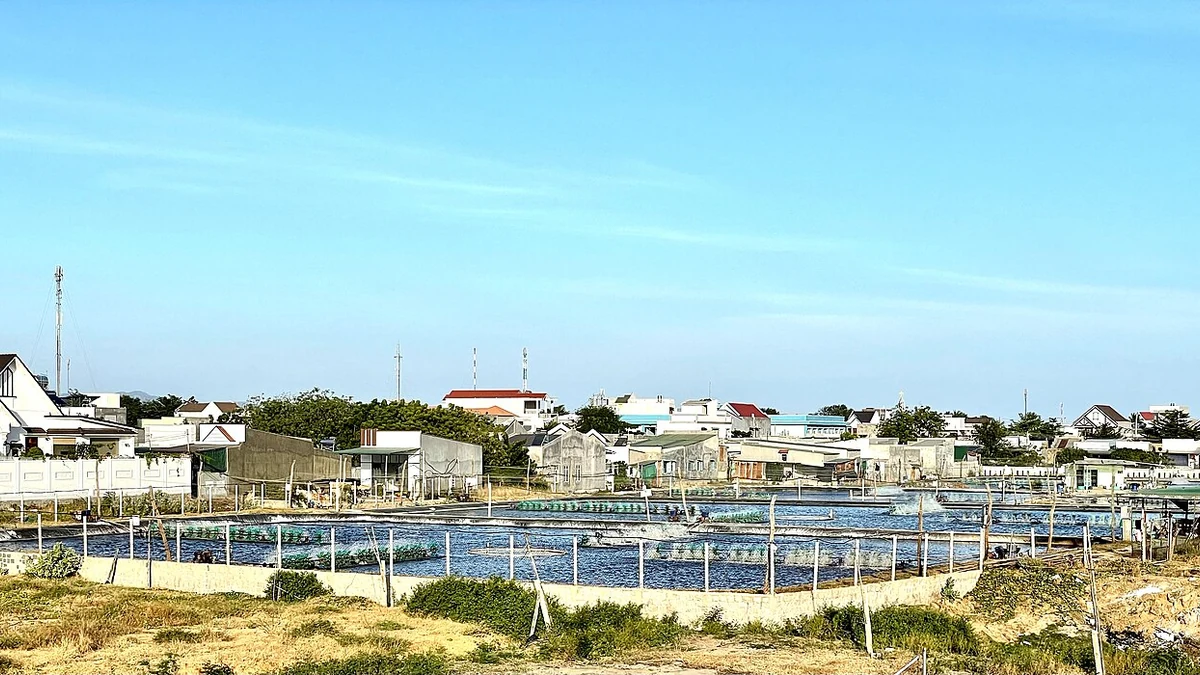
The U.S. Department of Commerce published final antidumping duty review results for certain frozen warmwater shrimp from Vietnam on Friday, November 6, setting a 10.71% dumping margin for the Fimex Group and 6.36% for Soc Trang Seafood Joint Stock Company, known as STAPIMEX. Another 27 Vietnamese exporters that qualified for a separate rate received a 7.59% margin.
The findings cover shrimp entered into the United States from February 1, 2024, through January 31, 2025. They also establish cash deposit requirements for covered shipments entering the U.S. from the publication date onward. The Vietnam-wide rate remains at 25.76%, although that figure was not recalculated in this review.
The final notice in the Federal Register sets out different treatment for exporters individually examined by Commerce, other companies granted separate-rate status and businesses that remain part of the Vietnam-wide entity. Those distinctions matter because the published margins are not a single new tariff applied uniformly to every shrimp supplier in Vietnam.
Final margins change modestly from preliminary results
Commerce reduced the Fimex Group margin from the preliminary 10.76% to 10.71%, a decrease of 0.05 percentage points. The STAPIMEX margin increased from 6.30% to 6.36%, or 0.06 percentage points. For the 27 eligible exporters not individually examined, the rate rose from 7.56% to 7.59%, a gain of 0.03 percentage points.
The differences are small compared with the gaps between the exporters’ final rates. Fimex faces a margin more than four percentage points higher than STAPIMEX, even though both were selected for detailed examination in the same review. The 7.59% rate for the remaining eligible companies is derived from the weighted average of the two examined respondents’ margins rather than from an individual calculation for each of those exporters.
Commerce selected Fimex and STAPIMEX as mandatory respondents and reviewed information about their sales and production costs. In the final notice, the department said it adjusted the calculations after considering comments and its review record. The detailed issues addressed include raw shrimp valuation, pricing methodology, production inputs and certain offsets used in the dumping calculations.
All 29 exporters granted separate-rate status include the two mandatory respondents and the 27 other qualifying companies. Eligibility for a separate rate is an administrative determination about how an exporter is treated under the antidumping order; it does not mean the exporter was found to have a zero dumping margin. None of the three final margins assigned to these groups is zero.
The countrywide figure applies under a separate framework. Commerce identified 131 companies in the Vietnam-wide entity in its final results, compared with 132 in its preliminary list. It removed Khang An Foods Joint Stock Company from that list because the company is included within the Fimex Group for this review. As the Vietnam-wide entity itself was not reviewed, its existing 25.76% margin remains in place rather than representing a fresh calculation.
The review relies on an existing order and distinct pricing rules
The United States has maintained an antidumping duty order on covered frozen warmwater shrimp from Vietnam since 2005. This administrative review revisits how the order applies to entries in a specific historical period; it is not the launch of a new antidumping investigation. The result can affect duties ultimately assessed on reviewed entries as well as deposits collected on later imports.
An antidumping margin reflects Commerce’s determination that merchandise was sold in the U.S. at less than its calculated normal value under the applicable trade-remedy rules. It is not, on its own, a measure of a company’s overall profitability or a prediction of how much retail shrimp prices will change. The calculation depends on the legal methodology and the information examined for the companies under review.
Vietnam’s treatment as a non-market economy is particularly relevant to that calculation. In an earlier Commerce decision on Vietnam’s trade status, the department said it would continue using its non-market-economy methodology for antidumping proceedings. Under that approach, Commerce can rely on market-based prices and costs from a comparable country when constructing normal value rather than simply accepting the exporter’s domestic costs.
The department also applied partial adverse facts available to STAPIMEX in the latest results. Commerce said the exporter had not adequately described five chemical factors of production despite requests for information. For those inputs, the agency used the highest reported chemical surrogate value on the record. The notice does not support attributing the entire 6.36% final margin to that one adjustment; the rate reflects the complete review calculation.
The Fimex Group treatment illustrates why company names in the notice require care. Commerce lists Sao Ta Foods Joint Stock Company, FIMEX VN, Sao Ta Seafood Factory and Khang An Foods Joint Stock Company together as one examined entity for these results. Counting those names as separate exporters with separate calculated margins would misstate the decision.
The final findings followed preliminary results published in May and additional consideration of submissions from interested parties. Commerce’s issues-and-decision process addressed questions about the Fimex Group’s raw shrimp surrogate value, STAPIMEX’s chemical inputs and other calculation points. The published final percentages, not preliminary estimates or arguments made by either side, govern the new cash deposit rates specified in the notice.
Importers face separate rules for past entries and new shipments
For imports made during the February 2024 through January 2025 review period, U.S. Customs and Border Protection will assess antidumping duties on appropriate entries according to Commerce’s instructions. For sales examined for Fimex and STAPIMEX, the department calculated importer-specific assessment rates from the dumping amounts and entered values, or per-unit rates where entered values were not available. The final companywide margin therefore should not automatically be read as the exact bill for every individual importer’s past shipment.
Entries associated with the 27 eligible but non-examined exporters are subject to the 7.59% assessment rate specified for that group. Commerce said entries attributable to the 131 companies in the Vietnam-wide entity are to be assessed at 25.76%. It also prescribed Vietnam-wide treatment for certain sales not reported by the mandatory respondents and for some shipments where an examined producer did not know the goods were destined for the United States, subject to the availability of an applicable intermediate-company rate.
Cash deposits operate on a different timeline. Starting with covered merchandise entered, or withdrawn from warehouse for consumption, on or after November 6, 2026, the deposit rate for the examined companies and eligible separate-rate exporters generally follows the final margins. Previously examined exporters with their own existing separate rates can retain those rates if they are not listed in this review, while Vietnamese exporters without separate-rate eligibility remain subject to the 25.76% Vietnam-wide deposit rate.
For non-Vietnamese exporters without their own separate rate, Commerce directs that the deposit rate correspond to the Vietnamese exporter supplying the merchandise. These rules mean an importer needs to identify the exporter and applicable case treatment rather than relying only on the country of origin. Cash deposits are collected toward estimated duties; final assessment of covered entries is a separate customs step.
Commerce intends to issue instructions for assessing duties no earlier than 35 days after the Federal Register publication. If a timely case is filed at the U.S. Court of International Trade, the instructions will account for the period during which parties may seek an injunction against liquidation. That procedure can affect when import entries are finally settled, without itself changing the published dumping margins.
The notice also reminds importers to file required certifications concerning reimbursement of antidumping or countervailing duties before the relevant entries are liquidated. Failure to meet that requirement can lead Commerce to presume reimbursement and instruct the assessment of doubled antidumping duties, or a corresponding increase involving countervailing duties. The immediate next implementation step is therefore the customs assessment process, while the new deposit requirements take effect with publication.
More News
Latest News
View all news- UK Public Service Productivity Grows 0.3% Over the Year to June, ONS Reports
- U.S. Economy Adds 165,000 Jobs in October as Unemployment Rate Slips to 4.1%
- Norwegian Banks’ Net Interest Income Falls Through Third Quarter as After-Tax Profit Reaches NOK 69.4 Billion
- Japanese Investors Buy ¥1.31 Trillion in Foreign Long-Term Bonds, Reversing Selling Streak
- Humana Raises 2026 Adjusted Earnings Outlook to at Least $9.50 a Share