Japanese Investors Buy ¥1.31 Trillion in Foreign Long-Term Bonds, Reversing Selling Streak
Japanese investors returned to foreign long-term bonds after six weeks of net selling, as overseas investors also increased their holdings of Japanese debt.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy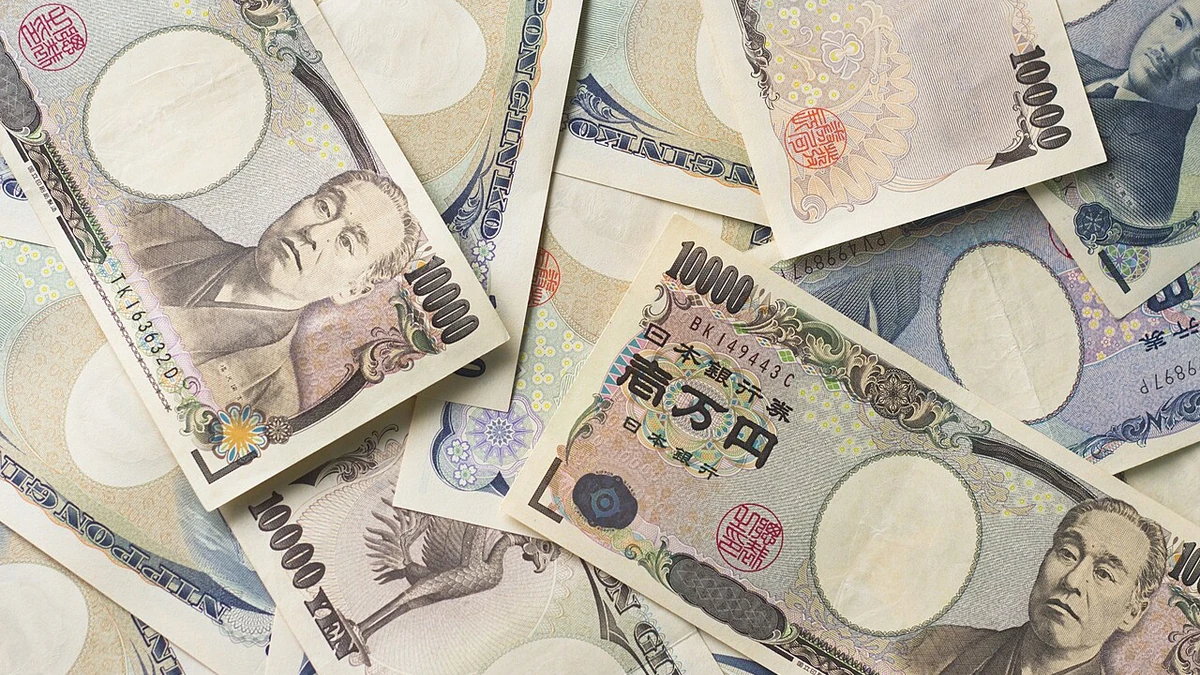
Japanese investors bought a net ¥1.312 trillion of foreign long-term bonds in the week ended October 31, ending six consecutive weeks of net sales, according to figures released by Japan’s Ministry of Finance on November 6. The return to buying marks a sharp weekly change in overseas bond flows, although the report does not identify the countries or individual securities that received the investment.
Over the preceding six weeks, investors had produced about ¥3.51 trillion in cumulative net sales of overseas long-term debt. In the immediately preceding week, net sales were revised to ¥81.8 billion. The latest buying therefore represents a substantial change from the previous week, but it does not erase the earlier withdrawals. Investors also sold a net ¥209.3 billion of foreign short-term debt in the latest reporting period.
The Ministry of Finance’s International Transactions in Securities series measures purchases and sales made by designated major Japanese investors. It provides an early account of capital moving across borders and separates long-term debt, short-term debt, and equities. The headline number is the difference between purchases and sales, not the total value of bonds bought.
Six Weeks of Overseas Bond Selling Come to an End
Measured in the ministry’s published units of ¥100 million, the latest net acquisition was 13,120, equivalent to ¥1.312 trillion. A positive number means acquisitions exceeded disposals; a negative number means investors sold more than they purchased. The latest result is therefore a net flow, not a statement that Japanese institutions increased their foreign bond holdings by exactly that amount after market-price changes and currency movements.
Long-term debt attracted net buying at the same time that short-term foreign securities recorded net sales. Taken together, the two figures show that the week’s change was concentrated in longer-dated instruments rather than an across-the-board increase in demand for every kind of overseas debt. The data do not reveal whether purchasers favored sovereign bonds, corporate debt, or another particular issuer category.
Moving from a revised ¥81.8 billion net sale in the preceding week to ¥1.312 trillion of net purchases represents a change of about ¥1.394 trillion in the weekly flow. That is a comparison between reporting periods, not evidence that one investor group moved that exact amount of money on a single day. The preceding six-week selling total remains considerably larger than this one week of buying, making a sustained reversal an open question rather than a confirmed trend.
Foreign Investors Were Also Buying Japanese Bonds
Capital moved in the opposite geographic direction as well. Nonresident investors bought approximately ¥1.48 trillion of Japanese long-term debt on a net basis during the same week, along with ¥874.7 billion of Japanese short-term debt. Their combined purchases of Japanese bonds amounted to roughly ¥2.36 trillion, a larger total than the net foreign long-term bond purchases made by Japanese residents.
These are separate measures of what different investor groups bought. Japanese purchases of debt issued overseas do not cancel out foreign purchases of debt issued in Japan, and the totals should not be interpreted as a single bilateral money transfer. The ministry classifies the securities by the residence of their issuers, not simply by the currency printed on the instrument.
Equities showed buying in both directions too. Japanese investors acquired about ¥1.08 trillion of foreign shares and investment fund interests on a net basis, while nonresidents bought around ¥1.13 trillion of Japanese equities and fund interests. In other words, the reporting week was not confined to movements between domestic and overseas bond markets. Cross-border equity investment was positive for both groups.
The bond and equity figures make it difficult to describe the week as an uncomplicated shift out of international assets and back into Japan. Japanese residents increased their purchases of foreign long-term debt and foreign shares, while investors based outside Japan increased their purchases of Japanese securities. The figures establish the direction and size of those reported flows, not a common investment motive behind them.
What the Weekly Numbers Leave Unanswered
Japan’s weekly series is compiled from reports filed by designated major investors, including banks, securities companies, life insurers and investment management firms. It is timely, but it does not capture the entire range of portfolio investment activity covered by Japan’s balance-of-payments statistics. That difference matters when comparing a weekly change with broader claims about the country’s international investment position.
Trades are recorded on their execution dates. The ministry counts redemptions of bonds in its disposal figures, so a negative reading can include bonds maturing and being repaid, not just discretionary decisions to sell in the market. The weekly report is useful for spotting changes in reported flows, but it cannot by itself explain every change in holdings or investor behavior.
The weekly data do not show which foreign markets received the ¥1.312 trillion of long-term debt purchases. It would therefore be inaccurate to equate the number with purchases of U.S. Treasury securities, even though U.S. bonds are an important part of global fixed-income markets. The figures likewise do not disclose how much currency risk investors hedged or the currencies in which the bonds were issued.
Interest-rate differences, bond yields, exchange rates and hedging costs can all affect the attractiveness of overseas debt for Japanese institutions. Those considerations help explain why cross-border bond flows are watched closely, but this release does not measure their individual effects. Nor does it establish that a particular change in stock prices or central-bank policy caused the latest buying. Assigning a single reason would go beyond what the underlying figures support.
Scheduled for November 12, the next weekly release will cover November 1–7 and provide another observation after the six-week selling streak ended. The ministry also has its October monthly securities report scheduled for November 10. Those figures will offer a broader view of the period, although the weekly and monthly datasets should still be interpreted according to their respective coverage and methodology.
More from Investing
Latest News
View all news- U.S. Consumer Sentiment Rises to 51.0 in November as Inflation Expectations Ease
- USDA Finalizes WIC Rule Allowing Online Grocery Orders and Digital Payments
- U.S. Commerce Publishes Final Antidumping Duty Review Results for Vietnamese Shrimp
- Sweden’s October Budget Deficit Comes in Below Forecast at SEK 14.5 Billion
- UK Public Service Productivity Grows 0.3% Over the Year to June, ONS Reports