Washington’s Updated Gold and Silver Bullion Tax Rules Take Effect
Washington’s revised bullion tax regulation takes effect November 21, formalizing how the state applies sales, use and business taxes after a longstanding exemption ended in January.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy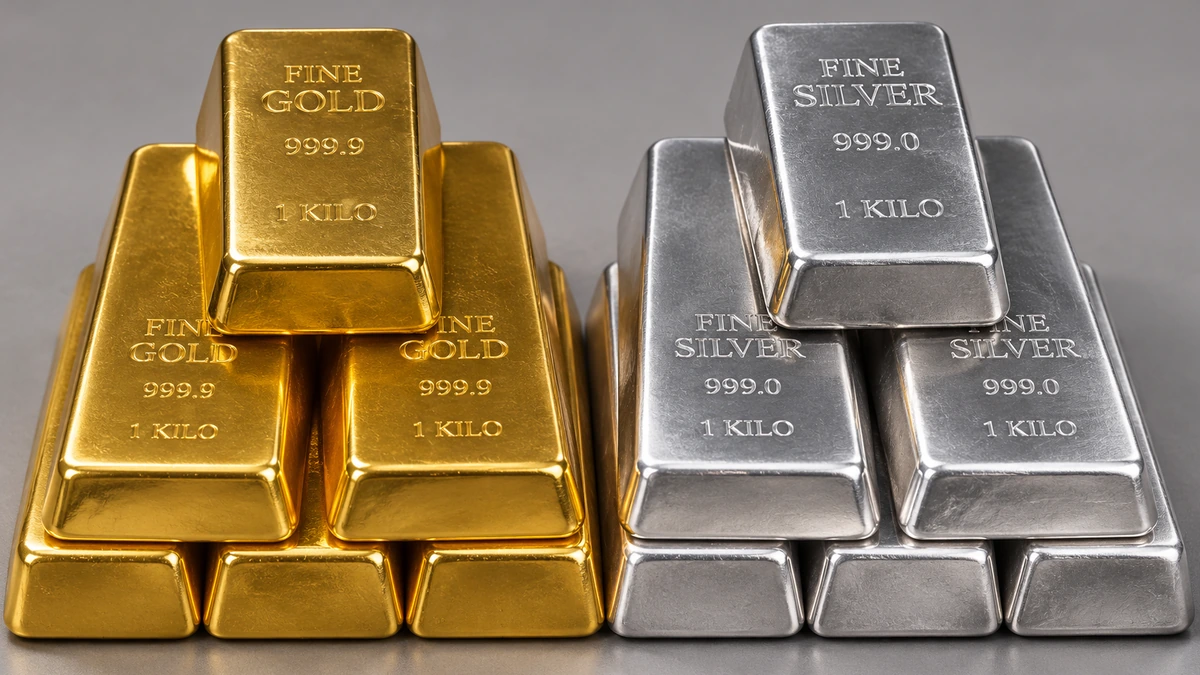
Washington state’s updated tax rule for gold, silver and other precious-metal bullion takes effect November 21, bringing the state’s written regulations into line with a tax change that began nearly 11 months earlier. The revision sets out how sales, business and occupation (B&O), and use taxes apply to bullion and qualifying metal coins.
The effective date concerns an administrative rule, not the start of a new tax on November 21. A law passed in 2025 removed a longstanding tax preference beginning January 1, 2026. The Washington Department of Revenue has now amended its guidance to reflect that change, clarifying the position for people buying bullion and businesses selling it.
The final rule, published as WSR 26-21-095, was filed October 21 and amends WAC 458-20-248, titled “Sales of precious metal bullion and monetized bullion.” Its adoption makes the revised regulatory language effective Saturday, November 21, while preserving January 1 as the date from which the revised tax treatment applies.
Washington ended the earlier bullion tax preference in January
For decades, qualifying precious-metal bullion and monetized bullion occupied a different place in Washington’s tax system from ordinary retail goods. The previous regulation described an exclusion that dated to July 1, 1985. Sales of qualifying bullion generally fell outside the definitions of retail and wholesale sales for these purposes, and the rule described relief from retail sales tax and the corresponding B&O classifications.
That approach changed when lawmakers approved Engrossed Substitute Senate Bill 5794 in 2025. Section 105 of the legislation repealed RCW 82.04.062, the provision that had excluded precious-metal bullion and monetized bullion from the ordinary retail and wholesale sales definitions. The repeal became effective January 1, 2026, rather than on the November date attached to the newer rule.
The new regulation explicitly separates the two periods. It states that bullion sales from July 1, 1985, through December 31, 2025, were covered by the former tax treatment. From January 1, 2026, those sales are included within the statutory definitions of retail and wholesale sales. That distinction is central to understanding what changed today: the department has updated the regulation to match legislation already governing sales this year.
Washington’s Department of Revenue had notified buyers and sellers of the tax change ahead of its implementation. Its September 2025 special notice explained that precious-metal bullion and monetized bullion would no longer be excluded from wholesale or retail sales beginning in 2026. The November rule adoption therefore does not reopen a grace period or introduce a separate statewide bullion tax with its own new effective date.
Retail buyers and resellers face different tax treatment
For a retail purchase of qualifying gold or silver bullion, the department says the dealer must collect retail sales tax from the customer. The dealer’s gross income from sales to end consumers is also subject to B&O tax under the Retailing classification. These are distinct obligations: retail sales tax is collected on taxable sales to customers, while B&O tax applies to the seller’s business receipts.
Wholesale purchases are treated differently. When a buyer is purchasing bullion for resale and supplies a valid reseller permit, the seller’s gross income is subject to B&O tax under the Wholesaling classification, according to the department. Retail sales tax does not apply to qualifying wholesale sales. The reseller-permit requirement matters because simply describing a purchase as an investment or saying that a buyer intends to resell it does not, by itself, establish that the sale qualifies for wholesale treatment.
The buyer’s location also affects the amount collected on a taxable retail sale. Washington has a 6.5% state retail sales tax rate, with additional local sales tax that varies by jurisdiction. The bullion rule does not establish one uniform combined rate for all buyers. The applicable rate depends on the location and the normal sales-tax rules, so a buyer should not assume that a single advertised rate covers every Washington purchase.
The updated language addresses use tax as well. For purchases occurring on or after January 1, 2026, the rule says use tax applies when a consumer first uses precious metals in Washington and retail sales tax has not been paid. This is particularly relevant when a taxable item is purchased without Washington sales tax being collected. The rule does not make ownership alone a new taxable event on November 21, but it does explain how the existing use-tax obligation fits purchases made under the 2026 framework.
For dealers, the change means ordinary recordkeeping and classification questions now matter in bullion sales as they do elsewhere in retailing. Sellers need to distinguish purchases by end consumers from documented sales for resale, collect the appropriate retail tax when required, and report gross receipts under the proper B&O classification. The department’s notice describes these obligations without announcing a special rate tied to movements in gold or silver prices.
Which metals, coins and dealer fees the rule covers
Despite the attention paid to gold and silver, the regulation covers a wider group of precious metals. It defines precious-metal bullion by the nature of the material and how it is valued: a metal that has been smelted or refined and whose value depends on its contents rather than its manufactured form. The listed examples include gold, silver, platinum, rhodium and palladium. Standard bars and other processed forms of metal can fall within this definition when their value is based principally on their metal content.
The rule also covers “monetized bullion,” a separate category for coins and other forms of money made from gold, silver or other metals that have been used as a medium of exchange under applicable laws. It distinguishes those items from coins or money sold to be made into jewelry or works of art. This distinction is important because a buyer cannot decide the applicable tax treatment solely by the fact that an item is metallic, collectible or stamped with a face value. The nature of the item and the purpose of the sale can affect how it is classified.
Dealer commissions are another part of the rule’s scope. The department says amounts received by dealers, brokers and other agents for buying or selling precious metals on customers’ accounts are generally subject to the service and other activities B&O classification. That is separate from the treatment of a dealer’s own gross receipts from retail or wholesale bullion sales. It also means fees charged for acting as an intermediary should not automatically be confused with the selling price of metal owned and sold by a dealer.
The filing history helps explain the timing. The Department of Revenue proposed revisions during 2026 after the 2025 legislation changed the underlying law, then adopted the permanent amendment on October 21. By taking effect November 21, the regulation now states directly what the department had already told dealers and consumers about bullion sales made since January.
For buyers assessing a new purchase, the practical question is whether retail sales tax applies to that sale and at what location-based rate. For businesses, the corresponding questions concern resale documentation, tax collection and reporting. The updated rule supplies the formal regulatory language for those obligations; it does not announce a second change in the law’s effective date.
More News

Latest News
View all news- Spain’s Sánchez Proposes Bank Tax Extension to Raise €1.4 Billion for Housing
- New York’s New CPA Licensing Law Takes Effect, Adding 120-Credit Pathway
- Nasdaq Rule Removing CORE FIX Order-Entry References Becomes Operative
- Monte dei Paschi Calls Intesa Takeover Offer Financially Fair but Says It Undervalues Future Potential
- France Opens €1,000–€10,000 Emergency Grants for Small Businesses Damaged by Unrest