Monte dei Paschi Calls Intesa Takeover Offer Financially Fair but Says It Undervalues Future Potential
Monte dei Paschi questioned how much of Intesa’s projected takeover benefits its shareholders would receive, but left the decision to tender up to investors.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy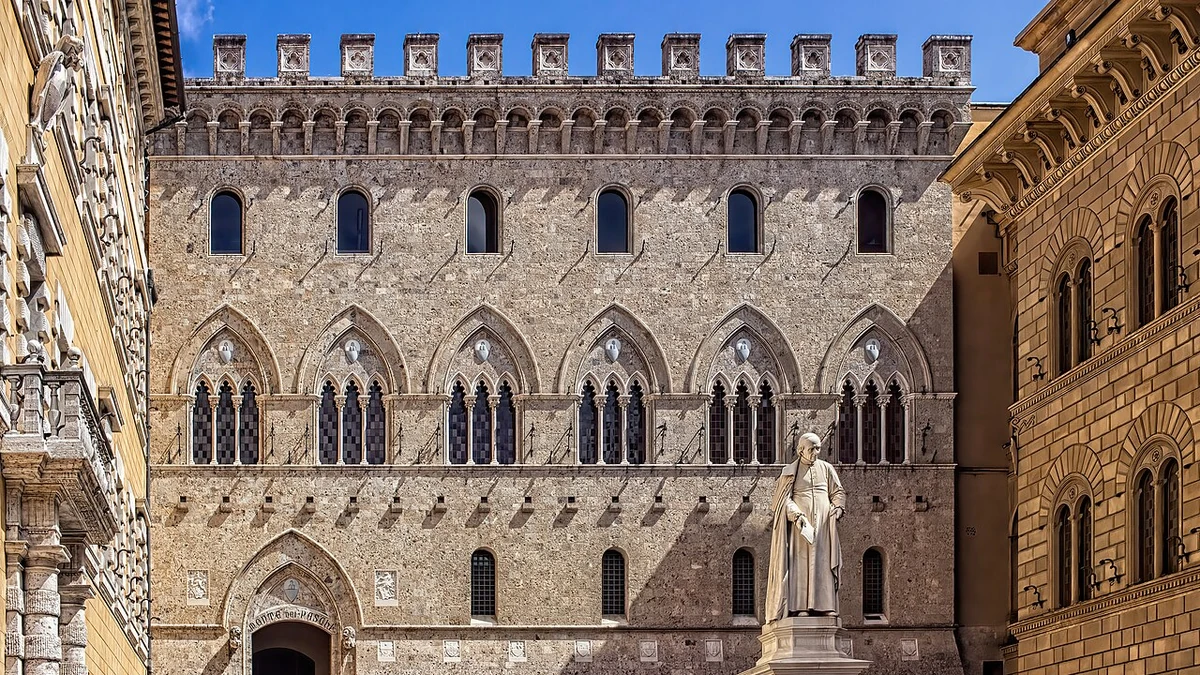
Monte dei Paschi di Siena has called Intesa Sanpaolo’s takeover offer financially fair, but said the improved cash-and-share proposal does not fully reflect the Italian bank’s prospects for growth and value creation. The assessment gives shareholders a qualified view of the bid just days before they can begin tendering their shares.
The board’s position turns on a distinction between the value of the consideration at a particular date and what MPS believes its business could deliver over time. Its assessment reflects the gains it expects from its acquisition of Mediobanca, its capital position and a five-year business plan. It also questions how much of the value Intesa hopes to generate from the takeover would be passed to MPS investors.
In its statement released on November 21, MPS said the offer was fair from a financial standpoint as of November 18, based on opinions from its financial advisers and the assumptions and limits of those opinions. The board approved the statement at a November 20 meeting with the support of all directors present for the vote. Director Corrado Passera resigned during the meeting before the discussion ended. The board explicitly declined to recommend that shareholders either accept or reject the offer.
How Intesa’s revised cash-and-share offer works
Intesa is offering €1.25 in cash and 1.664 newly issued Intesa shares for each MPS share tendered, according to its published offer terms. The cash element was raised from €1, while the share ratio was adjusted from 1.600 after Intesa announced an interim dividend of €0.22 per share. That adjustment was designed to offset the effect of the dividend being detached from Intesa’s shares, rather than to provide a separate increase of equal economic value.
The structure matters because MPS shareholders who tender would receive most of their consideration in Intesa stock, not cash. MPS estimates that shares represent about 88% of the payment. The final value received by investors therefore depends heavily on Intesa’s share price, and those who accept would remain exposed to the larger banking group’s future performance rather than simply exit for a fixed cash price.
Intesa says its offer carries a 15.3% premium, up from the 12.5% premium stated when it first announced the bid in June. Those figures use the bidder’s specified reference prices. MPS noted that, at the November 18 valuation date, and on average since the cash increase, the implied value of the offer was actually below MPS’s trading price. The contrast shows why the original headline premium and the price currently available in the market can tell shareholders different things.
The offer documents set an acceptance period beginning November 24, 2026, and ending January 22, 2027, unless extended. Shareholders tendering during that period are due to receive the cash and new shares on January 29, subject to the offer’s conditions and any change to the timetable. Intesa says a possible five-trading-day reopening of acceptances could follow if the applicable requirements are met.
MPS disputes the premium and the proposed division of benefits
MPS argues that its future earnings potential cannot be judged solely by the premium attached to Intesa’s offer. Its 2026-2030 business plan envisages a broader business following the Mediobanca acquisition, with improved diversification, profitability and capital strength. The board also pointed to a planned 100% payout ratio, which is a forecast policy rather than a guaranteed distribution to shareholders.
The bank compared Intesa’s announced 15.3% premium with an average of 30% for comparable Italian banking takeover offers, while acknowledging that individual deals are not identical. MPS also challenged the way the economic benefits would be shared. Using its own calculations, the roughly €4.2 billion premium represents about 27% of an illustrative estimate of the value of Intesa’s projected synergies, suggesting that MPS shareholders would receive only a limited portion of those expected gains through the offered premium.
The synergy projections themselves are another source of disagreement. Intesa expects about €2.9 billion a year in pretax savings and additional revenue at full run rate by 2029. MPS said that amount appears high relative to the detail disclosed on its underlying assumptions and to precedents in Italian banking. Its board believes projected implementation costs may be low and that lost revenue or other adverse effects could exceed the bidder’s assumptions.
Intesa has outlined roughly €1.5 billion in annual cost savings and €1.4 billion in annual revenue benefits, after accounting for revenue attrition, as part of its rationale for the acquisition. Those are management projections, not benefits already earned. Intesa also expects pretax implementation costs of approximately €2.1 billion. Whether the bank can deliver the stated earnings improvement depends on the operating changes it carries out after gaining control.
MPS highlighted potential capital benefits from its standalone strategy, including the treatment of insurance investments under certain circumstances, and argued that its current strategic path has value beyond the proposed takeover payment. These factors are conditional and subject to future execution. They help explain why a board can accept a fairness assessment based on financial methodologies without endorsing the offer as the best outcome for investors.
Restructuring risks complicate the takeover timetable
Intesa’s plan would not simply leave all of MPS’s businesses inside the acquiring group. It envisages retaining Mediobanca and selected banking operations while transferring a separate MPS-branded banking business to Unipol. The intended division raises questions about which activities, systems and personnel would move to each group, and how those changes would affect the earnings gains on which Intesa’s projections rely.
MPS said the proposed separation could require multiple corporate and operational steps even after the tender offer closes. Its board cited antitrust proceedings, necessary authorizations and the eventual merger of MPS into Intesa as factors affecting the timetable. Those steps are planned outcomes, not completed corporate actions. MPS warned that if Intesa secures less than 66.67% of the shares, it may lack the voting control needed to approve a merger on its own, complicating the proposed restructuring.
The board also considered the implications for Siena and the surrounding Tuscan region. Intesa has proposed a technology hub in Siena, a secondary office for central functions and a possible new commercial division in Tuscany. MPS welcomed the attention to the local economy but said the commitments, responsibilities and resources were not sufficiently defined for it to assess the lasting effect on employees, customers and the city’s role within the enlarged organization.
Shareholders face a decision that therefore involves more than comparing the implied bid price with the latest MPS share price. They must weigh a largely share-based payment, the possibility of participating in Intesa’s future gains, and MPS’s stated case for remaining independent. None of the projected synergies, distributions or standalone benefits is assured, and the board’s fairness finding is tied to the valuation date and specified assumptions.
The immediate milestone is the November 24 opening of the acceptance period. Investors will then be able to evaluate the published terms against MPS’s assessment, with the scheduled January 22 closing date providing the next major decision point unless the timetable changes.
More from Banking
Latest News
View all news- Washington’s Updated Gold and Silver Bullion Tax Rules Take Effect
- India’s Exports to Africa Jump 44%, Asia Shipments Rise 21%, Government Data Shows
- Six One Commodities’ U.S.-Canada Gas Trading Authorization Begins Two-Year Term
- Canada Announces C$248,063 Investment to Restore Nova Scotia Lighthouse and Support Tourism
- New York’s New CPA Licensing Law Takes Effect, Adding 120-Credit Pathway