Espey Fiscal 2026 Profit Rises as Sales Reach $46.1 Million
Net income climbed 37% to $11.2 million as gross margin widened to 35.3%, even as year-end backlog eased from the prior-year level.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy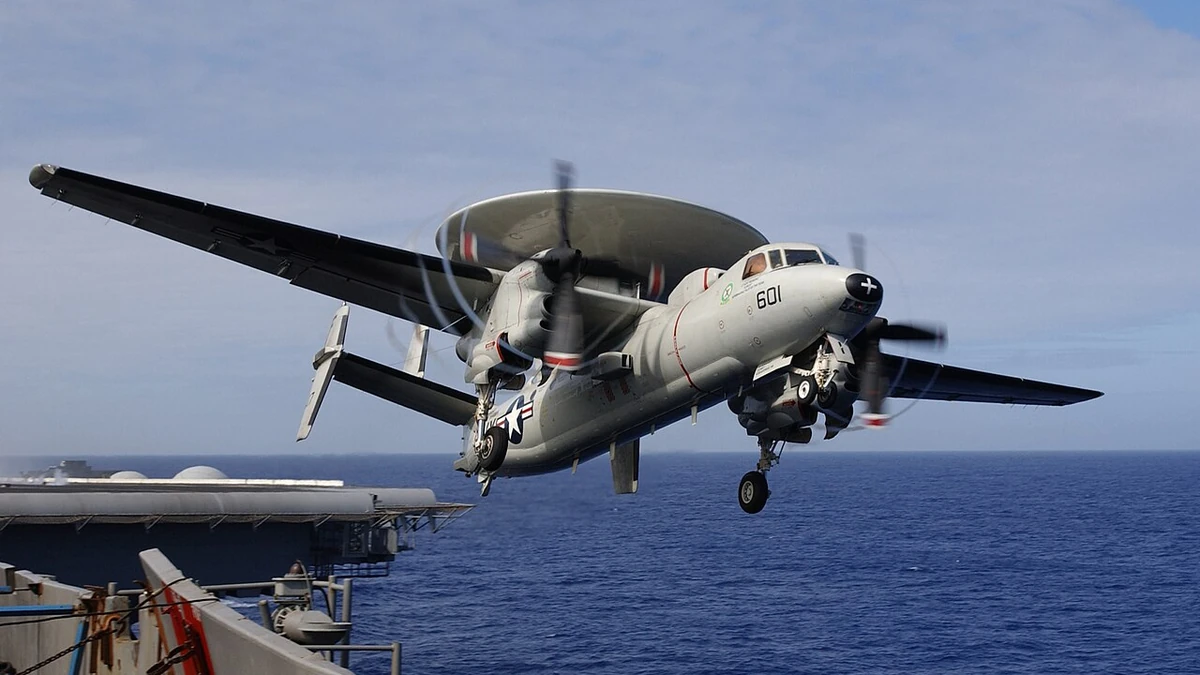
Espey Mfg. & Electronics Corp. reported higher sales and a sharper increase in profit for its fiscal year ended June 30, 2026. Net sales rose to $46.12 million from $43.95 million a year earlier, a gain of about 4.9%. Net income increased 37.3% to $11.18 million from $8.14 million, and diluted earnings per share rose to $3.89 from $3.02.
The fourth quarter supplied much of the year-end lift. Sales for the three months ended June 30 reached $13.47 million, up 40.4% from $9.60 million in the comparable quarter. Quarterly net income increased to $3.34 million from $2.93 million, with diluted earnings per share rising to $1.15 from $1.05. The stronger final quarter helped Espey finish the year above its fiscal 2025 revenue and earnings levels despite slower order intake during much of fiscal 2026.
Higher margins amplified a modest increase in annual sales
Profit grew much faster than revenue because Espey earned more gross profit from each dollar of sales. The company reported fiscal 2026 gross profit of $16.28 million, up from $12.68 million in fiscal 2025. Gross profit represented 35.3% of sales, compared with 28.9% a year earlier, an improvement of roughly 6.4 percentage points. Espey said in its annual filing that the increase in net income primarily reflected higher sales, stronger gross profit margins and increased other income, partly offset by higher selling, general and administrative expenses and a larger income-tax provision.
The fiscal 2026 annual report was filed through the U.S. Securities and Exchange Commission’s EDGAR system. The filing shows that the earnings improvement was not simply a result of a much larger revenue base. Sales increased by about $2.17 million year over year, but gross profit increased by roughly $3.60 million. That distinction matters for a manufacturer whose results can vary with the mix of defense and industrial programs moving through production at a given time.
Espey also ended the year with substantial liquidity. Cash and cash equivalents were about $19.44 million at June 30, and investment securities totaled about $26.01 million. Working capital increased to approximately $54.7 million from about $45.7 million a year earlier. The company said it had not borrowed funds during the last two fiscal years and maintained a $3 million line of credit that expires in March 2027. Operating cash flow, however, fell to $5.69 million from $20.99 million in fiscal 2025, so the income statement improvement did not translate into a comparable increase in cash generated from operations.
Backlog stays large, but fiscal 2026 orders fell sharply
Espey’s order book remained sizable at the end of June, although it was slightly smaller than a year earlier. Backlog stood at $134.9 million, down about 3.4% from $139.7 million at June 30, 2025. Of the fiscal 2026 year-end backlog, about $123.7 million was funded and $11.2 million was unfunded. Management expects approximately $48 million of the total to be filled during fiscal 2027, subject to scheduling and other factors that can affect long-duration defense and industrial programs.
The bigger change was in new orders. Espey received about $41.4 million of new orders during fiscal 2026, compared with $86.4 million in fiscal 2025. The prior year included two significant multi-year awards totaling about $49.4 million, which makes the year-over-year comparison unusually demanding. Even after allowing for that base effect, fiscal 2026 order intake was below annual sales, which explains why backlog edged lower despite the company finishing the year with record revenue.
Management’s fiscal 2027 outlook points to another year of revenue growth rather than a repeat of fiscal 2026’s margin expansion. Espey expects fiscal 2027 revenue to outpace fiscal 2026 and expects new orders to meet or exceed the fiscal 2026 level. It also cautioned that the sales mix is expected to include new products requiring heavier engineering investment. Those upfront costs may put temporary pressure on gross profit as the company works toward programs that could generate production revenue later.
Defense programs remain central to Espey’s revenue base
Espey designs and manufactures specialized power electronics, power supplies, transformers and related systems for military and severe-environment applications. Its customer base is concentrated: five customers accounted for 67% of fiscal 2026 sales. That concentration can make individual program timing and contract awards important to year-to-year results, especially for a company with annual revenue of roughly $46 million and a backlog several times that amount.
The company’s products support aircraft, naval and ground systems. Espey says its military airborne programs include high-voltage power supplies for the E-2C Hawkeye and E-2D Advanced Hawkeye, as well as products associated with platforms such as the C-130 and other defense systems. That program exposure helps explain why revenue recognition, engineering work and the timing of large awards can produce uneven comparisons even when the long-term backlog remains substantial.
Earlier in fiscal 2026, Espey had already shown that margins were strengthening before the fourth quarter. For the first nine months ended March 31, sales were $32.65 million, below the $34.35 million reported for the comparable prior-year period, yet net income rose to $7.84 million from $5.21 million. The fourth quarter then added both revenue growth and additional profit, turning the full-year sales comparison positive and lifting annual net income well above fiscal 2025.
The next quarterly filing will provide the first financial read on management’s fiscal 2027 forecast. It should also show whether new-order activity is moving toward the company’s expectation of meeting or exceeding the fiscal 2026 level, and whether heavier engineering work on new programs begins to weigh on the gross margin that drove much of the latest profit increase.
More from Investing
Latest News
View all news- Fed’s Barr Says Further Rate Adjustments Likely as Inflation Risks Rise
- Forward Industries Announces $25 Million Direct Offering to Buy More Solana
- Cracker Barrel Ends Fiscal 2026 With Lower Sales, Sets 2027 Outlook
- Bullish and Marex Partner to Expand Institutional Digital-Asset Access
- Beneficient Unveils Strategy to Challenge Former CEO-Linked Debt and Equity Claims