China’s Central Bank to Run Daily Overnight Reverse Repos at 1.25% From November 2
China will introduce daily overnight reverse repo auctions from November 2 while moving seven-day operations to a different auction format and a more selective schedule.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy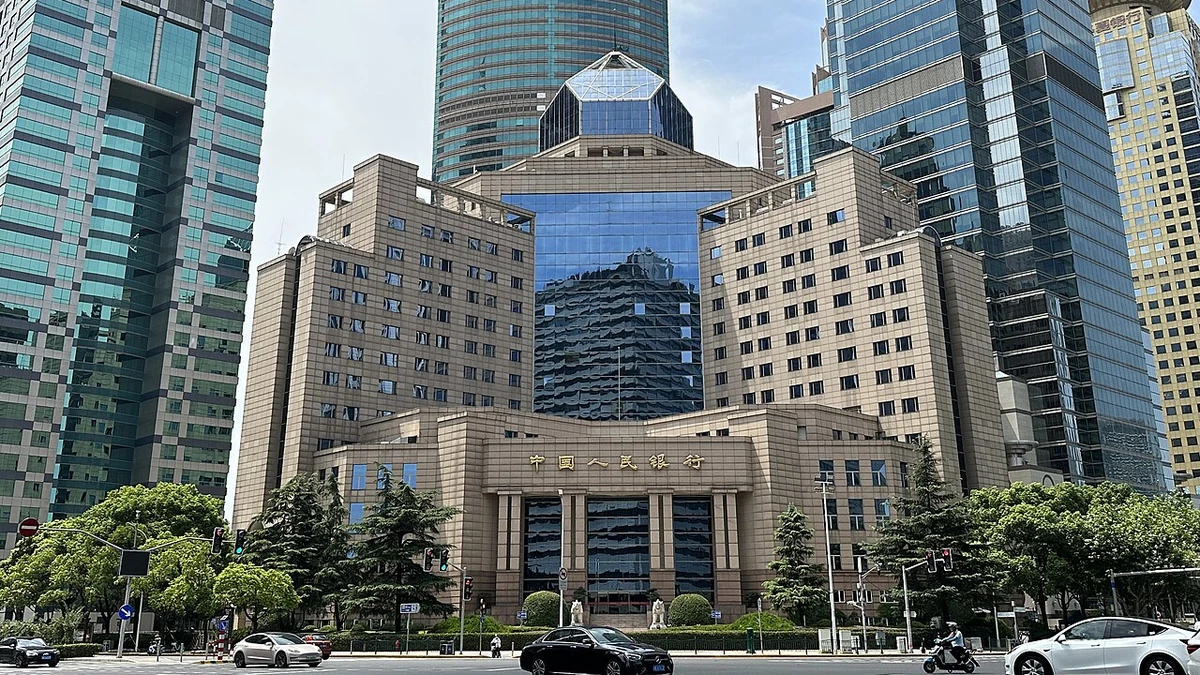
China's central bank will begin holding overnight reverse repurchase auctions every working day on November 2, a change intended to give it more direct control over the shortest-term borrowing rates in the financial system. The People's Bank of China (PBOC) announced the timetable on Friday, October 30, and said the overnight operation currently carries an interest rate of 1.25%.
The adjustment gives the one-day instrument a routine role previously filled by seven-day reverse repos. The seven-day facility will remain available, but its auctions will change format and will mainly take place around tax-payment periods and month-ends. Other central bank facilities that used the seven-day rate as a reference will instead be linked to the overnight rate.
The announcement is a change in how the PBOC conducts monetary operations, not an announced cut in borrowing rates. The 1.25% overnight rate is below the 1.40% rate on the existing seven-day operation, but those figures refer to funding with different maturities. Their 0.15-percentage-point difference should not be interpreted as a new 15-basis-point reduction for banks or borrowers.
Daily Overnight Auctions Become the Main Operating Tool
Beginning Monday, the PBOC will offer overnight reverse repos through fixed-rate, quantity-based tenders on every business day. It will set the interest rate, currently 1.25%, while participating institutions submit bids for the amount of funding they want. The announcement establishes a regular auction schedule but does not promise to inject a particular amount of cash on each day.
Reverse repos are a short-term way for a central bank to supply liquidity to financial institutions against securities, with an agreement to reverse the exchange later. An overnight operation matures the following business day, giving the PBOC a way to respond frequently to changes in banks' demand for cash. Actual liquidity conditions still depend on the amounts allotted, the funding that matures and other flows through the banking system.
The seven-day operation will be handled differently. Rather than its previous fixed-rate, quantity-bidding procedure, it will use a fixed quantity and interest-rate bidding with multiple accepted prices. That allows bids to determine the rates at which portions of an announced amount are allotted, instead of the central bank offering all accepted funding at one predetermined seven-day rate.
The PBOC identified tax-payment dates and month-end periods as the main occasions for seven-day auctions. Those are periods when cash demands and payment flows can shift markedly. Keeping a longer-duration option available gives the central bank a way to address funding needs that may not be well served by a sequence of one-day operations. The announcement does not say that seven-day reverse repos are being discontinued.
A third part of Friday's notice changes how several other liquidity tools are priced. Temporary repos and reverse repos, as well as the repo facility for foreign central banks and similar institutions, will be referenced to the overnight operation rate rather than the seven-day rate. The existing spreads above or below the benchmark will be preserved. This is a change in the reference point, not a statement that the absolute interest rate on every connected facility will be identical to its previous level.
The Reform Follows a Signal From the PBOC Governor
The decision follows a public explanation by PBOC Governor Pan Gongsheng at the Financial Street Forum on October 19. In his official remarks on the monetary-policy framework, Pan said that the interbank overnight repo rate, commonly known as DR001, had effectively become the central bank’s operating target. At the same time, the PBOC’s principal open-market instrument and principal policy rate still had a seven-day maturity.
Pan described that mismatch as a reason to consider shifting the principal operating instrument to overnight maturity. Friday's announcement puts a concrete start date and auction rules on that direction. It is therefore more than another temporary liquidity injection, even though the central bank had already conducted overnight operations before announcing the daily schedule.
The distinction matters for how policy signals reach money markets. Under the earlier framework, a seven-day auction rate helped guide shorter-term market funding costs indirectly. With a standing daily overnight auction, the central bank can express its operating rate at the maturity where it is seeking closer control. Whether market borrowing costs stay near that level will depend on bank demand, liquidity supply and conditions in the interbank market.
The new structure also separates two functions more clearly. A fixed-rate overnight auction provides a visible reference for the price of very short-term central bank funding. A seven-day auction that accepts multiple rates can be used to supply a set amount of longer funding when cash needs are concentrated. Neither feature guarantees a smooth market on its own, and neither fixes all bank funding costs at the overnight rate.
Bank Funding and Loan Pricing Remain Separate Questions
For banks, the immediate impact is operational. Treasury desks will have a daily overnight facility to consider when planning short-term funding, and they will need to account for seven-day auctions taking place on a more selective schedule. The new reference rate also matters to institutions using other PBOC tools whose pricing has historically been expressed as a spread to the seven-day operation.
The effects on loans to households and businesses are less direct. A central bank's open-market rate influences the cost of money in the banking system, but it is not itself the rate that a household pays on a mortgage or that a company pays on a loan. Changes in market funding rates must pass through lenders' pricing decisions and the terms of individual credit agreements before they affect borrowers.
Pan's October 19 speech set out a longer-term connection. He said some lenders and customers had already begun agreeing to use overnight interbank repo rates as benchmarks for floating-rate loans. He also discussed giving financially stronger companies more scope to choose between such a benchmark and the loan prime rate, while retaining a role for the loan prime rate in smaller-business and personal lending. Those ideas concern the evolution of loan pricing; they were not implemented through Friday's overnight auction notice.
Nor does Friday's announcement by itself establish that the PBOC is preparing an immediate broad interest-rate cut. It sets out the price and format of one operating instrument, changes the use of another and reanchors related facilities. Assessing any easing or tightening of monetary conditions requires looking beyond the two quoted operation rates to actual money-market prices and net liquidity supplied.
The first scheduled auctions under the new arrangement are due on November 2. Their allotment sizes, together with the behavior of overnight interbank rates and the PBOC's subsequent use of seven-day operations, will provide the first practical evidence of how the revised framework works in day-to-day funding markets.
More from Banking
Latest News
View all news- New York Fed Researchers Find LinkedIn Hiring Data Can Improve Inflation Forecasts
- India’s Fiscal Deficit Reaches 42.1% of Annual Target in First Half of FY27
- Energy Department Opens $237 Million Funding Opportunity for U.S. Power Grid Supply Chain
- Chicago Business Barometer Falls to 55.3 in October but Signals Continued Expansion
- Chevron Posts $9.9 Billion Quarterly Profit as U.S. Refinery Throughput Hits Record