UK Government Pledges Legal Protections for Access to In-Person Banking
The proposed safeguards would cover more than cash withdrawals, but ministers still need to define which in-person banking services must remain accessible.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy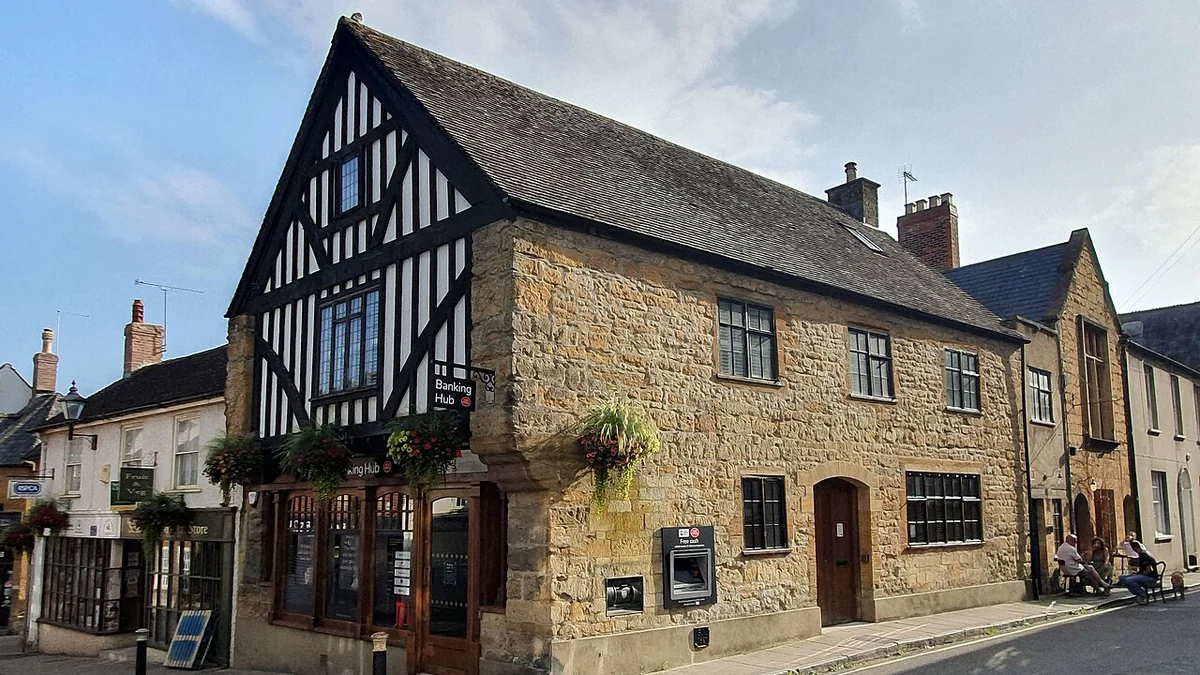
The UK government said on Monday, November 16, that it will legislate to protect access to essential face-to-face banking services, after an independent review found that millions of adults still need help from bank staff in person. The commitment is to secure reasonable access, rather than to require every bank branch to remain open.
More than three million UK adults regularly rely on in-person banking, according to evidence considered by the review, with the number rising above four million when less frequent users are included. Led by Richard Lloyd, the review drew on 18,197 responses to a public call for evidence as well as research and submissions from consumer groups, businesses and the banking industry.
The announcement gives a direction for legislation but not a finished set of rules. Ministers have not yet specified the distance people should be able to travel for different services, which banks will face the new duties or when the protections will take effect. Those choices will determine what customers actually gain from the pledge.
Protection would cover more than access to cash
The proposal targets a gap between existing cash-access safeguards and the wider help people need to run their accounts. In its November 16 announcement, HM Treasury accepted the review’s central recommendation that a new statutory framework is needed. The government plans to design the rules with the Financial Conduct Authority (FCA), banks and consumer representatives.
For personal customers, the review describes essential day-to-day services as opening and maintaining current accounts, updating account details, obtaining statements and getting assistance with payments or transfers. Some people also need help registering for online banking or completing identification checks. A cash machine or a counter that only handles deposits cannot necessarily provide that support.
The review identifies a separate set of needs that arise less often but can be difficult to manage remotely. These include handling banking arrangements after a death, registering a power of attorney, resolving account-access problems and seeking assistance following suspected fraud. People facing financial difficulties or needing additional support may also have reasons to discuss their circumstances with a member of staff.
Small businesses, charities and community organisations have somewhat different needs. The evidence emphasises cash deposits, withdrawals and change for trading, alongside updates to account mandates and authorised signatories. The review does not say every banking service must be available at every local outlet; it proposes different standards of reasonable access for routine and more complex tasks.
The FCA already oversees a statutory access-to-cash regime that took effect in September 2024. Designated banks and building societies must assess whether local changes leave significant gaps in withdrawals or deposits and arrange additional services where needed. But the regulator says those powers concern cash, not the full range of banking support, and do not in themselves stop branches from closing.
Fewer branches, with a much wider rural gap
The review puts the contraction of the branch network at 2,382 closures since January 2021, about 45% of the network it measured. In 2025, 79.6% of people lived within three miles of a branch operated by one of the larger banks or building societies offering personal current accounts, down from 87% in 2022. That measure was only 28.7% for rural residents, against 91.5% in urban areas.
Cash provision is more widespread than access to a bank branch. At the end of 2025, the review says 94.6% of the population lived within one mile of a physical cash-access point. Those locations may offer withdrawals or deposits without the staff, private space or range of services necessary to deal with a complicated banking problem. Proximity to cash therefore tells only part of the access story.
Digital banking has become the normal channel for many customers. FCA survey figures cited by the review show that 75% of day-to-day account holders used a mobile banking app during the 12 months to 2024. In a different measure, 18%, or 9.7 million account holders, visited a particular branch at least monthly in 2024, down from 40% in 2017. Regular branch visits and dependence on in-person help are not interchangeable measures.
The consequences are not confined to customers who dislike using apps. Limited digital skills, disabilities, poor connectivity and the cost of devices can make remote services impractical. Travelling to a surviving branch can also be difficult where public transport is limited. The review found that reduced access had caused recurring harm, including financial costs, lost time, stress and banking tasks that people could not complete.
Shared banking hubs offer one potential way to maintain a physical presence without restoring a separate branch for each bank. Typically, they provide a common cash counter and access to visiting community bankers from participating institutions on rotating days. The model can help with some account queries, but available services and the days on which specialist staff attend differ from place to place. Whether a hub is sufficient will depend on the needs it is expected to serve.
The new obligations still need to be defined
In a written statement to Parliament, Economic Secretary to the Treasury Lucy Rigby said the government would amend the Financial Services and Markets Bill to enable the proposed framework. The statement commits ministers to legislation and further design work, but it does not adopt every detail of the independent review or establish an immediate entitlement to a nearby full-service branch.
The review recommends placing an access obligation on designated larger providers of personal current accounts. Under its proposed approach, those banks would assess and address significant local gaps, take evidence from councils and community groups, and face FCA oversight. It also recommends standards tailored to different services and an independent route to challenge an assessment. These remain recommendations until ministers and lawmakers determine the final framework.
Among the questions still open are what counts as reasonable travel or waiting time, how often in-person specialists must be available, and whether a telephone or digital option can adequately meet a particular need. Treasury says it wants a proportionate scheme that recognises the value of accessible remote banking, avoids unnecessary costs and supports competition. It also plans to work with banks on improvements before legislation becomes operational.
The independent review suggests that banks could pilot new approaches during 2027, ahead of a possible regulatory implementation period in 2028. Those dates are the review’s assessment of what might be feasible, not a government commencement timetable. The next concrete step is the promised Bill amendment, followed by decisions on which firms and services the new protections will cover.
More from Banking
Latest News
View all news- BILL Agrees to $6 Billion Take-Private Acquisition Led by TPG, With Corpay Taking Minority Stake
- India Launches ₹5,610 Crore Development Initiatives in Arunachal Pradesh
- South Korea Readies Stock Market Stabilization Fund After Emergency Meeting
- Australia-Led COP31 Talks End Without Overarching Climate Accord After Fossil Fuel Standoff
- UK Government Unveils Financial Literacy Overhaul for Schools in England