
Home Depot Reports 4.9% Sales Growth to $43.4 Billion and Updates Annual Guidance
Comparable sales climbed 2.2% as the retailer moved its full-year sales-growth outlook to the upper end of the previous range.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy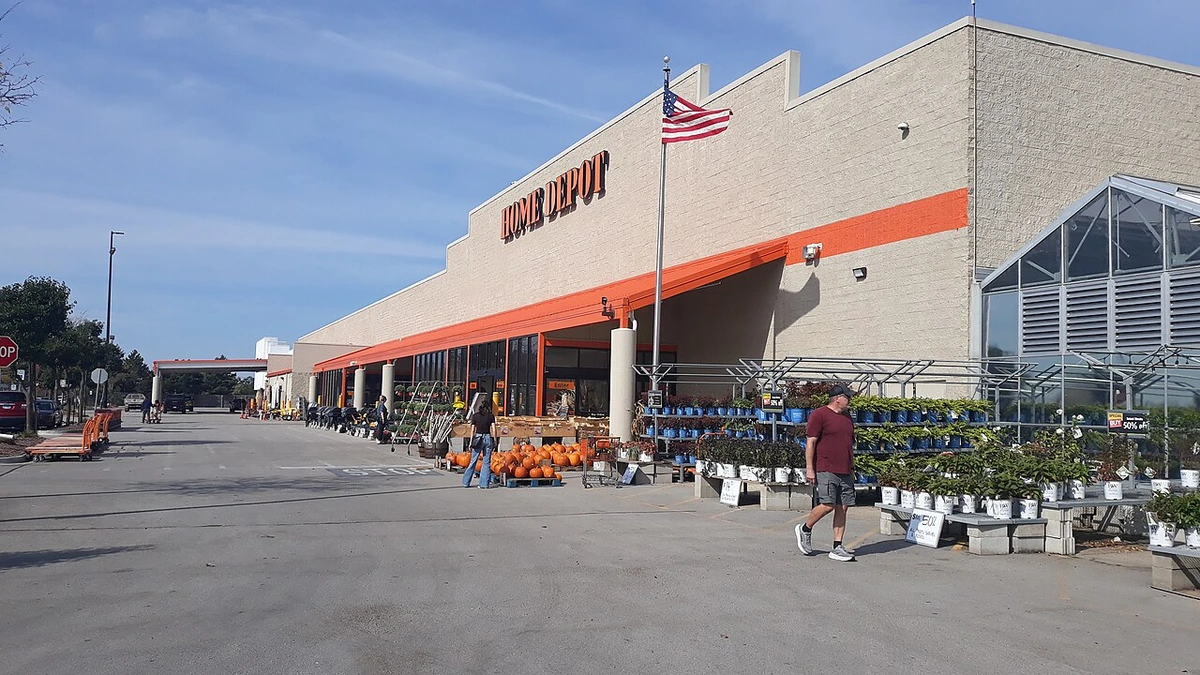
Home Depot reported $43.4 billion in sales for its fiscal third quarter, a 4.9% increase from a year earlier, and updated its annual guidance to put expected sales growth at the top of its previous range. Comparable sales increased 2.2% across the business and by the same amount in the United States.
The retailer now forecasts about 4.5% total sales growth for fiscal 2026, compared with a prior forecast of 2.5% to 4.5%. The change narrows the outlook to the earlier upper limit rather than raising it above that limit. Its projection for comparable sales growth is approximately 1.4%, within the earlier range of flat to 2.0%.
For the three months ended November 1, sales were $43.398 billion versus $41.352 billion in the year-earlier quarter. Net earnings rose to $3.71 billion from $3.60 billion, according to the company’s November 17 earnings release. The stronger top line came alongside a decline in gross and operating profit margins, showing that revenue growth did not translate into equally strong growth in operating earnings.
Comparable sales improve as customer visits remain subdued
Comparable sales were up 2.2% from the corresponding quarter a year earlier, when the measure had grown just 0.2%. The latest U.S. comparable-sales increase was also 2.2%, compared with 1.3% in the preceding fiscal quarter. Those figures offer a view of sales performance across comparable operations, separate from growth in the company’s total reported revenue.
Comparable customer transactions fell 0.5% in the quarter, even as the comparable average ticket increased 3.0%. This means the increase in comparable sales was associated with more spending per qualifying purchase rather than an increase in the count of those purchases. The numbers do not, by themselves, establish whether the bigger ticket resulted from higher prices, a different product mix or larger projects.
On a broader reported basis, Home Depot recorded 392.7 million customer transactions, down from 393.5 million a year earlier. Its average ticket rose to $93.09 from $90.39. The company notes that these transaction and ticket measures exclude the results of HD Supply and SRS Distribution, an important qualification when comparing them with total company sales.
Total sales growth of 4.9% and comparable-sales growth of 2.2% measure different parts of the business. Total revenue captures activity beyond the set of operations included in the comparable-sales measure. The earnings figures establish the size of that gap, but do not assign a precise share of it to any single acquisition, store opening or other source of revenue.
In the preceding fiscal quarter, total sales increased 5.7% and comparable sales grew 1.7%. Through the first nine months of fiscal 2026, the company reported $133.0 billion in sales, up 5.2%, with comparable sales rising 1.5%. The third-quarter comparable-sales gain therefore exceeded the nine-month pace, although quarterly comparisons also reflect the normal differences between seasonal selling periods.
Profit rises more slowly than revenue
Higher revenue came with higher merchandise costs. Cost of sales rose 6.0% from a year earlier, exceeding the 4.9% rate of revenue growth, while gross profit increased 2.9% to $14.22 billion. Based on the company’s reported figures, gross profit represented about 32.8% of sales, compared with roughly 33.4% a year earlier.
Operating income reached $5.48 billion, up 2.4% from $5.35 billion in the corresponding quarter of fiscal 2025. Operating margin eased to 12.6% from 12.9%. Selling, general and administrative costs increased to $7.89 billion from $7.64 billion, a smaller percentage increase than sales, but the pressure at the gross-profit line still left operating income growing less quickly than revenue.
Net earnings totaled $3.71 billion, an increase of 3.1%, and diluted earnings per share rose to $3.72 from $3.62. On the company’s adjusted basis, diluted earnings per share increased to $3.86 from $3.74, or 3.2%. The adjusted figure excludes the after-tax impact of amortization associated with acquired intangible assets, and should be read alongside, not in place of, the reported earnings figure.
Adjusted operating income was $5.66 billion, compared with $5.51 billion a year earlier. Adjusted operating margin was 13.0%, down from 13.3%. The company uses this measure to remove acquired intangible-asset amortization, including amounts related to SRS Distribution, from operating results; it does not exclude the revenue contributed by those businesses.
Across the first nine months, earnings also grew more slowly than sales. Net earnings for the period increased 1.6% to $11.77 billion, versus a 5.2% rise in sales. Operating margin over those nine months was 13.0%, down from 13.5%. These results add context to the revised annual targets: the business is selling more, but its profitability as a share of revenue remains below the corresponding prior-year levels.
Full-year forecast reaches the top of the prior sales range
In August, Home Depot maintained an annual forecast for total sales growth of 2.5% to 4.5% and comparable sales ranging from flat to 2.0% growth. Its new guidance of approximately 4.5% sales growth and 1.4% comparable-sales growth removes the width of those ranges. The two projections describe different measures, so the stronger total-sales target should not be treated as an identical forecast for established comparable operations.
Home Depot trimmed its annual gross-margin forecast to approximately 33.0%, from the 33.1% projected in August. Home Depot expects an operating margin of about 12.4%, at the low end of its prior 12.4% to 12.6% range. Adjusted operating margin is forecast at roughly 12.8%, also at the low end of the earlier 12.8% to 13.0% range.
For earnings, the company now expects fiscal 2026 diluted earnings per share to grow approximately 1.5% from the $14.23 it reported for fiscal 2025. Adjusted diluted earnings per share are projected to increase about 2.0% from the prior year’s $14.69. Both growth rates fall within the earlier zero-to-4% ranges, giving investors more specific targets without implying that the previous upper earnings expectations are still the central forecast.
Home Depot also forecast net interest expense of approximately $2.2 billion, compared with its previous estimate of $2.3 billion, and an effective tax rate of about 24.6%, up from 24.3%. The updated projections help explain how the company expects the operating result to translate into earnings per share, although the figures remain forecasts rather than completed annual results.
Store expansion and investment plans were left intact: Home Depot still expects to open approximately 15 new stores in fiscal 2026 and spend about 2.5% of total sales on capital expenditures. Those assumptions are unchanged from August, even as the company has revised its annual sales, margins and earnings projections.
More from Investing
Latest News
View all news- U.S.-China Congressional Commission Posts 2026 Report Examining Trade, Commodities and AI
- U.S. Mortgage Applications Fall 2.3% as 30-Year Rate Rises to 7.35%
- U.S. Housing Starts Rise 9.9% in October Even as Building Permits Drop 7.4%
- Infinity Natural Resources Signs Reorganization Agreement, Targets December 1 Closing
- U.S. Outdoor Recreation Economy Reaches $704.2 Billion, New Federal Data Show
