
Australian Gas Buyers More Than Double 2027 Long-Term Contracting, ACCC Says
Long-term prices held near A$12–13 per gigajoule even as the ACCC forecast heavier reliance on Queensland gas and storage during winter 2027.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy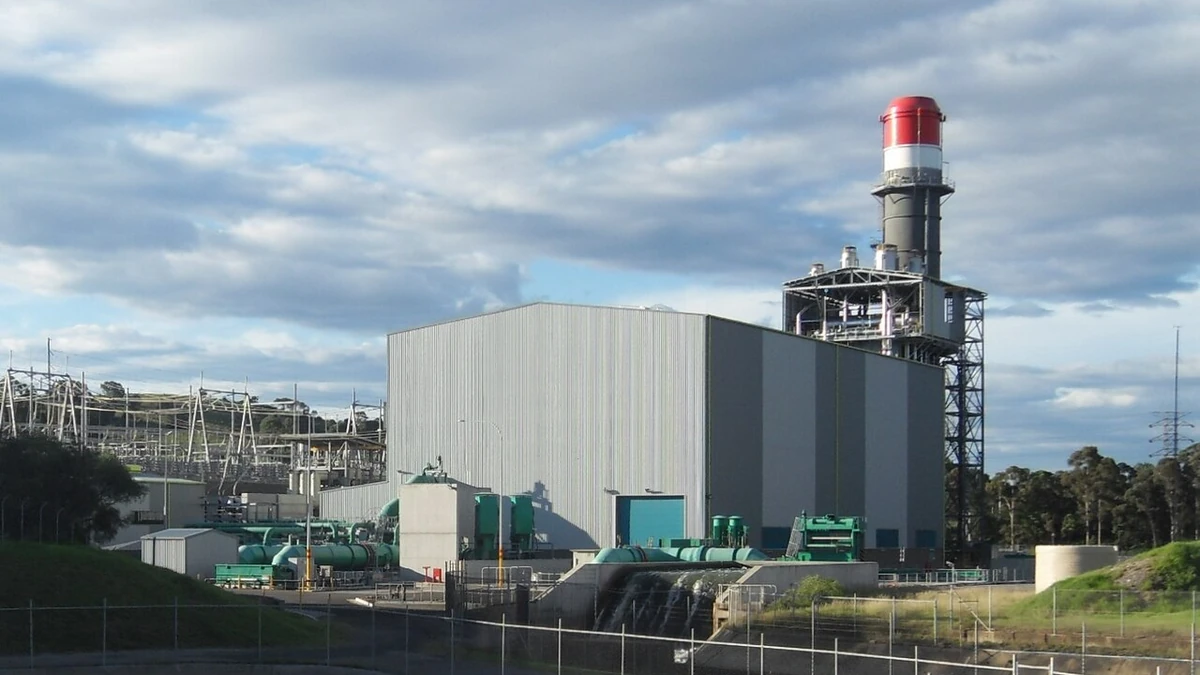
Gas buyers on Australia’s east coast signed long-term agreements for 51 petajoules of gas in the first half of 2026 for delivery in 2027, more than twice the volume contracted during the corresponding period a year earlier, the Australian Competition and Consumer Commission said Friday. The increase came without a comparable jump in agreed long-term prices, which remained around A$12 to A$13 per gigajoule for supply in 2027 and 2028.
The stronger purchasing extended beyond next year. Buyers arranged contracts for 43 petajoules to be supplied in 2028, exceeding the amount signed at the same stage of either of the previous two contracting cycles. Commercial and industrial users and other large buyers also secured more gas at this point in the process than in any of the preceding four years, according to the regulator.
Those figures, detailed in the ACCC’s October 9 gas-market update, suggest that major customers have been more willing to lock in future supply after a period of uncertainty over domestic availability and international energy prices. They do not, however, mean that the entire east coast will have ample gas when demand rises next winter. The same report warns of a large seasonal imbalance between production and consumption in the southern states.
Buyers lock in larger volumes for 2027 and 2028
The ACCC’s comparisons track gas supply agreements signed during the first six months of each year, rather than all gas already under contract for a future delivery year. The 51 petajoules therefore measures newly contracted 2027 supply during January through June 2026. It is not a figure for Australia’s total expected gas consumption in 2027 or a tally of all gas previously committed for that year.
That distinction matters when assessing the pace of contracting. A rise in the amount newly agreed several months ahead of delivery points to greater forward purchasing activity, but it does not establish how much additional gas has been produced or will ultimately be available at a particular point on the transmission network. Buyers still depend on producers meeting delivery commitments and the market’s pipelines and storage sites being able to move gas where it is required.
The regulator defines a long-term gas supply agreement as one covering at least 12 months. Such contracts are not necessarily multi-year deals, even when their terms extend into a future calendar year. The price analysis in the ACCC’s published charts covers agreements for at least 0.5 petajoules annually and a term of at least 12 months, making it a measure of the larger wholesale contracting market rather than every small business gas purchase.
Forward agreements can help industrial users budget for production and allow gas retailers to plan purchases against expected customer demand. A customer fixing a commodity price in advance can reduce exposure to a later wholesale price increase, although the overall cost of delivered gas can also depend on transportation, retail margins and the individual contract’s provisions. The ACCC’s reported A$12-to-A$13 range is a wholesale contracting measure, not a forecast for household gas bills.
Long-term prices hold despite international volatility
The ACCC said higher overseas gas prices had not translated into a comparable rise in east coast wholesale prices over the period examined. Most new gas supply agreements entered into between April and June 2026 used fixed prices rather than formulas tied to international commodity benchmarks. That helps explain why the increase in forward contracting was accompanied by broadly steady agreed prices.
Fixed-price contracts and globally linked agreements expose buyers to different risks. Where a contract ties the gas price to an international energy benchmark, a movement in that benchmark can affect the price payable under the agreed formula. A fixed-price agreement instead establishes the commodity price on the terms negotiated at signing. It may still be influenced by international conditions when the supplier and buyer first negotiate, so fixed pricing should not be mistaken for a permanent separation from global markets.
The distinction also limits what can be inferred from the new figures. The ACCC assessed agreements struck through June, using market conditions as they stood in the first half of the year. Its finding of relative price stability does not guarantee that offers made later in 2026 will remain in the same range, nor does it describe the price paid on every spot-market trade. The figures are evidence of what large purchasers secured under those specific agreements, not a promise about future wholesale prices.
Longer-dated purchasing is particularly relevant for commercial and industrial operations that rely on gas as a production input. Predictability can make it easier to plan operating expenses, but a contract also fixes commitments before future demand and market conditions are known. The ACCC did not identify the individual customers behind the newly reported volumes or attribute the increase to a single policy change.
Winter supply remains the harder test
For the first three months of 2027, the ACCC expects the east coast gas system to have enough wholesale supply to meet forecast demand. Its central near-term assessment shows a surplus of 5 petajoules if liquefied natural gas producers export all their uncontracted gas. The January-to-March period generally brings lower Australian gas demand, while Northern Hemisphere winter consumption supports LNG exports.
Even during that relatively comfortable quarter, the regulator cautioned that southern states might need extra gas from Queensland, withdrawals from storage or higher local production in February. The position is more demanding in the following six months. From April through September 2027, southern gas production is expected to fall 64 petajoules short of southern demand, making transport from Queensland and gas held in storage more important during the colder months.
That 64-petajoule figure is a projected gap between southern production and southern consumption, not a prediction that households and industry will necessarily go without that amount of gas. Imports of gas from northern parts of the interconnected east coast market and releases from storage can help bridge the difference. Whether supply is adequate at a particular time depends on where gas is available, how much can be transported and how heavily storage facilities are used through winter.
Australia’s energy market operator has raised similar concerns about the geography of future supply. In its March 2026 Gas Statement of Opportunities update, AEMO forecast that production from legacy southern fields would decline by 46% over five years. The operator said better supply capability and lower demand forecasts had improved the near-term outlook, but stressed the need for production, pipeline and storage projects to be completed on schedule.
The two agencies assess different questions. The ACCC’s latest report looks at contracted volumes, prices and the supply balance for a specific quarter, while AEMO evaluates whether the gas system can satisfy demand over a longer planning horizon, including unusually high-demand days. More forward contracts can make purchasers’ costs and supply arrangements clearer without removing the physical constraints that emerge during a cold spell.
The ACCC’s next gas inquiry report is scheduled for December 2026. It will provide another opportunity to assess how contracting and price conditions have evolved as buyers prepare for 2027 and the southern market approaches another winter dependent on gas arriving from farther north and on stored reserves.
More News
Latest News
View all news- U.S. Commerce Department Finalizes South Korean Hot-Rolled Steel Subsidy Review
- Treasury Names Judy Shelton Counselor on Currency Policy, With China Focus
- U.S. Opens Proposed Gulf Offshore Oil and Gas Lease Sale 4 for Review
- Federal Reserve Reports Rising Household Financial Stress Despite Gains in Income and Wealth
- Canada Employment Falls in September as Unemployment Rises to 6.5%
