
USDA Releases October Crop Supply and Demand Estimates for Global Grain Markets
The October WASDE arrives after USDA recorded a 35% increase in U.S. old-crop corn stocks and reported a sharply smaller wheat harvest.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy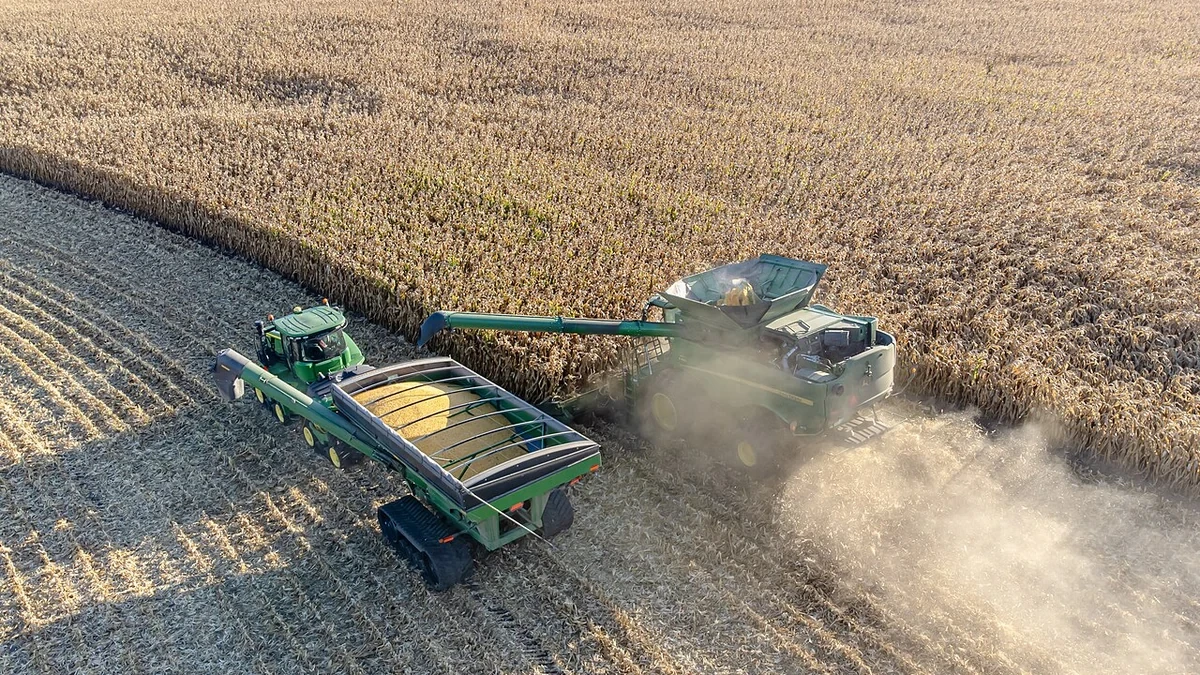
The U.S. Department of Agriculture’s October crop supply-and-demand update puts a fresh focus on global grain availability as buyers assess the American harvest, export prospects and consumption in the 2026/27 marketing year. The October edition of the World Agricultural Supply and Demand Estimates (WASDE) is on the department’s Friday, October 9 release calendar, following a separate grain-inventories report that showed a much larger U.S. corn carryover than a year earlier.
The two releases measure different things. A grain-stocks survey records inventories at a specific date, while WASDE brings together estimates of production, domestic use, imports, exports and the stocks expected to remain at the end of a marketing year. That distinction is particularly important this month because the latest confirmed inventory figures offer a different starting point for assessing future corn supplies.
USDA’s official WASDE release page schedules the October report for noon Eastern time on October 9. Its World Agricultural Outlook Board prepares the monthly estimates with analysts from several USDA agencies, covering wheat, rice, coarse grains and oilseeds in both the United States and overseas markets. The figures are forecasts subject to revision as new harvest, stock and trade information becomes available.
Corn inventories add a new dimension to the supply outlook
On September 30, USDA’s National Agricultural Statistics Service reported that U.S. old-crop corn stocks totaled 2.10 billion bushels on September 1, 2026, an increase of 35% from the same date in 2025. This was a measurement of grain already in storage at the end of the previous marketing year, not a forecast for the crop currently being harvested. The scale of those inventories matters because supplies carried from one season into the next are part of the new year’s available grain.
The distribution of that corn was also uneven. About 787 million bushels were held on farms, 22% more than a year earlier, while off-farm facilities held approximately 1.31 billion bushels, a 44% increase. Commercial elevators, processors and other off-farm storage operators therefore accounted for a substantial share of the additional inventory. Where grain is located can affect local availability and marketing decisions even when the national stock figure looks comfortable.
USDA estimated June-through-August corn disappearance at 3.20 billion bushels, compared with 3.09 billion a year before. The measure reflects the reduction in reported supplies over the period and is not the same as a direct survey of every bushel used for animal feed or industrial processing. Consequently, an increase in stocks cannot by itself establish that all categories of corn demand weakened.
The September stocks report also incorporated modest revisions to last year’s production. USDA revised its 2025 corn crop down by less than 1% and reduced its estimate of 2025 soybean output slightly. These revisions concern an already completed growing season. They can affect the arithmetic carried into subsequent supply-and-demand balances without saying anything definitive about this autumn’s yields.
For grain traders, the distinction between an inventory figure and a marketing-year forecast is practical. A larger carry-in increases available supply if other assumptions remain unchanged, but the amount remaining at the end of 2026/27 will also depend on the size of the new harvest and how much corn is consumed domestically or shipped abroad. Changes in feed requirements, ethanol processing and export demand can counteract, or reinforce, the effect of a bigger starting stockpile.
Wheat production points to a different supply picture
U.S. wheat data published alongside the corn figures suggest different constraints. USDA put all-wheat stocks at 1.85 billion bushels as of September 1, down about 14% from a year earlier. Of that total, 547 million bushels were on farms, a decline of 21%, and roughly 1.30 billion bushels were held off farms, down 10%. These are inventory figures at a particular date, not the projected ending stocks for the 2026/27 wheat marketing year.
The agency’s September 30 Small Grains Annual Summary separately estimated U.S. wheat production for 2026 at 1.53 billion bushels, 23% below the revised 2025 total. Harvested area was estimated at 31.9 million acres, down 15%, and average yield at 48.1 bushels per acre, down 10%. Both the amount of land harvested and production per acre contributed to the decline, which is more informative than treating the smaller crop as the result of a single factor.
Production also differed by class. Winter wheat was estimated at 1.02 billion bushels, down 27% year over year. Other spring wheat totaled approximately 450 million bushels, a 10% decline, and durum wheat was put at 64.8 million bushels, 24% lower. Because wheat classes serve different milling and food markets, shifts in their supplies may not have identical implications for buyers.
The difference between relatively large remaining stocks and weaker current-year production is central to understanding the wheat outlook. Stored grain can bridge supply between harvests, but it does not eliminate the effect of a smaller crop on exportable quantities and next season’s inventory. Importing countries must also consider competing origins and shipping availability, rather than rely on a single U.S. aggregate figure as a guide to world wheat supplies.
The contrast with corn underscores why grain markets cannot be summarized by one national inventory measure. Corn entered the season with more old-crop stocks, while wheat had a markedly smaller U.S. harvest and lower September inventories. Their demand bases, international competitors and marketing calendars also differ. An outlook that is comfortable for one crop does not automatically carry over to another.
Global grain balances turn on production, trade and use
WASDE’s international tables extend the calculation beyond the United States. USDA tracks global supply and use for wheat and rice, as well as coarse grains such as corn, and separately covers oilseeds including soybeans. Production developments in exporting countries feed into the same broad balance as consumption in importing markets. As a result, national harvest news becomes more meaningful when placed alongside expected trade flows and carryover inventories.
The distinction between a crop’s total global output and the volume available for international shipment is especially important. A country may produce a large harvest but use much of it at home, while another market may rely heavily on purchases from abroad. Changes in demand for feed, food or industrial processing can alter the volume that remains for export without an equivalent change in production. For importers, the origin and timing of supply can be as important as the headline world total.
WASDE also joins historical measurements with estimates of what has not yet occurred. This month’s attention to the September 1 U.S. stock readings illustrates the process: recorded inventories provide a more concrete baseline, while future harvest size, consumption and export volumes remain projections. A revision to one part of the balance sheet need not translate into a matching change in ending stocks if other assumptions change at the same time.
The figures in USDA’s September 30 inventory release should therefore not be mistaken for newly verified October WASDE forecasts. The release of fresh estimates gives producers, grain merchants and food-sector buyers a common reference point, but any assessment of a change from September requires the actual October report tables, with the same crop year and units compared on both sides.
USDA’s monthly calendar lists November 10 as the next WASDE release date after October. By then, additional harvest reporting and trade information will provide another opportunity to revise the 2026/27 balances, particularly for crops whose production and shipment estimates remain sensitive to the progress of the marketing year.
More News
Latest News
View all news- Treasury Names Judy Shelton Counselor on Currency Policy, With China Focus
- U.S. Opens Proposed Gulf Offshore Oil and Gas Lease Sale 4 for Review
- Federal Reserve Reports Rising Household Financial Stress Despite Gains in Income and Wealth
- Canada Employment Falls in September as Unemployment Rises to 6.5%
- Australian Gas Buyers More Than Double 2027 Long-Term Contracting, ACCC Says
