Canadian Producer Prices Rise 12.6% Annually, Even as Raw Material Costs Decline in October
Energy products drove the annual increase in factory-gate prices, while cheaper metal ores pulled raw material costs lower from September.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy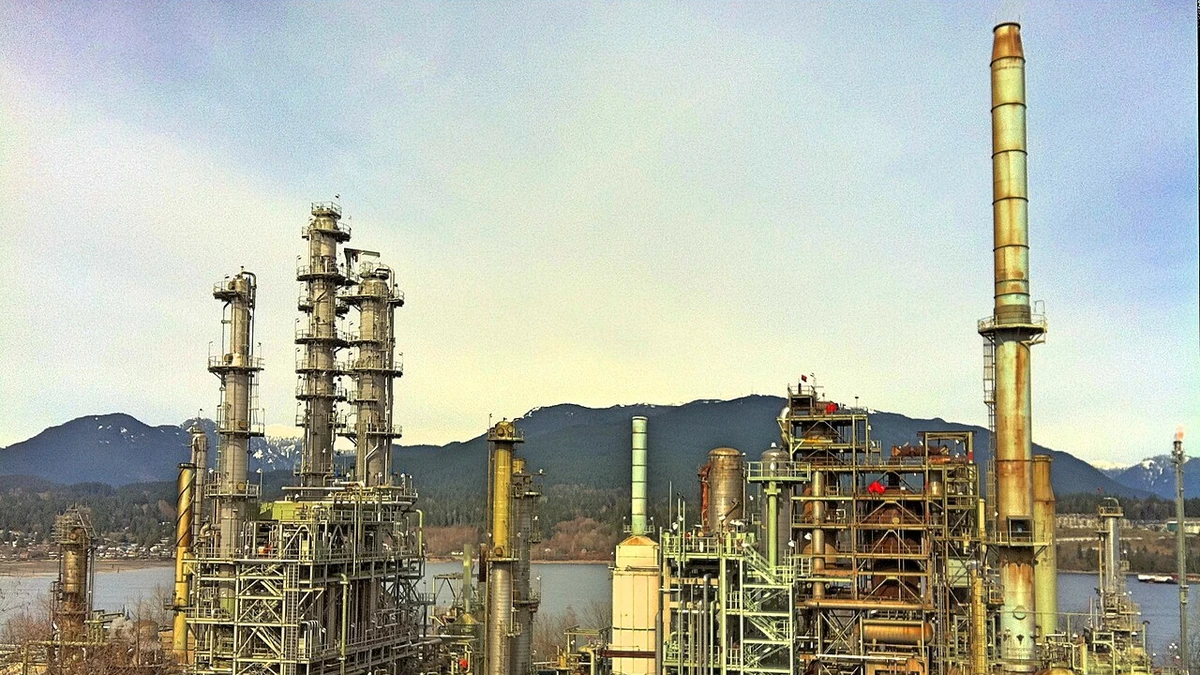
Prices received by Canadian manufacturers were 12.6% higher in October than a year earlier, even as the cost of raw materials eased from September, according to figures released Thursday by Statistics Canada. The Industrial Product Price Index (IPPI) advanced 0.3% month over month, while the Raw Materials Price Index (RMPI) declined 1.0%.
The contrast needs an important qualification: raw material prices were still 23.5% higher than in October 2025. The monthly decline therefore did not erase the much larger rise over the preceding year. Meanwhile, October marked the 25th consecutive month in which the IPPI recorded a year-over-year increase.
Energy was central to the annual increase in factory-gate prices, but the picture varied substantially among products. Statistics Canada’s October producer-price report showed that the IPPI rose only 0.1% from September when energy and petroleum products were excluded. Lower prices for primary metals also offset increases elsewhere in manufacturing.
Petroleum prices remain the main annual driver
Prices for energy and petroleum products increased 1.2% in October, following an 8.6% rise in September. The pace of the monthly gain slowed sharply, but the sector continued to support the broader industrial price index. Statistics Canada identified the conflict between the United States and Iran as a contributing factor behind higher energy and petroleum prices.
Refined petroleum energy products were up 0.7% in October. Within that category, diesel fuel prices rose 1.7%, and light fuel oil prices increased 2.5%. Finished motor gasoline moved the other way, falling 1.2%. That difference helps explain why a higher overall energy index does not mean every fuel product became more expensive during the month.
The annual comparisons were much larger. Diesel fuel prices stood 93.3% above their level a year earlier, finished motor gasoline was up 50.2%, and light fuel oils were 100.3% higher. These are prices for the industrial products covered by the index, not changes in the amounts households paid at retail filling stations. Energy and petroleum products made the biggest contribution to the overall 12.6% annual IPPI increase.
Chemicals also added to October’s monthly increase. Prices for chemicals and chemical products climbed 2.1%, led by a 12.7% rise in plastic resins, their first monthly increase since June. Fertilizers, pesticides and other chemical products were up 3.2%, while paints, coatings and adhesives increased 4.6%. By contrast, the category covering dyes, pigments and petrochemicals declined 3.3%.
Metal prices provided another illustration of the uneven picture. Lower prices for primary non-ferrous and primary ferrous metals restrained the monthly IPPI, even though several processed metal products remained substantially more expensive than a year earlier. Unwrought copper and copper alloys were up 36.5% annually, and unwrought aluminum and aluminum alloys increased 20.0%. Unwrought gold, silver and platinum group metals and their alloys rose 6.3% over the same period.
Cheaper metal ores pull raw-material prices lower
On the input side of the manufacturing process, the biggest source of October’s decline was metal ores, concentrates and scrap. Prices in that group dropped 5.4% from September, more than offsetting an increase in crude energy costs. With crude energy products removed, the raw materials index fell 3.3%, a steeper decline than the 1.0% movement in the full RMPI.
Precious-metal inputs were particularly weak during the month. Prices for gold, silver and platinum group metal ores and concentrates decreased 6.3%. Silver ores, concentrates and mill bullion fell 9.8%, while the comparable gold category declined 3.8%. These input-price changes helped drive the overall decrease, rather than a broad fall across every major raw material group.
Crude energy prices worked against that decline. The crude energy product group rose 2.5% in October after a 14.4% increase in September. Conventional crude oil prices gained 4.1% in the latest month, although synthetic crude oil prices fell 1.9%. The difference within crude oil categories matters because the RMPI represents a basket of inputs purchased by Canadian manufacturers rather than a single benchmark oil price.
Annual raw-material inflation remained elevated despite the monthly reversal. The RMPI’s 23.5% increase from October 2025 followed a 26.6% annual gain in September, according to the latest release. Crude energy products were the largest contributor to October’s annual increase. Conventional crude oil prices were up 65.6% year over year and synthetic crude oil prices rose 79.5%. Excluding crude energy products, the RMPI was 5.1% higher than a year earlier.
Even among precious-metal inputs, the monthly and annual readings pointed in different directions. Gold, silver and platinum group metal ores and concentrates were 10.7% more expensive than a year earlier despite their October decline. A decrease over one month can coexist with a positive annual comparison when prices were higher during much of the intervening period.
What the split means for manufacturers and inflation data
The two indexes measure related but different points in production. The IPPI tracks prices Canadian manufacturers receive for goods as they leave the factory gate. The RMPI measures prices manufacturers pay for key raw materials entering production. Because the underlying product groups, weights and stages of processing differ, a drop in the input index does not require an immediate drop in the output index.
The divergence also cannot establish whether manufacturers’ profit margins improved in October. Some businesses may face higher energy costs while others benefit from cheaper metal inputs, and the indexes do not match a particular company’s input purchases with the prices it charges for its output. They measure price movements across the economy, not the financial results of individual producers.
Neither index should be mistaken for Canada’s Consumer Price Index. Factory-gate prices exclude retail and wholesale distribution costs, transportation beyond the factory gate and indirect taxes such as sales taxes and tariffs. Raw-material prices, by contrast, include charges incurred in bringing inputs to the establishment, including transportation and applicable duties. Statistics Canada notes that tariffs can still affect producers’ selling prices indirectly through input costs or shifts in supply and demand.
The figures are not seasonally adjusted, a detail that matters when interpreting a single monthly change. Statistics Canada has also been phasing in a new survey sample since the September 2026 reference month, using information from its Annual Survey of Manufacturing and Logging Industries. The transition is scheduled to cover all sample strata by the December reference month, while existing-sample index values will not be revised using data from the new sample.
Businesses use producer-price indexes for contract adjustments and industry analysis. Statistics Canada also uses them to separate changes in manufacturing prices from changes in real production. The next release of the industrial product and raw materials price indexes, covering November 2026, is scheduled for December 17.
More News

Latest News
View all news- Spain’s Sánchez Proposes Bank Tax Extension to Raise €1.4 Billion for Housing
- Canada Announces C$248,063 Investment to Restore Nova Scotia Lighthouse and Support Tourism
- New York’s New CPA Licensing Law Takes Effect, Adding 120-Credit Pathway
- Nasdaq Rule Removing CORE FIX Order-Entry References Becomes Operative
- Monte dei Paschi Calls Intesa Takeover Offer Financially Fair but Says It Undervalues Future Potential