
DEUTZ Shareholders Approve Capital Increase for €1.6 Billion FFG Acquisition
DEUTZ shareholders backed the share-based financing step with 99.73% of valid votes cast, clearing a key hurdle for the planned FFG acquisition and a potential 29.9% anchor stake for the seller families.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy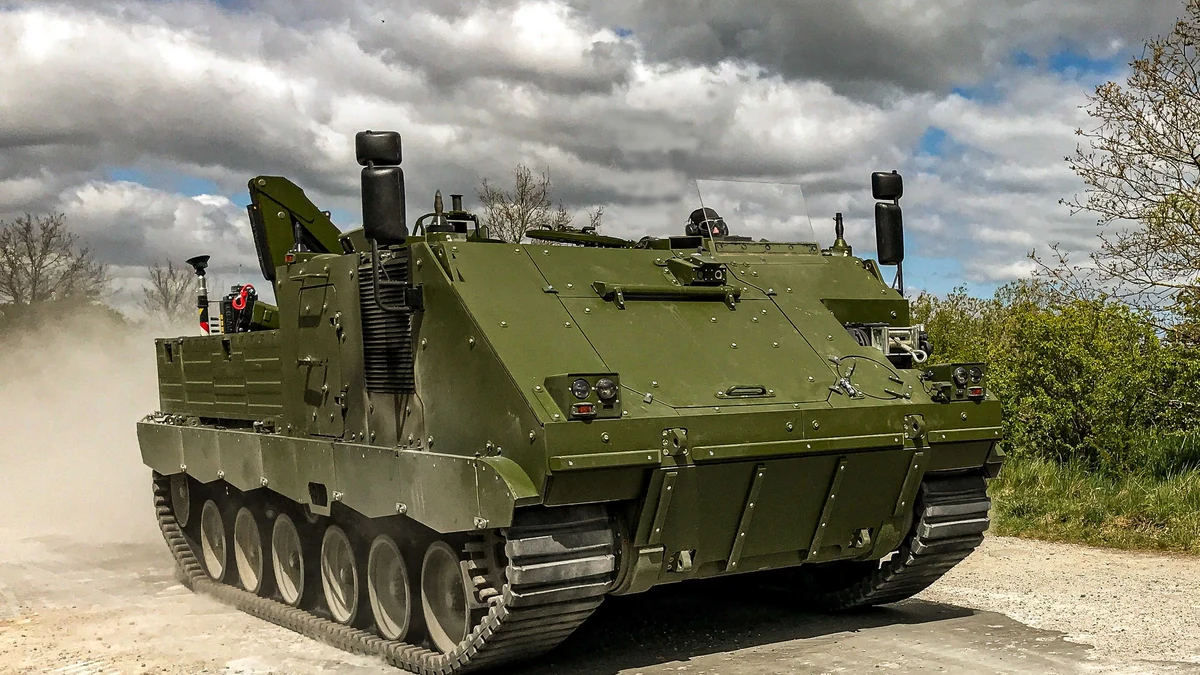
DEUTZ AG shareholders approved a capital increase tied to the company’s planned €1.6 billion acquisition of FFG Flensburger Fahrzeugbau Gesellschaft on Monday, clearing a central financing and ownership step for the German engine maker’s expansion into military vehicles. The approval came at a virtual extraordinary general meeting held on August 24.
The resolution received 63,834,069 votes in favor and 172,170 against, equal to 99.73% support among valid votes cast. Those valid votes represented 41.93% of DEUTZ’s share capital. The vote does not mean the acquisition has closed: DEUTZ says outstanding approvals still need to be obtained, with completion expected in late 2026 or early 2027.
The capital increase gives FFG’s owners a path to a 29.9% DEUTZ stake
DEUTZ said after the meeting that the approved capital increase against a non-cash contribution will be used to help finance the FFG purchase. Under the company’s August 24 announcement, the families that currently own FFG are expected to become long-term anchor shareholders of DEUTZ with a stake of up to 29.9% once the remaining conditions are met and the share issuance is completed.
The €1.6 billion purchase price combines cash and equity. DEUTZ’s July ad-hoc disclosure put the cash component at about €1.0 billion, funded through debt financing already secured from a consortium of international banks, and the equity component at roughly €0.6 billion in newly issued DEUTZ shares. The acquisition agreement also includes further compensation components, including variable elements.
The mechanics approved by shareholders are more detailed than the headline financing split. DEUTZ currently has 152,638,105 shares outstanding. In the base scenario, the company is authorized to issue 65,105,268 new shares to the FFG sellers in exchange for part of their FFG holdings. The authorization can rise to as many as 71,615,796 new shares if DEUTZ first carries out a separate cash capital increase and the sellers exercise their contractual right to preserve a post-issuance holding of up to 29.9%.
Existing shareholders do not have subscription rights to the new shares issued for the FFG contribution. The new stock is reserved for the four seller entities identified in the meeting notice, which will transfer part of their FFG ownership to DEUTZ in exchange. DEUTZ will buy the remainder of FFG for cash. The extraordinary meeting notice specifies a cash consideration of about €1.03 billion for those remaining shares, alongside the additional compensation components set out in the acquisition agreement.
A second resolution at Monday’s meeting also passed, with 99.95% of valid votes cast. It allows DEUTZ to shorten or waive the existing notice period when a supervisory board member resigns. DEUTZ has separately said the FFG owner families are aiming to take two seats on its supervisory board after the acquisition is completed, while the board’s parity-based structure will remain in place.
FFG would add a much larger defense business to DEUTZ
FFG is a Flensburg-based producer and service provider for wheeled and tracked military vehicles. Its work spans manufacturing, modernization, maintenance and platform development. On its official website, FFG describes itself as a systems house serving customers in more than 40 countries and covering the chain from development and design through production, maintenance and after-sales support.
DEUTZ says FFG employs more than 1,100 people across nine sites and generated about €760 million of revenue in 2025. Orders on hand exceed €1.9 billion, according to DEUTZ’s August 24 release. The target company makes and supports armored recovery vehicles, infantry fighting vehicles, personnel carriers and other special-purpose platforms, and it also participates in multinational NATO armaments programs.
The acquisition would therefore change the scale of DEUTZ’s defense activities rather than simply add another engine customer. DEUTZ plans to make FFG the core of its Defense business unit while keeping the company operationally independent. The industrial rationale is to combine FFG’s vehicle and platform expertise with DEUTZ’s propulsion systems, industrial production capabilities and service network.
FFG’s scale is large against DEUTZ’s current group results. DEUTZ reported €1.12 billion of revenue in the first half of 2026, up 10.7% from a year earlier, while adjusted EBIT rose 43.1% to €79.7 million and the adjusted EBIT margin improved to 7.1%. Its full-year outlook remains €2.3 billion to €2.5 billion of revenue and an adjusted EBIT margin between 6.5% and 8.0%.
Management expects FFG alone to generate well above €1 billion of revenue next year with a margin of more than 20%. Those figures are forecasts rather than completed results, but they explain why DEUTZ is presenting FFG as a new earnings pillar. The company has also said the acquisition should allow it to reach its 2030 goals of €4 billion in revenue and a 10% EBIT margin earlier than previously planned.
The shareholder vote clears one hurdle, not the closing
The German Federal Cartel Office has already cleared the planned acquisition, according to DEUTZ. Monday’s vote removes another major condition because the seller families are due to receive DEUTZ shares as part of the consideration. Other regulatory approvals remain outstanding, and DEUTZ has not moved its expected closing window from late 2026 or the first quarter of 2027.
The sequence matters for current shareholders. The August 24 resolution authorizes the non-cash capital increase, but the shares are not being issued immediately as if the purchase had already completed. DEUTZ says the agreed capital increase will be implemented after the outstanding approvals are obtained as part of the completion sequence, allowing the FFG owner families to become anchor shareholders.
For current shareholders, the financing has two distinct effects as the deal moves toward completion. DEUTZ would add about €1.0 billion of acquisition debt for the cash portion, while the equity portion would materially expand the share count and give the sellers a large continuing interest in the combined business. In return, DEUTZ would acquire a defense company with €760 million of 2025 revenue, a backlog above €1.9 billion and management forecasts for further rapid growth.
The next scheduled financial update from DEUTZ is its statement for the first nine months of 2026 on November 5. Before then, the main acquisition milestone is the receipt of the remaining approvals needed to complete the FFG purchase within the company’s stated late-2026 to early-2027 window.
More from Investing
Latest News
View all news- Strive Buys 1,355 More Bitcoin, Raising Holdings to 26,355 BTC
- UK Help to Save Bonus Payments Pass £300 Million as Government Plans Wider Eligibility
- Bundesbank Says German Economy Is Losing Momentum Temporarily in Third Quarter
- France and Canada Put LNG, Energy and Critical Minerals on Macron-Carney Agenda
- U.S. and China Open New York Economic Talks on Trade, AI and Critical Minerals
