
England Adds 36,000 Social Homes, but Traditional Social-Rent Stock Shrinks
Registered providers held about 4.6 million social housing units at the end of March, with gains in Affordable Rent and low-cost ownership offset by losses in traditional Social Rent homes.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy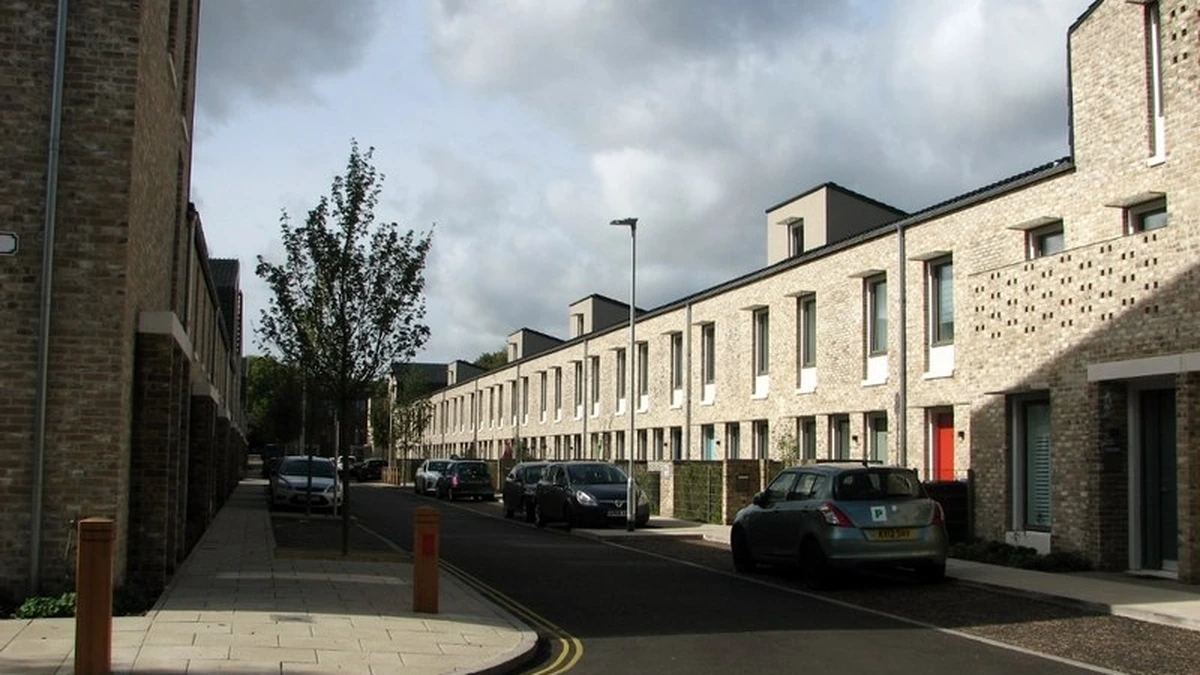
England’s social housing stock rose by about 36,000 units over the year to March 2026, but the number of homes let at traditional Social Rent levels declined, according to figures released Tuesday by the Regulator of Social Housing. The contrasting trends show that growth in the overall stock does not necessarily mean more homes are available at the sector’s lowest regulated rents.
Registered social landlords owned about 4.6 million housing units at the end of March, roughly 1% more than a year earlier. The increase was led by 24,334 additional Affordable Rent units and 13,390 more low-cost home ownership units, while the stock of Social Rent accommodation moved in the opposite direction.
The figures come from the regulator’s annual stock and rent statistics, which cover housing owned by local authorities and other registered providers. They measure the net change in homes held at two reporting dates, not the number of properties newly built during the year. Purchases, disposals, changes in tenure and other stock movements can all affect the totals.
Affordable Rent and ownership homes drive the increase
The mix of tenures matters because the phrase “social housing” covers more than homes let at Social Rent. Under the government’s rent framework, Social Rent is based on a formula that takes account of property values, local earnings and property size. Affordable Rent is a separate category that can generally be set with reference to up to 80% of local market rents, subject to the applicable rules.
Those approaches are not interchangeable for tenants. Social Rent is usually the lower-cost option, while an Affordable Rent property may still cost considerably more than a formula-rent home in the same market. A rise in the Affordable Rent category therefore cannot be treated as an equivalent increase in the supply of homes at traditional Social Rent levels.
Low-cost home ownership is different again. It includes homes intended to make ownership more accessible rather than providing an ordinary Social Rent tenancy. Its inclusion in the regulator’s overall social stock figure is appropriate for the statistical definition, but the 13,390-unit increase should not be described as an expansion of the social rental stock.
Private registered providers, including housing associations, accounted for 88% of the increase in Affordable Rent and 97% of the growth in low-cost ownership stock, the regulator reported. That leaves local authorities with a much smaller share of the additional units in those two categories. The figures do not, on their own, show how many households moved into newly constructed properties.
Across the existing stock, approximately 82% of units were general-needs low-cost rental housing, including Social Rent and Affordable Rent. Supported housing made up about 11%, and low-cost home ownership roughly 6%. The proportions are rounded, and the reported units include both self-contained homes and non-self-contained bed spaces, so the 4.6 million headline is broader than a count of individual houses or flats.
Council-owned Social Rent homes fall despite provider gains
Ownership patterns explain much of the fall in traditional Social Rent. Private registered providers reported a net gain of 7,829 Social Rent units, but local authority registered providers recorded a loss of 9,570. The rise among housing associations and other private registered providers was therefore not enough to offset the reduction in council-owned stock.
The regulator identified Right to Buy sales and other schemes as likely major contributors to the council decline. That is its assessment rather than a breakdown establishing the precise cause of every lost unit. A reduction in council-owned homes is also not automatically the same as a reduction in occupied homes; the stock statistics track the tenure and ownership of units at the reporting date.
The divergence is notable because the two types of landlord have very different roles within the sector. Local authorities owned about 1.6 million social housing units at the end of March, compared with roughly 3 million held by private registered providers. Despite their smaller share of the national total, councils account for a particularly large part of the traditional Social Rent housing portfolio.
This is not a one-year reversal from steady Social Rent growth. The regulator’s preceding annual announcement reported a fall of just over 4,100 Social Rent homes in the year to March 2025, alongside gains of roughly 28,000 Affordable Rent units and 13,900 low-cost ownership units. The latest release suggests that the overall loss of Social Rent accommodation has moderated, but it has not turned into a net increase.
For families seeking a home on the lowest regulated rents, the distinction is practical rather than merely statistical. A new Affordable Rent unit may expand the range of below-market options without offering the same rent as a Social Rent home. Likewise, transferring a property between providers or changing its tenure can alter reported categories without creating another dwelling.
Rent increases and regional differences add context
The report also shows the cost of occupying existing social housing rising. Average weekly net rent for general-needs Social Rent homes increased by 3.2%, or £3.63, between April 2025 and March 2026. The average increase for supported housing let at Social Rent was 4.1%, equivalent to £4.62 a week.
For private registered providers, average weekly general-needs Social Rent was £121.72 across England. Regional averages ranged from £100.31 in the North East to £154.73 in London, underscoring how much the cash cost differs by location even within the same rent category. Council rents were lower on average than private registered provider rents, according to the regulator.
The 3.2% change in the general-needs average was above the 2.7% limit on annual increases for most existing tenancies in 2025-26. That comparison does not establish that landlords breached the limit. The regulator notes that additions to the stock, units covered by exceptions and rents reset within permitted rules when homes are re-let can change the average across the portfolio.
The stock is also unevenly distributed. London accounted for 19.4% of the social housing units owned by registered providers, against 5.4% in the North East. Birmingham was the local authority area with the largest reported volume, at a little over 107,000 units. These are shares of the national stock, not measures of social housing relative to each area’s population or waiting-list need.
The regulator’s survey covered 1,580 registered providers, comprising 230 local authorities and 1,350 private registered providers. Its data offer a consistent picture of ownership, tenure and rents as at March 31 rather than a live measure of properties available to rent today. They also predate the new rent standard that took effect in April 2026.
Future changes in the tenure mix will depend partly on what landlords develop and acquire, as well as what they sell or reclassify. The government’s Social and Affordable Homes Programme for 2026 to 2036 supports new Social Rent and Affordable Rent homes, among other types of housing. The next annual stock returns will provide evidence of whether Social Rent holdings are recovering under that newer funding and policy framework.
More News
Latest News
View all news- Hapag-Lloyd Sets $1,000 Container Rate Increase on Three Americas Services From November 15
- CVS Health Study Finds GLP-1 Medical Savings Do Not Fully Offset Drug Costs at Current Prices
- Bitcoin Falls Near $62,000 as Crypto Selloff Deepens Following U.S. ETF Outflows
- Singapore Central Bank Details SME Financing and Digital-Money Agenda for FinTech Festival
- Novo Nordisk Releases New CagriSema Analysis Showing 25.4% Weight Loss Among Early Responders
