
Gold Futures Retreat Toward $4,190 as U.S. Dollar Strengthens
Gold futures slipped back toward $4,190 as a firmer U.S. dollar weighed on bullion ahead of this week's key U.S. inflation reports.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy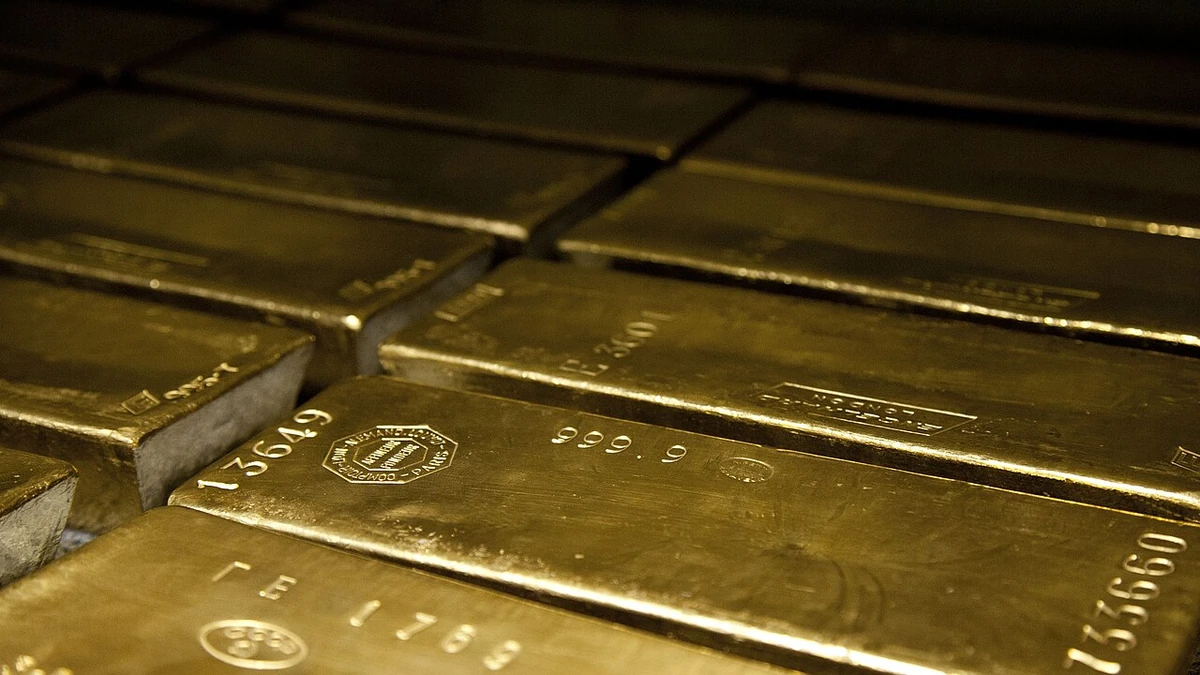
Gold futures pulled back toward the $4,190 level on Monday as the U.S. dollar stayed firm, trimming some of the metal’s recent rebound and keeping traders focused on how much room bullion has to run if U.S. inflation data reinforce a higher-for-longer rates view.
December gold futures were quoted near that level during the session, and Reuters reported they were down about 0.5% at $4,196.20 an ounce in Monday trading. The move came after gold had reached a one-week high late last week, showing that the metal remains caught between longer-run support from geopolitical anxiety and central-bank demand on one side, and near-term pressure from the dollar and interest-rate expectations on the other.
The benchmark CME Group Gold futures market remains the central venue for that price action. Gold futures trade nearly around the clock, which means the contract often reacts quickly to cross-asset shifts in oil, currencies, real yields and macro expectations. Monday’s retreat did not erase the broader rally that has driven gold to historically elevated price territory this year, but it did show how quickly momentum can soften when the U.S. currency strengthens.
Dollar strength remains a direct headwind for bullion
The main macro pressure point was the dollar. The ICE U.S. Dollar Index, known by the DXY symbol, measures the U.S. currency against a basket of major peers and is widely used as the benchmark for broad dollar strength. Reuters reported that the index traded near 102.39 on Monday, close to an 18-month high, as investors continued to favor the dollar amid geopolitical tension and ahead of key U.S. inflation readings.
That relationship matters because gold is priced in dollars. When the dollar rises, gold generally becomes more expensive in other currencies, which can curb some international demand and make the metal less attractive at the margin. The relationship is not mechanically perfect because safe-haven flows can sometimes lift both the dollar and gold at the same time, but on ordinary macro days a stronger dollar is still one of the clearest short-term drags on bullion.
Monday looked like one of those sessions. Gold did not collapse, which suggests underlying support remains intact, but it did lose ground as the currency backdrop turned less helpful. Rising oil prices also complicated the picture by keeping inflation concerns alive. In a market already sensitive to rates, that can push investors to think less about gold as a pure haven and more about the opportunity cost of holding a non-yielding asset when interest rates may stay elevated.
U.S. government bond markets and federal offices were closed for Columbus Day, which likely reduced some normal Treasury-market signaling during the session. Even so, the dollar retained enough momentum to keep pressure on precious metals. That helped explain why the move in gold was a retreat toward $4,190 rather than a decisive break higher after last week’s rebound.
Inflation data could shape the next move
Investors are now looking ahead to the next major macro catalysts: U.S. inflation data. The Bureau of Labor Statistics says the September 2026 Consumer Price Index is scheduled for release on Wednesday, October 14, at 8:30 a.m. Eastern time, and the September 2026 Producer Price Index is scheduled for release on Thursday, October 15, at the same time. Those reports matter because they feed directly into expectations for Federal Reserve policy, Treasury yields and, by extension, gold.
Higher-than-expected inflation readings would tend to support the argument that the Fed cannot pivot quickly toward easier policy. That would usually help the dollar and could keep pressure on gold, especially after a long advance that has left the metal historically expensive. Softer inflation data would not automatically ignite another sharp rally, but it could at least ease some of the pressure coming from rate expectations and the foreign-exchange market.
Gold’s recent behavior shows that this macro balance is still delicate. Reuters reported that spot gold had touched a one-week high of $4,194.36 on Friday before Monday’s pullback, highlighting that the market had already been trying to recover from a weaker spell earlier in the month. That rebound suggested buyers still view dips as opportunities, but the inability to hold onto all of those gains on Monday indicates the market still needs a cleaner rates backdrop to resume a stronger upward trend.
For shorter-term traders, this week is therefore less about long-run gold narratives and more about sequencing. First comes inflation data. Then comes the market’s interpretation of what those numbers mean for the Fed’s next moves. Only after that will gold’s latest retreat be easier to judge as either a routine pause in an ongoing bull market or the start of a deeper consolidation phase.
Gold remains supported, but not immune to macro pressure
None of this changes the bigger picture that has supported bullion this year. Gold has benefited from persistent geopolitical risk, strong official-sector demand in recent quarters, and continuing investor interest in portfolio hedges against inflation, fiscal stress and broader financial volatility. Those themes do not disappear because of one firmer-dollar session.
At the same time, high prices leave the market more vulnerable to setbacks when macro conditions turn less favorable. A metal trading near record territory does not need a dramatic change in the outlook to pull back; sometimes a stronger dollar, firmer yields or a modest shift in expectations is enough. Monday’s move fit that pattern. Gold stayed expensive by any historical standard, but some of the urgency left the market as the U.S. currency gained.
The important distinction for readers is between a reversal and a retreat. The evidence so far points to a retreat. Gold futures moved back toward $4,190, but they remained close to levels that still reflect an unusually strong year for the metal. Unless inflation data, Fed expectations or the dollar take a much sharper turn, the near-term story is one of pressure within strength rather than a clear break in trend.
The next decisive milestone is now straightforward: the CPI release on Wednesday morning, followed by PPI on Thursday. Those reports should provide the clearest near-term test of whether the dollar keeps the upper hand and whether gold can steady after Monday’s slide.
More from Investing
Latest News
View all news- Brent Crude Climbs Above $106 as Middle East Supply Concerns Intensify
- U.S. 30-Year Mortgage Rates Hover Near 7.55% as Housing Borrowing Costs Remain Elevated
- U.S. Gasoline Averages About $4.36 a Gallon, More Than $1 Above a Year Earlier
- Wall Street Trades Mixed as Oil Prices Rise Ahead of Major Bank Earnings
- UK Government Announces More Than £1 Billion in Deals Linked to India Trade Mission
