
Wall Street Trades Mixed as Oil Prices Rise Ahead of Major Bank Earnings
Energy stocks advanced as technology shares weakened, with JPMorgan, Citi, Goldman Sachs and Wells Fargo scheduled to report third-quarter results Tuesday.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy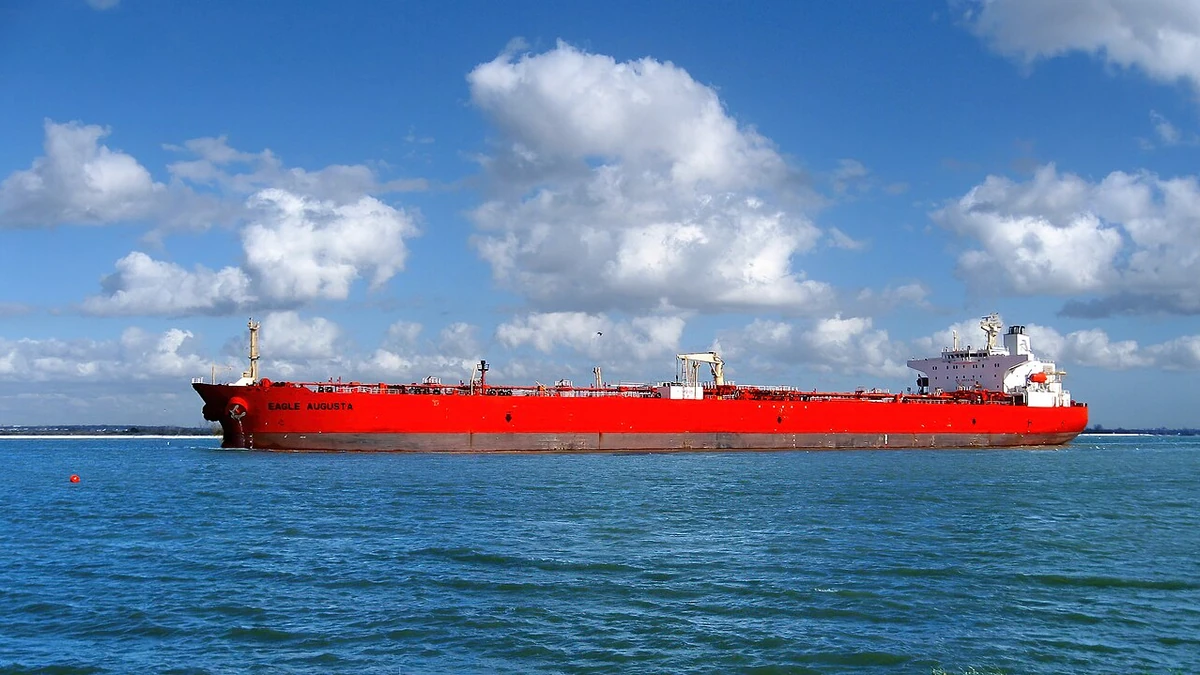
U.S. stocks moved in different directions on Monday as rising crude prices helped energy companies but weighed on the broader market ahead of third-quarter earnings from major banks. The Dow Jones Industrial Average was higher, the S&P 500 edged lower and the Nasdaq Composite lagged as technology shares came under pressure.
At 11:28 a.m. Eastern time on October 12, the Dow was up 236.45 points, or 0.46%, at 51,891.40, according to an intraday market snapshot reported by Reuters. The S&P 500 was down 0.05% at 7,807.50 and the Nasdaq Composite was down 0.33% at 27,275.77. Those figures describe late-morning trading, not the closing levels for the session.
Brent crude futures traded above $106 a barrel as the market weighed renewed Middle East security concerns. The rise in oil added another complication for investors trying to assess corporate profit prospects, but it did not produce a uniform selloff. Energy shares gained as parts of the technology sector retreated, leaving the headline indexes with sharply different performances.
Oil lifts energy stocks as technology loses ground
Monday’s divergence was apparent beneath the index totals. Reuters reported that the S&P 500 energy sector had gained about 1.4% by late morning, compared with a decline of roughly 1% for its information technology sector. The Philadelphia semiconductor index was down about 2.7%. Those contrasting moves mattered more for the character of trading than the small net change in the S&P 500 alone.
Microsoft and Salesforce offered some support to the Dow, with their shares rising about 1.4% and 2.4%, respectively, in the same late-morning report. Because the Dow weights its 30 components by share price rather than market capitalization, gains in individual blue-chip names can give it a different direction from the broader S&P 500 or the more technology-heavy Nasdaq. The mixed session therefore reflected differences among sectors and stocks, not a single verdict on the economy.
Crude prices rose amid concerns about security and shipments in the Middle East. Reuters linked Monday’s market reaction partly to reported attacks at Riyadh’s international airport over the weekend. An attack on an airport is not, by itself, evidence of lost oil production. The relevant market risk is whether further disruption affects export routes, energy facilities or the cost of moving crude; the extent of any such additional disruption remained uncertain.
The supply concern is more substantial than one day’s price change. In its October 6 Short-Term Energy Outlook, the U.S. Energy Information Administration raised its forecast for the average Brent spot price in the fourth quarter to $105 a barrel, $14 higher than its previous monthly forecast. The agency said it still expected Middle Eastern oil production and exports to improve over time through alternative routes and shipping arrangements, even as regional flows remained constrained.
The EIA also reported that Brent spot prices averaged $114 a barrel in September, after attacks on Saudi energy infrastructure disrupted a key export pipeline. That September average and Monday’s futures quote are different measures over different periods; neither should be read as a direct like-for-like comparison. The agency finished the inputs for its October forecast on October 1, so the outlook does not incorporate subsequent events as confirmed facts.
For businesses outside the energy sector, sustained oil-price pressure can affect transport, distribution and manufacturing expenses. Producers of refined fuels face a separate issue: tight inventories. The EIA said East Coast distillate stocks were 32% below their five-year seasonal average in September, a constraint that could keep diesel costs elevated even if crude markets become less volatile. The eventual effect on corporate margins depends on how long prices stay high and how much of the cost companies can pass on.
Major banks begin reporting Tuesday
The next immediate test for stocks is the start of big-bank earnings. JPMorgan Chase, Citigroup, Goldman Sachs and Wells Fargo are all scheduled to report third-quarter results on Tuesday, October 13. JPMorgan said it expects to release its figures at approximately 7 a.m. Eastern time, followed by an 8:30 a.m. earnings call. Wells Fargo also plans a roughly 7 a.m. release, while Citi expects to publish results at about 8 a.m.
Bank of America and Morgan Stanley are due to follow on Wednesday, October 14, according to their investor-relations announcements. That schedule gives investors a concentrated look at large U.S. lenders and Wall Street securities businesses over two mornings. The reports will cover the July-to-September quarter, so Monday’s fresh rise in crude cannot be treated as a direct explanation of results that have not yet been published.
For commercial and consumer lenders, net interest income will be an important figure. Higher interest rates can lift returns on some loans and securities, but they can also raise the cost of attracting and retaining deposits. Loan growth, funding costs and the pace at which assets and liabilities reprice will help explain whether wider market yields are supporting earnings or squeezing margins. The effect differs from bank to bank and cannot be inferred from the direction of Treasury yields alone.
Credit quality will offer a second test. Investors can compare provisions for credit losses with changes in delinquencies and management’s comments about customers’ ability to repay. Elevated fuel costs may put pressure on households and businesses if they persist, but Monday’s crude move does not establish that such stress has already reached bank loan books. The third-quarter figures and executives’ outlooks will provide more useful evidence than a broad assumption about energy prices.
Investment-banking fees and trading revenue are also relevant, particularly for firms with large capital-markets operations. Deal activity, underwriting and client trading do not respond to the economy in exactly the same way as traditional lending. A bank might benefit from stronger securities activity while its deposit franchise faces different pressures, or vice versa. The composition of earnings, rather than the headline profit total alone, will help distinguish those outcomes.
Inflation readings follow, with the Fed meeting later in October
The bank reports arrive just before two closely followed inflation releases. The Bureau of Labor Statistics has scheduled the September consumer price index for Wednesday, October 14, at 8:30 a.m. Eastern time. Its September producer price index is due Thursday, October 15, at the same hour. Neither figure had been released at the time of Monday’s trading.
The distinction between the price series matters. The CPI tracks prices paid by consumers, while the PPI measures prices received by domestic producers. Higher energy costs can reach those measures through different channels and with different delays. Since both releases cover September, they will not directly measure an oil-price rise that occurred on October 12. They can, however, clarify how much price pressure was already present before this week’s move.
Monday also coincided with Columbus Day, when the U.S. bond market was closed under the Securities Industry and Financial Markets Association’s holiday recommendation. Stocks continued trading, but there was no normal cash Treasury-market session to supply a fresh, directly comparable move in benchmark government-bond yields. That makes it particularly important not to treat yields quoted from an earlier session as if they were simultaneous with Monday’s stock prices.
Inflation and borrowing costs are linked to expectations for Federal Reserve policy, which in turn affect company valuations and bank funding conditions. The Federal Open Market Committee is scheduled to meet October 27–28. The upcoming CPI and PPI releases will provide fresh evidence for that discussion, although neither report determines a policy decision on its own.
More News
Latest News
View all news- Gold Futures Retreat Toward $4,190 as U.S. Dollar Strengthens
- IonQ Agrees to Buy Cybersecurity Firm Elisity for Up to $1.3 Billion
- KKR, TotalEnergies to Add $1.2 Billion Solar Portfolio to U.S. Venture
- U.S. 30-Year Mortgage Rates Hover Near 7.55% as Housing Borrowing Costs Remain Elevated
- Wall Street Volatility Gauge Rises as Traders Assess Inflation and Earnings Risks
