
KKR, TotalEnergies to Add $1.2 Billion Solar Portfolio to U.S. Venture
KKR and TotalEnergies plan to add three solar projects in Texas and Ohio to their U.S. joint venture, giving the portfolio another 700 megawatts at a $1.2 billion enterprise valuation.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy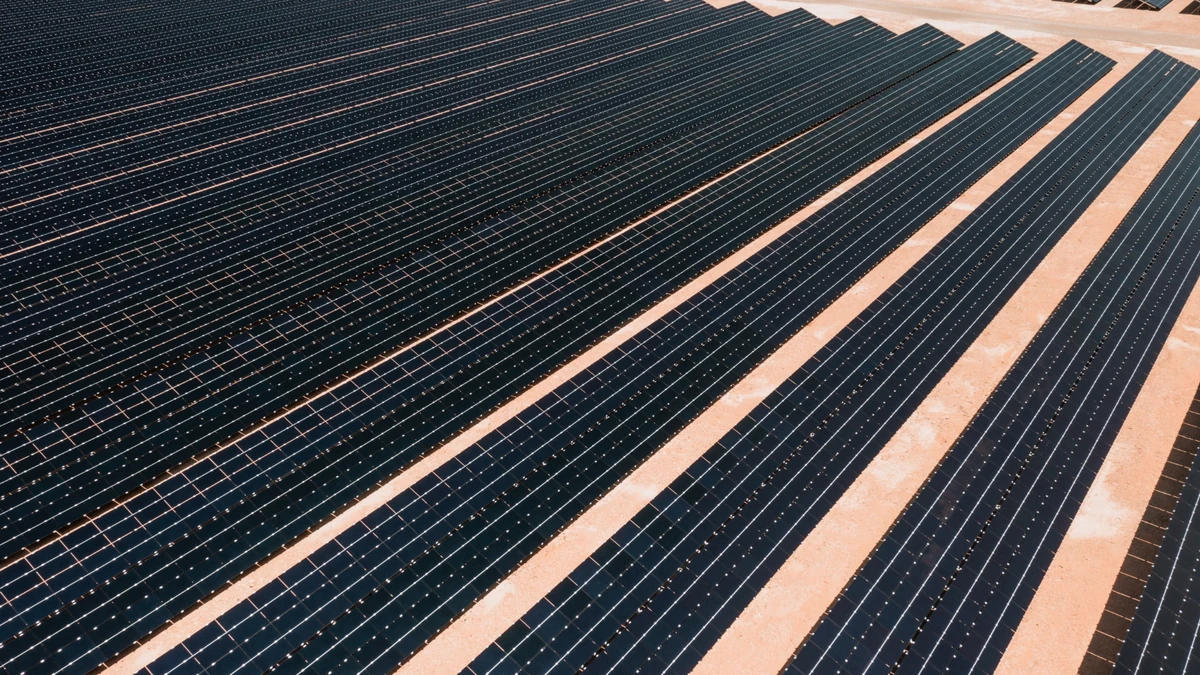
KKR and TotalEnergies have agreed to add a $1.2 billion U.S. solar portfolio to their existing joint venture, expanding a partnership that already held 1.4 gigawatts of renewable capacity in North America. The new agreement covers three utility-scale solar projects in Texas and Ohio with a combined 700 megawatts of capacity, according to the companies.
The addition matters less as a headline-grabbing number than as another example of how large energy companies and private capital are financing renewables. Rather than retaining 100% ownership of every project on its balance sheet, TotalEnergies has been using partial sell-downs and joint ventures to recycle capital into new development while keeping an operating role in the assets. For KKR, the agreement adds more long-lived contracted infrastructure to a platform that was established only last year.
Three solar projects will add 700 megawatts in Texas and Ohio
In separate but matching announcements from KKR and TotalEnergies, the companies said the portfolio consists of three utility-scale solar assets and carries an enterprise value of $1.2 billion. The assets are expected to reach commercial operation by the first quarter of 2027, and the parties expect the agreement to close in 2026, subject to customary conditions.
The releases did not identify the individual projects by name or disclose a separate cash purchase price. What they did make clear is that the valuation refers to the portfolio on an enterprise-value basis, a distinction that matters because enterprise value is not the same thing as the equity check one partner writes to another. The companies also said electricity from the assets has already been sold to third parties or will be marketed by TotalEnergies, suggesting the projects enter the venture with a commercialization path already in place.
TotalEnergies said it will continue to operate the assets after completion. That keeps the industrial logic of the partnership intact. KKR supplies capital and long-duration infrastructure appetite, while TotalEnergies continues to bring operating expertise, project management and power marketing capabilities. If the addition closes as planned, the venture’s held capacity would rise from 1.4 gigawatts to about 2.1 gigawatts.
Texas and Ohio are also telling locations. Texas remains one of the country’s largest utility-scale solar markets, while Ohio gives the portfolio some geographic spread outside the Sun Belt. Neither company said how the 700 megawatts are split between the two states, nor did they describe whether all three projects are already under construction. That leaves some room for uncertainty around project timing, even though the broad commercial-operation window is now on the record.
The latest agreement builds on a 2025 North American solar deal
This is not a new partnership from scratch. The current venture was created from a 2025 agreement under which TotalEnergies sold a 50% stake in a 1.4 gigawatt North American solar portfolio to insurance vehicles and accounts managed by KKR. In that earlier deal, TotalEnergies said the portfolio was valued at an enterprise value of $1.25 billion and included six utility-scale solar assets totaling 1.3 gigawatts, plus 41 distributed-generation assets totaling 140 megawatts, primarily in the United States.
TotalEnergies also said at the time that the stake sale, together with bank refinancing then being finalized, was expected to deliver $950 million to the company at closing. In its fourth-quarter 2025 results, the company later described the sale to KKR as completed. That background helps explain why Monday’s announcement is better read as an expansion of an operating capital model rather than an isolated portfolio deal.
From a financing perspective, the structure is straightforward. TotalEnergies develops or owns renewable assets, brings in a capital partner once projects are operating or nearing operation, keeps half ownership and continues to run the portfolio. That approach can lower capital intensity, recycle funds into future projects and still let the company preserve exposure to long-term cash generation from electricity assets. For KKR, it offers a route into large-scale renewable infrastructure without having to build a development platform alone.
The two announcements also point to an important common feature between the 2025 portfolio and the newly added one: the electricity has either already been sold or will be marketed by TotalEnergies. That reduces one of the biggest risks in utility-scale renewables, namely how and at what price the power will be sold over time. The companies did not disclose counterparties, contract tenor or how much of the output is already contracted, but the marketing detail signals that revenue planning is central to the venture’s design.
The agreement fits both companies’ broader energy strategies
For TotalEnergies, the deal sits squarely within its integrated power strategy, which pairs renewable generation with trading, supply and power marketing. The company has repeatedly used farm-down structures in renewables to unlock value from projects after development while retaining enough ownership to benefit from future operating cash flows. Monday’s agreement follows that pattern closely. Rather than exiting the assets, TotalEnergies is enlarging a structure in which it remains both co-owner and operator.
KKR, meanwhile, has been an active investor in energy transition infrastructure through its global infrastructure platform. In the 2025 announcement that created the venture, KKR said it had committed more than $23 billion to energy transition investments to date. The new portfolio addition does not change that headline figure in itself, but it does show that the firm is continuing to scale exposure to contracted or marketable renewable assets in the U.S. power sector.
The strategic appeal for both sides is easier to understand when the timing is considered. Utility-scale solar projects require large up-front capital commitments, but once they move toward operation they can be a good fit for infrastructure investors seeking predictable, long-duration returns. An oil and gas major trying to build a large electricity business does not necessarily want to warehouse every completed asset forever on its own balance sheet. A private capital partner can fill that gap, especially when the operator already has a pipeline and commercial capabilities.
What remains undisclosed is just as important for readers to note. The companies did not name the three projects, publish asset-level capacity figures, disclose the venture’s financing structure, or say whether any debt will sit at the project or holding-company level. They also did not spell out the precise ownership path by which the assets are being transferred into the venture. Even so, the core facts are clear: three U.S. solar projects in Texas and Ohio are being added to the 50-50 partnership at a $1.2 billion enterprise valuation, the assets are expected to be online by the first quarter of 2027, and closing is targeted for 2026.
The next concrete milestones are therefore not abstract. First, the parties need to complete the deal under customary closing conditions. After that, the focus shifts to construction and commissioning, with commercial operation of the three projects expected by the first quarter of 2027.
More from Investing
Latest News
View all news- Brent Crude Climbs Above $106 as Middle East Supply Concerns Intensify
- U.S. 30-Year Mortgage Rates Hover Near 7.55% as Housing Borrowing Costs Remain Elevated
- U.S. Gasoline Averages About $4.36 a Gallon, More Than $1 Above a Year Earlier
- Wall Street Trades Mixed as Oil Prices Rise Ahead of Major Bank Earnings
- UK Government Announces More Than £1 Billion in Deals Linked to India Trade Mission
