Union Pacific Third-Quarter Profit Rises 16% to $2.1 Billion as Freight Volumes Grow
Operating revenue climbed 15% to $7.2 billion, helped by higher fuel surcharges and pricing, while the railroad faced a sharply larger fuel bill.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy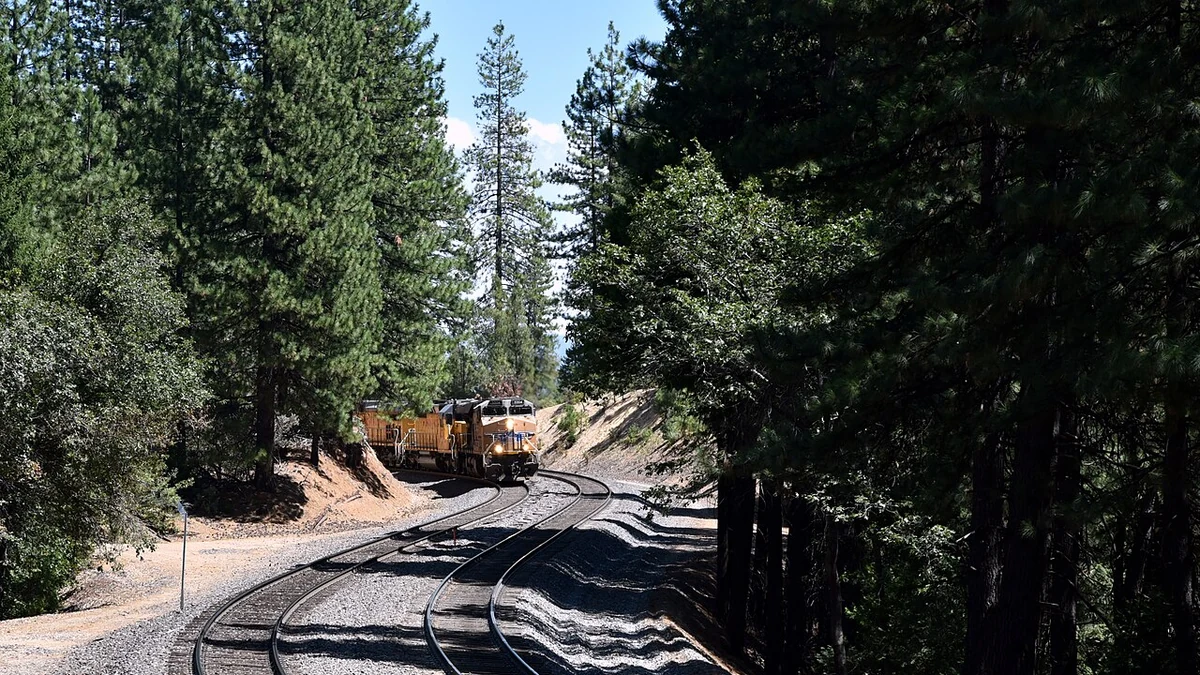
Union Pacific’s third-quarter profit increased 16% as the railroad hauled more freight and collected higher revenue, although a sharp rise in fuel costs left only a narrow improvement in its reported operating ratio. The company earned $2.076 billion in the three months ended September 30, 2026, compared with $1.788 billion a year earlier, according to its earnings filing released October 22.
Diluted earnings per share rose to $3.49 from $3.01. Excluding specified acquisition-related expenses, Union Pacific reported adjusted earnings of $3.53 a share, up 15% from $3.08. Operating revenue climbed 15% to $7.197 billion from $6.244 billion, while the number of revenue carloads increased 6% to 2.293 million.
The distinction between traffic growth and revenue growth is important to the quarter. Higher fuel surcharges contributed to the sales increase, alongside stronger core pricing and additional shipments. Those surcharges are not the same as a comparable increase in underlying freight demand. Union Pacific said freight revenue excluding fuel surcharge grew 6%, matching the reported rise in carloads. The details appear in the railroad’s October 22 earnings filing.
Intermodal and industrial traffic led the increase
Shipment growth was uneven across Union Pacific’s major freight categories. Its premium business, which includes automotive and intermodal transportation, handled 1.158 million carloads or units, 9% more than a year earlier. Within that group, intermodal traffic increased 11% to 956,000 containers and trailers, making it a central source of the railroad’s additional volume.
Industrial traffic rose 6% to 606,000 carloads. Metals and minerals shipments increased 8%, while energy and specialized markets grew 7%. The bulk business, by contrast, was essentially flat at 529,000 carloads. Grain and grain products increased 5%, but coal and renewables declined 3%. That split shows why a network-wide 6% volume gain should not be read as a uniform improvement in every market Union Pacific serves.
The revenue picture also varied by business. Industrial freight revenue rose 14% to $2.509 billion, premium freight revenue increased 21% to $2.188 billion, and bulk freight revenue was up 10% to $2.116 billion. Together, the three groups produced $6.813 billion in freight revenue, compared with $5.927 billion in the third quarter of 2025.
Intermodal freight revenue grew 27% to $1.517 billion, considerably faster than its 11% increase in volume. Average revenue per intermodal unit was $1,586, up from $1,393 a year earlier. Such figures reflect the amount billed per shipment, including effects from surcharges and mix, so they should not be treated as a direct measure of core freight-rate increases.
Across the railroad, average freight revenue per car rose 8% to $2,971. More carloads and higher receipts per shipment supported revenue, but the broader 15% sales increase also came with a much larger fuel bill.
Fuel expenses absorbed much of the operating benefit
Fuel expense reached $1.040 billion in the quarter, compared with $616 million a year earlier, a 69% increase. That was the most striking cost movement in Union Pacific’s income statement. Compensation and benefits increased 4% to $1.264 billion, while purchased services and materials rose 9% to $746 million.
Total operating expenses increased 15% to $4.254 billion, almost exactly in line with the revenue growth rate. Operating income nevertheless rose 15% to $2.943 billion. Union Pacific’s reported operating ratio, the share of revenue consumed by operating expenses, edged down to 59.1% from 59.2%. A lower ratio is better, but the change amounted to just 10 basis points.
On an adjusted basis, the picture was less favorable. The operating ratio rose to 58.8% from 58.5%, a deterioration of 30 basis points. The adjusted measure excludes $22 million of acquisition-related expense this quarter, compared with $41 million in the year-earlier period. Adjusted earnings are useful for comparing results, but they are non-GAAP figures and do not replace the reported results.
Union Pacific said higher fuel prices adversely affected its operating ratio by 140 basis points. The fuel surge therefore helps explain why strong freight and operating-income growth did not translate into a large improvement in margins. The company also warned that elevated fuel prices would continue to challenge its reported operating ratio, even as it sought improvements in its core business.
Several network measures moved in a better direction. Freight car velocity rose to 228 daily miles per car from 226, and average time spent in terminals fell to 19.9 hours from 20.4. Average train length increased 2% to 9,969 feet. The railroad’s fuel consumption per thousand gross ton-miles improved 2%, and workforce productivity, measured as car miles per employee, advanced 5%.
Not every service measure improved: the intermodal service-performance index declined to 92% from 98%, according to the company’s operating statistics. The data point complicates an otherwise positive set of operational trends and matters because intermodal shipments supplied much of the volume growth.
Outlook holds as Norfolk Southern review continues
For the full year, Union Pacific maintained its expectation for high-single-digit growth in reported earnings per share. It also reaffirmed an objective of price gains in dollar terms exceeding inflation and said its freight-service outlook remained strong despite a mixed economic forecast. Those are management expectations, not results already achieved.
The company updated its capital plan to $3.5 billion. Cash generation provides some context for that spending: operating cash flow in the first nine months of 2026 was $8.302 billion, up from $7.065 billion a year earlier. Union Pacific reported $2.834 billion in capital investments during the period and paid $2.484 billion in dividends.
Its company-defined free cash flow reached $2.362 billion for the first nine months, compared with $1.856 billion a year earlier. Union Pacific calculates that measure by subtracting cash used in investing activities and dividends paid from operating cash flow. Because it is a non-GAAP measure, it is best considered alongside the underlying cash-flow figures rather than in isolation.
The earnings release also comes as Union Pacific pursues its proposed acquisition of Norfolk Southern. Chief Executive Jim Vena referred to the next stages of the Surface Transportation Board’s review, which concerns a proposed merger of the railroads’ operations. The pending acquisition is a separate corporate development from the freight and financial performance reported for the quarter.
The Surface Transportation Board’s merger docket lists an August decision that restarted consideration of the revised application and an October decision addressing late-filed notices. The agency’s earlier actions did not decide whether the merger should be approved. For now, Union Pacific’s reported freight growth and fuel-sensitive margins describe its existing railroad business, not the performance of a merged network.
More from Investing
Latest News
View all news- U.S. Leading Economic Index Was Flat in September as Growth Tilts Toward Business Investment
- U.S. Jobless Claims Fall to 194,000 as Layoffs Remain Historically Low
- Kansas City Fed Releases October Manufacturing Survey as Factories Face Cost Pressures
- Census Bureau Releases New Business Conditions Data Covering U.S. Employers
- BEA Expands State-Level R&D Economic Statistics With New 2024 Estimates