U.S. Gasoline Prices Fall to $3.84 a Gallon, but Diesel Remains Above $6
Regular gasoline is nearly 20 cents cheaper than a week ago, but diesel still costs about $2.20 more per gallon, keeping fuel pressure on freight and delivery businesses.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy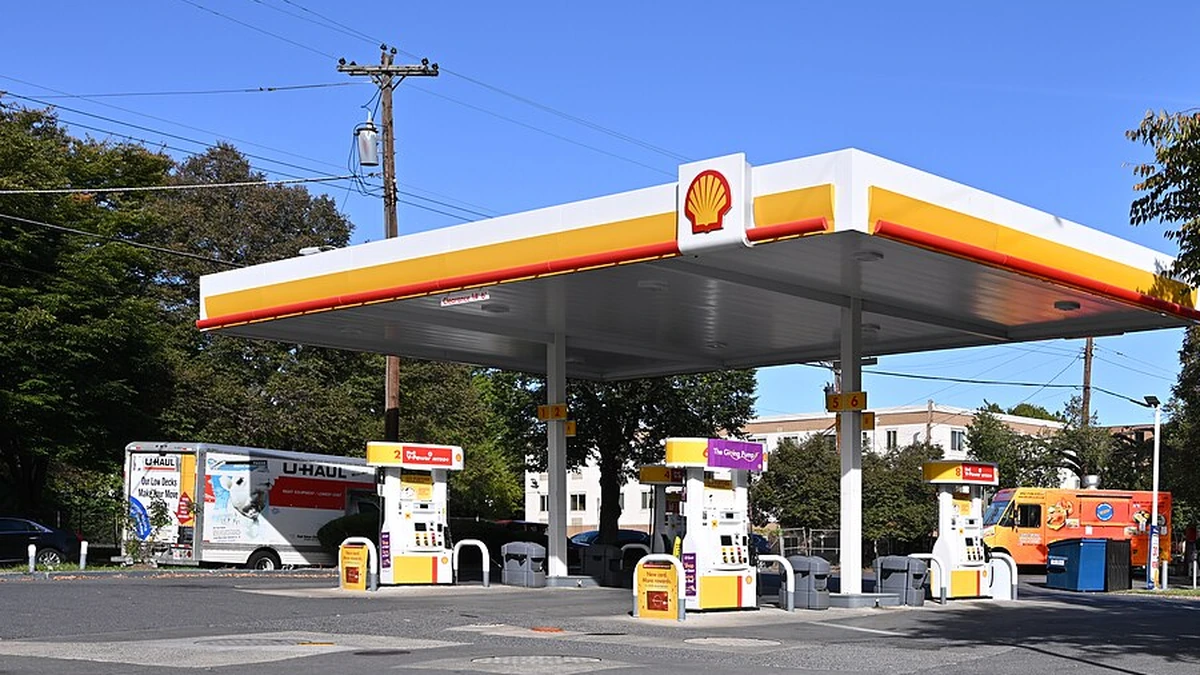
U.S. gasoline prices fell to an average of $3.84 a gallon on Saturday, extending a retreat that has brought some relief to drivers after months of expensive fuel. Diesel also became cheaper, but at $6.04 a gallon it remained far above the price of regular gasoline, leaving transportation businesses exposed to a different set of fuel costs.
AAA’s November 14 national averages put regular gasoline at $3.8406 a gallon and diesel at $6.0366. Regular was about 20 cents cheaper than a week earlier, while diesel had declined about 17 cents. The gap between the two fuels was still roughly $2.20 a gallon, a reminder that falling pump prices are not translating into the same level of relief across the U.S. fuel market.
The latest figures extend a decline that took regular gasoline below $4 earlier in the week for the first time since July. Even after the drop, both fuels cost considerably more than at the same point last year, according to AAA’s daily national price survey.
Lower crude prices and autumn demand ease gasoline costs
Regular gasoline has declined from $4.0371 a gallon a week ago and $4.3333 a month ago. That amounts to a weekly reduction of 19.65 cents and a drop of more than 49 cents over the month. The direction matters for household budgets, although the starting point was high enough that the recent decline has not restored last year’s fuel costs.
AAA attributed the move below $4 to a mix of lower crude oil prices, the switch to less expensive winter-blend gasoline and weaker autumn demand. Summer-grade fuel is generally more costly to produce because of its seasonal requirements. Driving demand also tends to ease after the summer travel period, reducing pressure on the supply of gasoline available to retailers.
In its November 12 update, AAA said U.S. gasoline demand had edged down from 8.80 million to 8.76 million barrels per day in the latest weekly Energy Information Administration data. A modest change in demand is only one part of the pricing picture, but it helps explain why the market can soften even when fuel remains expensive by historical standards.
The Energy Information Administration’s separate weekly retail survey also showed the decline, though on an earlier measurement date. Its November 9 reading put regular gasoline at $3.995 a gallon, down from $4.153 the previous week. That weekly survey and AAA’s more recent daily average should not be treated as simultaneous quotes: they use different reporting schedules and can show different prices as the market moves.
For drivers, the weekly change is noticeable without being a complete reversal. At the current national average, 15 gallons of regular gasoline cost about $57.61, versus roughly $60.56 at the price recorded a week ago. The same purchase would still cost about $11.40 more than at AAA’s year-earlier average of $3.0804 a gallon.
Diesel remains expensive despite its own decline
Diesel’s national average fell from $6.2075 a week earlier to $6.0366, according to AAA, and was down from $6.2997 a month ago. Its retreat has been real, but much smaller in dollar terms than the increase over the past year. Diesel averaged $3.7690 a gallon at the same point in the previous year, putting the current price about $2.27 higher.
The price gap with regular gasoline has widened sharply over that period. A year earlier, diesel carried a premium of about 69 cents a gallon. It now costs nearly $2.20 more. That difference is particularly relevant to trucking fleets, delivery services, farm operators and other businesses that use diesel rather than gasoline. Lower gasoline prices do not directly reduce those businesses’ fuel bills.
Diesel has eased from AAA’s recorded national high of $6.5276 a gallon on September 22, but the current reading remains within about 49 cents of that peak. It also leaves considerable room for costly fuel surcharges and pressure on operating margins where transport providers cannot quickly pass higher expenses to customers.
The underlying fuel markets have not moved in lockstep. Diesel is produced from distillate fuel oil, a category also connected to heating-fuel demand. That makes diesel sensitive to refinery output, distillate inventories, industrial and transport use, and the international market for refined products. Changes in crude oil prices influence both gasoline and diesel, but they do not determine the retail spread by themselves.
In its November Short-Term Energy Outlook, the Energy Information Administration described continued constraints on global refined-fuel supplies and warned that disruptions could sustain elevated refinery margins. The agency forecast an average U.S. retail diesel price of $5.03 a gallon for 2027, higher than the $4.49 it had projected one month earlier. These are estimates for the full year, not a prediction that diesel will reach that level on a particular date.
The price divide varies by region and may outlast this week’s drop
National averages conceal major differences between local fuel markets. The EIA’s November 9 weekly survey showed regular gasoline at $3.481 a gallon on the Gulf Coast, compared with $5.110 on the West Coast. In the same survey, diesel averaged $5.741 on the Gulf Coast and $7.110 on the West Coast. Those regional readings predate AAA’s November 14 national figures, but they illustrate how geography affects the amount of relief motorists and commercial drivers experience.
Refining capacity, distribution costs, taxes and regional fuel specifications all contribute to the variation. A falling U.S. average therefore does not mean that every station has cut prices at the same pace. Differences are also significant for diesel-intensive businesses with routes or operations concentrated in higher-cost regions.
For households, the immediate benefit is straightforward: each gallon of regular gasoline now costs less than it did last week. For freight operators, the remaining diesel premium is large enough to affect fuel spending across an entire fleet. The size and timing of any impact on the prices consumers pay for delivered goods depend on contracts, fuel-surcharge arrangements and other costs; the pump-price gap alone cannot establish a specific increase in retail prices.
The EIA’s November outlook projected that gasoline would average $3.73 a gallon in 2027, up from its October forecast of $3.56, even as it expects prices to fall from this year’s levels. Both gasoline and diesel forecasts were revised higher because the agency expects constrained global refined-fuel supplies to persist. That forecast offers a longer-term reference point, but the near-term path remains dependent on crude prices, refinery conditions and demand.
The next scheduled EIA weekly gasoline and diesel price release is November 17, followed by its next Short-Term Energy Outlook on December 8. Together, those updates will provide fresh evidence on whether gasoline continues to ease and how quickly diesel’s much larger premium narrows.
More News
Latest News
View all news- Nasdaq Expands Public Disclosure of Disciplinary Cases as $10,000 Threshold Is Removed
- Switzerland’s New Payment Standards and QR-Bill Rules Take Effect
- Singapore Issues First International Carbon-Credit Project Authorization Under Rwanda Agreement
- Canada Concludes Philippines Free-Trade Talks and Nears Agreement With ASEAN
- U.S. Producer Prices Rise 6.5% Annually in October, Fastest Pace Since November 2022