
Wall Street Volatility Gauge Rises as Traders Assess Inflation and Earnings Risks
Cboe’s VIX edged higher Monday as traders faced an upcoming U.S. inflation report and the first major third-quarter bank results, with the reading still below recent volatility peaks.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy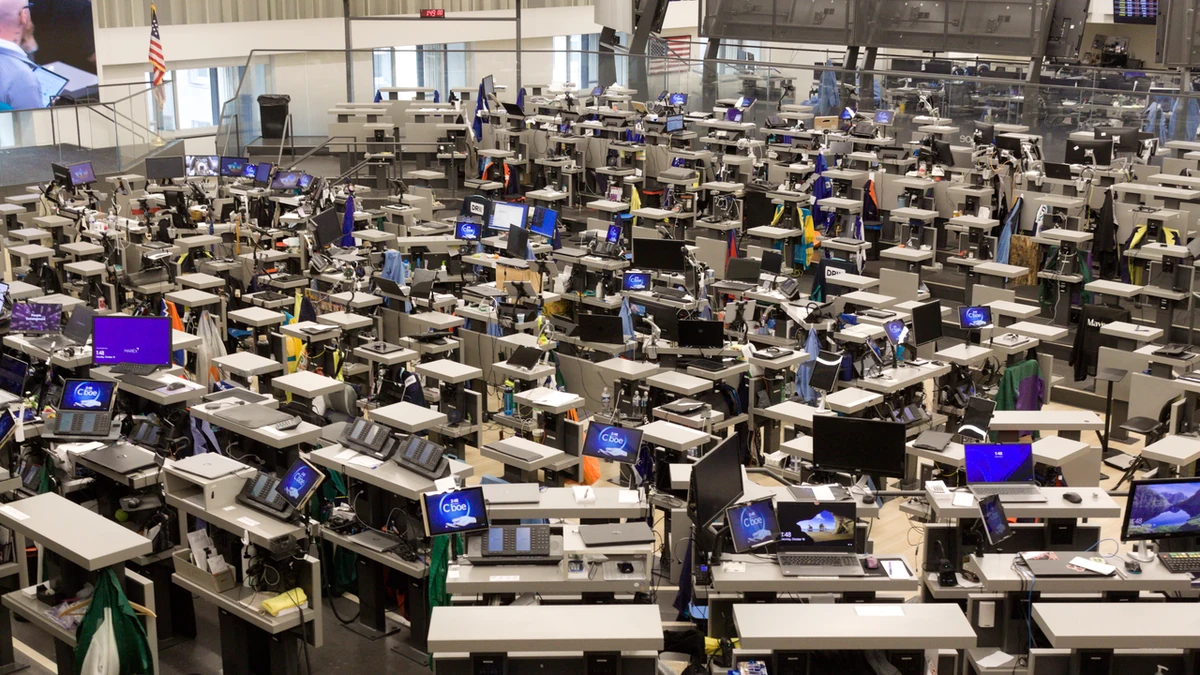
Wall Street’s closely watched volatility gauge rose Monday as traders approached a week of inflation data and major bank earnings. The Cboe Volatility Index, or VIX, stood at 15.21 in an intraday reading available during the early U.S. afternoon, up 0.37 point, or 2.49%, from Friday’s close of 14.84. The reading was not a final closing value.
The increase was modest in level, but it showed that expected market turbulence had picked up from the previous session. It arrived ahead of Tuesday’s first major third-quarter bank reports and Wednesday’s September consumer inflation figures, two events capable of changing investors’ assessments of corporate profits and interest rates.
Monday’s rise should not be confused with a forecast that U.S. stocks will fall. The VIX measures expected volatility rather than the direction of the S&P 500, and a single intraday reading cannot establish which of several risks prompted demand for options protection.
A higher VIX meets an unusually quiet bond-market session
Cboe derives the VIX from prices of S&P 500 index options, producing a measure of expected price swings over roughly the next 30 days. A rise generally means those options imply greater future fluctuations, not that such fluctuations are certain to occur. Cboe’s VIX market data and methodology overview provide the basis for the index and its latest reported levels.
The details of Monday’s trading reinforce the distinction. The gauge opened at 15.39, above Friday’s 14.84 close, before easing to the 15.21 reading. It therefore remained higher on the day despite slipping from its opening level. Cboe’s dashboard also put its 52-week range at 13.38 to 35.30, offering useful perspective on the size of the move without suggesting that a low reading removes market risk.
The session had another unusual feature. U.S. stock trading continued on Columbus Day, but the Securities Industry and Financial Markets Association recommended a full holiday closure for U.S. fixed-income trading. That left investors without the usual stream of regular-session bond-market price changes alongside equity moves. The holiday does not, by itself, explain the VIX increase; it is a limitation when drawing broad conclusions from one session’s cross-market behavior.
Options prices reflect traders’ willingness to pay for exposure or protection across a range of possible outcomes. They can respond to scheduled economic releases, changes in the perceived distribution of risks, or adjustments to positions. The VIX captures the resulting market-implied volatility at a point in time. It does not separate those motives or assign an exact share of Monday’s change to inflation, earnings or any other event.
September inflation data could reshape the rate outlook
The next major U.S. inflation report is scheduled for Wednesday, October 14, at 8:30 a.m. Eastern, when the Bureau of Labor Statistics will publish September’s Consumer Price Index. The agency’s official October release calendar also lists September producer prices for Thursday, October 15. Neither release had been published as of Monday’s trading session.
August’s CPI report explains why the September reading matters. The headline index increased 0.4% on a seasonally adjusted monthly basis, compared with a 0.1% gain in July. Consumer prices were 3.4% higher than a year earlier. Excluding food and energy, prices rose 0.3% during August and 2.4% over 12 months. The annual core rate had eased from 2.5% in July, even as the headline monthly increase accelerated.
Energy was one source of that tension. The BLS reported a 2.1% rise in its energy index in August, including a 3.9% increase in gasoline prices, which accounted for more than one-third of the monthly gain in the overall CPI. Those figures are already known; the September data will establish whether that earlier contribution persisted, weakened or was outweighed by other categories.
The Federal Reserve has recently shown why price readings carry particular weight. At its September 16 meeting, the Federal Open Market Committee raised its target federal funds rate by a quarter percentage point to a range of 3.75% to 4%, saying inflation remained elevated. A stronger-than-expected CPI reading could complicate the outlook for borrowing costs, while a softer one could change how investors assess further policy action. Neither outcome can be treated as established before the release.
For stock valuations, the connection is practical. Interest-rate expectations affect the yields investors demand and the present value they place on future earnings. That can matter especially when equity prices already reflect expectations of sustained profit growth. The inflation report may also shed light on costs faced by businesses and households, although a single monthly result will not settle the broader inflation trend.
Bank earnings arrive first, with credit and margins in focus
Major banks will begin supplying fresh operating evidence before the CPI publication. JPMorganChase has scheduled its third-quarter results for about 7 a.m. Eastern on Tuesday, October 13, followed by an 8:30 a.m. earnings call. Citigroup expects to release its results at approximately 8 a.m. the same morning and discuss them at 11 a.m., according to the companies’ investor-relations announcements.
Their reports will be important for more than the banks’ own shareholders. Loan demand and consumer credit performance offer clues about activity across households and businesses. Credit-loss provisions can show how management is assessing repayment risks, while trading and investment-banking revenue can reveal the effect of market conditions on fee-generating businesses. These are questions the reports can address, not conclusions about results that have yet to be released.
The effect of interest rates on bank profitability is also less straightforward than a simple higher-rates-are-better assumption. Yields on loans and securities can support interest income, but banks must also contend with deposit costs, funding competition and the creditworthiness of borrowers. Management commentary on those pressures may matter as much as the headline earnings figures, particularly after the Fed’s September rate increase.
Because the VIX is based on broad S&P 500 option prices, bank earnings alone cannot be assumed to determine its direction. Investors may instead reassess risks across sectors as results and outlooks accumulate. The opening bank announcements will provide an early look at third-quarter conditions, but they cannot stand in for earnings from technology, industrial or consumer companies.
Tuesday’s first scheduled results will give investors concrete figures on banking activity before Wednesday’s 8:30 a.m. CPI release provides the next official reading on consumer-price pressures. Until those announcements arrive, Monday’s higher VIX is best understood as a measured increase in expected volatility, not proof of how either report will turn out.
More from Investing
Latest News
View all news- Brent Crude Climbs Above $106 as Middle East Supply Concerns Intensify
- U.S. 30-Year Mortgage Rates Hover Near 7.55% as Housing Borrowing Costs Remain Elevated
- U.S. Gasoline Averages About $4.36 a Gallon, More Than $1 Above a Year Earlier
- Wall Street Trades Mixed as Oil Prices Rise Ahead of Major Bank Earnings
- UK Government Announces More Than £1 Billion in Deals Linked to India Trade Mission
