Washington State’s New Insurance Claims Rules Take Effect October 18
Insurers face expanded claim-file access, clearer investigation notices and new requirements for vehicle inspections and repair estimates.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy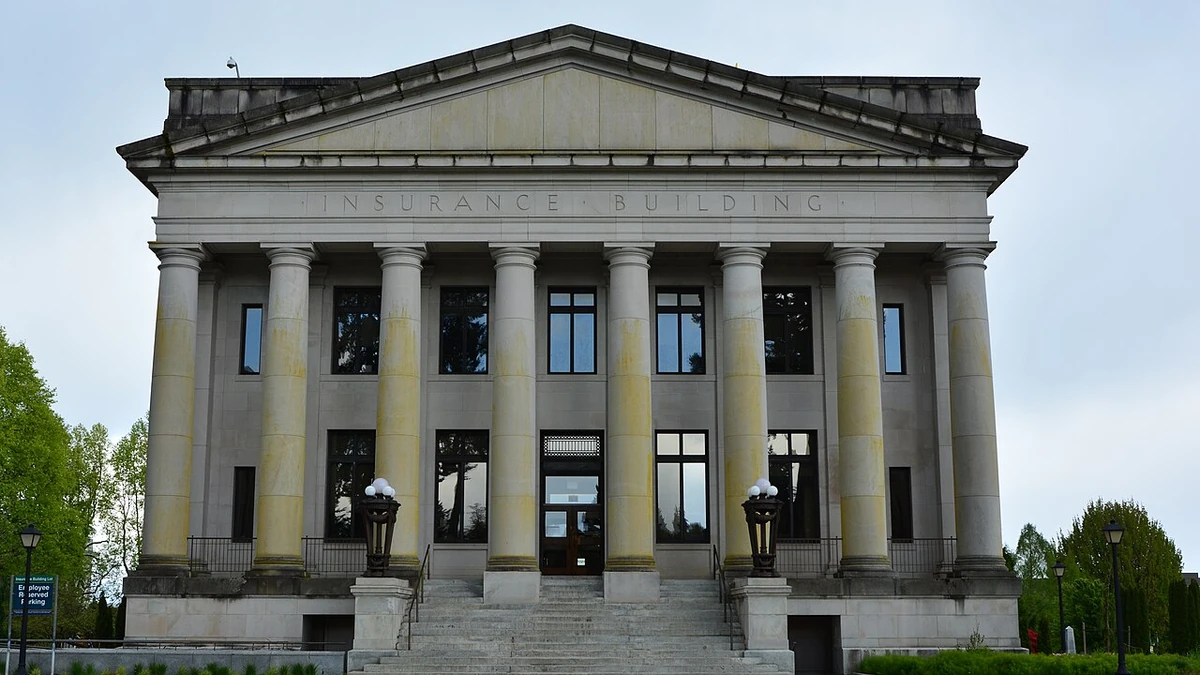
Washington state’s revised insurance claims rules take effect Sunday, October 18, giving policyholders broader access to claim records and requiring insurers to explain delays, coverage decisions and the numbers behind some damage estimates.
Insurance Commissioner Patty Kuderer adopted the amendments on August 18. They revise 15 sections of Washington’s unfair claims settlement practices regulation, covering investigations, communications and settlements. The changes address claims made under a customer’s own policy as well as certain claims against another person’s insurer, although individual protections vary by type of claim.
The final adopted rule places particular emphasis on how insurers determine whether a loss is covered and what they owe if it is. It sets standards for reasonable investigations, including situations where companies use software or photographs to assess damage. The changes regulate claims handling; they do not, by themselves, add benefits to an insurance policy.
More access to claim records and explanations for delays
One of the clearest changes gives insured customers a right to request portions of their first-party claim file at reasonable intervals. Insurers must provide the appropriate requested materials within 15 business days. The records can include adjuster notes, estimates, contractor and engineering reports, photographs, measurements and other documents used in handling the claim.
That access is not unlimited. Insurers may redact legally privileged material, third-party financial information and certain records whose release would compromise a reasonable investigation of alleged criminal activity. They must tell the insured when documents have been withheld or redacted for those reasons. If the company considers a request unreasonable, it must explain that decision in writing. The specific file-access provision is for first-party insureds, not a blanket entitlement for every person making a third-party claim.
The regulations also spell out response times. An insurer generally must acknowledge notice of a claim within 10 business days for an individual policy or 15 business days for a group contract. Other communications from claimants that reasonably call for a reply carry the same respective deadlines. When the insurance commissioner’s office asks a company about a consumer complaint, the company’s response deadline is now 10 business days, reduced from 15 working days.
An investigation ordinarily must be completed within 30 calendar days after a claim is reported, unless it cannot reasonably be finished in that period. If more time is needed, the company must provide a written explanation and, while the matter remains open, further written updates every 30 days. Those updates must address material developments, including items still needed to finish the investigation and whether a replacement adjuster has reviewed the file.
For first-party claims, the insurer also generally has 30 calendar days from notification to say whether the claim has been accepted or denied. If it cannot make that determination, it must explain why and provide continuing updates. The time frame is not an unconditional promise of payment within 30 days, and the regulations specify exceptions, including for medical professional liability claims. A denial based on a policy exclusion or condition must identify the relevant policy language in writing.
Vehicle inspections and repair estimates face tougher scrutiny
The new rules are especially detailed for automobile damage. Insurers cannot require a claimant to agree to a photo-only inspection as a condition of coverage. If a claimant initially uses a virtual inspection and disputes the resulting damage amount, the company must accept a request for an in-person inspection and conduct it within five business days, unless the parties agree to a different time.
Insurers must tell claimants at the start of a vehicle claim that they can request an in-person inspection. When submitted photographs do not establish particular damage, the company must make reasonable efforts to obtain additional documentation before rejecting coverage for that damage. These requirements allow insurers to use technology but limit their ability to treat a remote assessment as the final word in a disputed case.
Repair shops and drivers receive additional procedural protections. Insurers must respond in writing to a claimant and the repair facility within five business days after receiving supplemental damage estimates and the final invoice, explaining covered amounts and the basis for rejected items. They also cannot force customers or repair facilities to use only an internet-based claims application. Email, postal mail, fax and in-person delivery must remain available ways to submit information.
The responsibility for an accurate estimate remains with the insurer, including when the evaluation is produced on its behalf. An insurer may not deny or refuse to pay a claim without a reasonable investigation, and such an investigation cannot rely solely on a database or estimating software. If pricing data from a survey, software or benchmark is used for labor or materials, claimants can request the date and location of data collection and the businesses that supplied the underlying cost information.
Total-loss valuations receive closer documentation requirements as well. Reports must identify comparable vehicles, relevant prices and the information used to determine a damaged vehicle’s actual cash value. When a valuation reduces the payment based on a comparable vehicle’s condition, the insurer must provide supporting photographs and documents on request. Evidence is also required when the company deducts value because of the damaged vehicle’s condition.
Homeowners may see more detailed explanations too. When an insured has a policy duty to prevent additional property damage and submits a proposed scope of mitigation, the insurer generally has five business days to approve it or provide an approved alternative. Rejections must explain the technical or industry standard at issue and itemize disapproved amounts. These requirements concern claim administration rather than a guarantee that every proposed repair cost will be covered.
Complaints and changing technology prompted the overhaul
Washington’s insurance regulator says automobile and homeowners’ claim volumes were broadly consistent over the preceding six years, even as consumer complaints and notices under the state’s Insurance Fair Conduct Act increased. Such notices indicate an intention to pursue legal action against an insurer. The agency cited consumer testimony from a 2023 public meeting, along with concerns about delays, incomplete investigations and the increasing use of automated and photo-based assessments.
The adopted amendments also change the framework used to identify unfair claims settlement practices. An earlier provision referred to misconduct occurring frequently enough to show a general business practice. The revised purpose section removes that frequency qualification. This makes the regulatory language more direct, but it should not be read as automatically determining the outcome of an individual lawsuit or establishing that every disputed settlement is unlawful.
One limit matters when assessing the final package of changes. During the rulemaking process, the commissioner removed a proposed definition of ‘undisputed amounts’ and a related proposed unfair-practice provision. That abandoned proposal is not part of the rule taking effect October 18, so the adopted amendments should not be described as creating a new, separate requirement to pay every undisputed portion of a claim under that provision.
For people with an unresolved claim, the practical significance is the greater amount of information they can request and the written record the insurer must maintain when it needs more time or disagrees over valuation. The insurance commissioner’s office accepts consumer complaints and can seek an explanation from a carrier, although its complaint process does not itself decide the amount owed on a contested claim. The new standards give regulators more specific conduct to examine when those disputes arise.
More News
Latest News
View all news- Japanese Investors Outline $1.2 Billion Tourism Investment Plan in Bangladesh
- Israel Revises Second-Quarter GDP Growth Up to 15.4% in New October Estimate
- French Retailers Estimate Hundreds of Millions of Euros in Damage After Nationwide Protests
- Australian Government Commits A$6 Million to Western Australia’s Telethon
- Anthropic Co-Founder Cites Scenario of $44 Trillion U.S. GDP by 2030 as AI Advances