Charter Unveils $2 Billion Annual Cost-Savings Plan Alongside Third-Quarter Results
The 18-month expense target is separate from expected Cox acquisition synergies, as comparable revenue and internet customer numbers declined in the third quarter.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy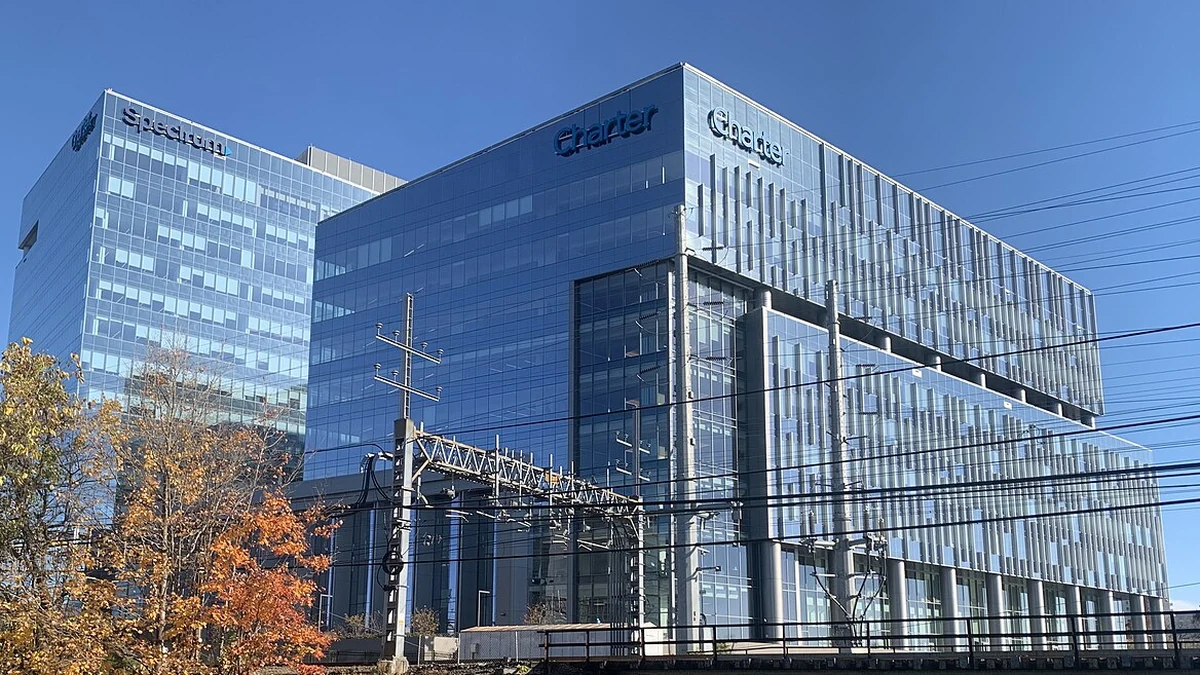
Charter Communications has set a target of $2 billion in annualized operating expense savings over the next 18 months, announcing a broad overhaul of its business alongside third-quarter results that showed continued broadband customer losses. The target is separate from more than $1 billion in cost synergies the cable and internet provider expects from its acquisition of Cox Communications.
The announcement on November 6 puts a larger expense-reduction effort at the center of Charter’s attempt to return to customer growth. It is a goal, not savings the company has already realized, and it arrives as the expanded business faces pressure on revenue and its core internet subscriber base.
Third-quarter revenue rose on an as-reported basis because Charter owned Cox for part of the period. On a pro forma basis that includes Cox in both comparable periods, however, revenue fell 1.5% from a year earlier. The distinction is important in judging whether the acquisition is masking weakness in the underlying business.
Broadband customer losses remain the central pressure
Charter lost 233,000 internet customers during the quarter on a pro forma basis. That comprised a loss of 156,000 at legacy Charter operations and 77,000 at legacy Cox. The expanded company ended September with 34.3 million internet customers, according to Charter’s third-quarter earnings announcement.
The figures help explain why management is changing more than its cost structure. Charter plans to adjust how it markets and sells its internet service and to improve installation, service delivery and customer retention. Those initiatives are intended to address the loss of connections, rather than simply offset lower revenue with reduced spending.
Mobile service provided a counterweight. Spectrum added 508,000 mobile lines on a pro forma basis during the quarter, including 440,000 at legacy Charter, bringing the total to 13.5 million lines. Video customer losses also moderated: the company reported a pro forma decline of 77,000 video customers, compared with 121,000 in the year-earlier quarter. Even with that improvement, the video base continued to shrink.
The revenue mix shows why adding mobile lines does not immediately solve the broadband problem. Pro forma internet revenue fell 3.7% to $7.1 billion, while mobile service revenue increased 17.3% to about $1.2 billion. Across the residential business, pro forma revenue declined 4.1% to $12.2 billion. The average monthly residential revenue per customer was $117.85, down 1.6%, although changes in the way streaming-app costs were reflected in video revenue also affected that comparison.
Charter plans a wider operating overhaul
The proposed $2 billion in annualized savings is a run-rate target. In practical terms, Charter wants its ongoing operating expense base to be lower by that amount once the program is implemented; it is not forecasting that $2 billion will be saved in cash during the current year. The company gave itself 18 months to reach the target and said the effort would sit alongside, rather than replace, the expected Cox acquisition synergies.
Management identified three broad areas for reductions: ending activities it considers nonessential, simplifying organizational structures and making greater use of efficiencies available through vendor relationships. The announcement did not provide a division-by-division savings schedule or a specific headcount reduction target. That leaves the eventual mix of staffing, procurement and operating changes unclear.
The new model also changes Charter’s commercial priorities. Management wants to strengthen the appeal of its core internet offering and use mobile and video products to increase the value of each customer relationship. Better retention could help protect revenue, but that outcome depends on execution in markets where fiber and fixed-wireless competitors offer alternatives to cable broadband.
There is a trade-off for the company to manage. Lower costs could improve profitability even if subscriber numbers remain weak, but savings that reduce the quality or responsiveness of customer service could make the growth objective harder to achieve. Charter’s announcement presents both aims as part of the same operating redesign; it has not yet demonstrated their combined financial effect.
Cox makes reported growth harder to compare
Charter completed its acquisition of Cox Communications on August 19, adding more than 11 million serviceable locations and over 5 million customer relationships. Cox operations entered Charter’s actual financial results from August 20 through September 30, while the pro forma comparison treats Cox as part of the group for the full periods being compared. The two presentations therefore answer different questions.
On the actual basis used in Charter’s financial statements, revenue increased 9.1% to $14.9 billion, and adjusted EBITDA rose 6.9% to $5.9 billion. Those gains largely reflected the newly acquired Cox business. With the same operations included in both periods, pro forma revenue slipped to $16.5 billion and adjusted EBITDA declined 4.0% to $6.6 billion. Adjusted EBITDA is Charter’s non-GAAP performance measure, not its reported net income.
Pro forma operating costs and expenses rose 0.2% year over year to about $9.9 billion. That is a relatively small change in the expense total, but it occurred alongside declining revenue. The result was pressure on operating earnings before the new savings initiative had begun to deliver its targeted benefits.
The acquisition also enlarged Charter’s opportunity to sell Spectrum services in former Cox markets. In September, the company introduced Spectrum products, prices and packages across the legacy Cox footprint. Charter reported stronger demand and improving customer trends in those markets after the launch, but the overall pro forma figures still showed a net loss of internet customers for the quarter.
A large impairment sharpens the cash-flow focus
The quarter’s net loss attributable to Charter shareholders totaled $2.4 billion on an actual basis, compared with net income of $1.1 billion a year earlier. A $6.3 billion pretax franchise impairment charge was the main reason for the loss. In its quarterly regulatory filing, Charter described that charge as noncash and said its valuation reflected lower expectations for future customer and revenue growth, along with assumptions about the replacement cost of network assets.
That accounting charge did not represent a $6.3 billion cash payment during the quarter. It nonetheless provides another indication of the weaker outlook for parts of Charter’s existing business. The impairment analysis was performed before the Cox acquisition closed and did not include the newly acquired assets, according to the filing.
Cash generation offers a more immediate measure of the company’s ability to finance its network and manage debt. Actual operating cash flow fell to $4.0 billion from $4.5 billion a year earlier, which Charter attributed to the timing of cash tax payments and one-time expenses associated with the Cox acquisition. Free cash flow was $674 million, down $947 million year over year, reflecting the lower operating cash flow and an unfavorable change in accrued capital spending.
Actual capital expenditures totaled $3.0 billion in the quarter. On a pro forma basis, spending declined to $3.2 billion from $3.6 billion in the comparable period. Charter expects approximately $13.0 billion in pro forma capital expenditures for full-year 2026, excluding transition capital spending, though the final figure remains dependent on network projects, supply conditions and business growth.
At September 30, Charter reported $108.6 billion in principal debt and $573 million in cash. It also said its credit facilities provided about $2.4 billion of additional liquidity. Against that balance sheet, the new expense target is intended to support stronger free cash flow, but any benefit will depend on how quickly the reductions take effect and whether Charter can stabilize its internet customer base.
The next measurable step is the company’s progress toward its 18-month annualized savings target. Future quarterly results will show whether costs are coming down while broadband subscriber trends improve, rather than merely whether the expanded company reports more revenue following the Cox acquisition.
More from Investing
Latest News
View all news- U.S. Consumer Sentiment Rises to 51.0 in November as Inflation Expectations Ease
- USDA Finalizes WIC Rule Allowing Online Grocery Orders and Digital Payments
- U.S. Commerce Publishes Final Antidumping Duty Review Results for Vietnamese Shrimp
- Sweden’s October Budget Deficit Comes in Below Forecast at SEK 14.5 Billion
- UK Public Service Productivity Grows 0.3% Over the Year to June, ONS Reports